Office: (404) 975-4800

News

semi truck parking business

How to Start a Semi-Truck Parking Business

semi truck parking business

Starting a semi-truck parking business can be a great idea. As long as you find an area with strong demand for truck parking, you can start a profitable and rewarding business, helping truck drivers and truck companies with a space for their vehicles.

There are many considerations when starting a semi-truck parking lot. There are also many different types of public parking options you can offer to truck drivers.

If you’re interested in getting this kind of business off the ground, here are some of the main steps you’ll need to follow.

Semi Truck Parking Business: Steps to Success

Perform Market Research

The first step to starting a semi-truck parking business is to perform in-depth market research. The better you understand the market, the more easily you’ll be able to identify the right truck parking lot opportunity.

When researching this, there are a few key considerations. These include:

  • Understanding what type of truck parking lot you will set up (how large it will be and what types of vehicles you will be able to accommodate)
  • Identifying areas where there is a truck parking shortage
  • Understanding what competitors exist in your area
  • Identifying your exact target audience (this could be long-haul truck drivers, food truck drivers, regional truck drivers, and so on)
  • Researching the feasibility of your semi-truck parking business and understanding what will be required to make your potential truck parking facilities profitable
hand writing

  • Performing in-depth market research is necessary for establishing a detailed business plan. This will help you understand exactly how you will be able to set up the truck parking lot, and what steps you will take to ensure your truck parking facility is profitable and makes sense for the market.

Understand Laws and Regulations

Truck parking lots need to comply with the relevant county and state zoning laws and regulations. These zoning regulations differ depending on your specific location and could include things like environmental standards and safety requirements.

It’s important to understand what regulations exist around creating proper truck parking in your area. This is necessary for finding the right location so that you can develop into a semi-truck parking business.

For example, your location might be restricted by residential neighborhood zoning issues, which prevent you from developing new truck parking lots.

Find the Right Location

When it comes to truck parking lots, location is everything.

You can offer high-quality facilities and great prices, but even the best truck parking spaces will stand empty if there’s no demand for them.

Make sure you develop your truck parking facilities where there are plenty of truck drivers actively looking for a place to stay. Of course, busier trucking routers have more demand, but that also means there’s more competition. Your goal is to strike the right balance between the two.

It’s a good idea to try to identify areas where there is a high rate of illegal truck parking.
road with truck

These areas present a great opportunity for a proper truck parking facility, as there is likely a truck parking shortage in these parts.

Beyond demand, there are various factors to consider when choosing the right place for your truck parking lot. These include:

  • The truck parking space dimensions available on the lot
  • What type of construction will be required on the space
  • What types of amenities are available on the truck parking lot
  • The legal compliance requirements for developing that land into a truck parking lot
  • Insurance requirements for turning the space into a truck parking lot
  • What exit ramps will lead to your parking stall
  • Whether there’s enough space for trailer parking, semi-tractors, and freight transportation
  • Whether the area is secure enough for overnight parking

Consider Franchises and Business Options

Once you’ve identified the ideal place for your truck parking lot, you’ll need to establish what approach you will take in starting your semi-truck parking business. The first question to ask is whether you’ll be operating a franchise, or starting your own business. Both options come with their pros and cons.

Starting a franchise means you get access to an already-established brand. You will also get plenty of support in setting up the business according to a proven business model. The downside is that you have less freedom over what you can do with your truck parking lot. Starting a franchise can also be expensive.

Put Your Business Plan Into Action
man shaking hand

At this stage, you should have a detailed business plan. Now, it’s time to unfold this plan and start implementing it.

You will need to discuss:

  • Finances: Ensure your truck parking lot has a detailed and sensible financial plan. Establish realistic financial projections and know what will be required to turn a profit. You may need to take on commercial financing to start the business.
  • Marketing: Know how you will market your semi-yard to attract truck drivers. This could include listing your business on truck parking apps, developing a strong presence in your area, joining truck driver networks, and developing a solid digital marketing strategy.
  • Get the right equipment: Your truck parking lot needs to be kitted out with the right amenities for fatigued truck drivers. This includes everything from restrooms to washing facilities and security cameras.

Establish Your Business

When you have a solid truck parking lot idea that you’re ready to execute, you’ll need to establish your business. This involves setting up the right business structure, applying for all of the relevant permits, and ensuring your truck parking business meets all of the right legal requirements.

At this stage, you might need to take on staff, set your business up with insurance, establish a brand, and so on. This is the part where your truck parking lot starts coming together.

Conclusion

There’s a lot of thought and planning that goes into establishing truck parking facilities. Get it right, and a semi-truck parking business can be a lucrative opportunity.

By carefully following the steps and considerations above, you should be able to establish the perfect truck parking lot business based on your interest, area, and market.

If you’re looking to purchase a semi for yourself, reach out to Mission Financial Services today.


how to start semi truck with bad starter

How To Start A Semi Truck With A Bad Starter

how to start semi truck with bad starter
Hey there, truckers and gearheads! We all know how frustrating it can be when you’re ready to hit the road but your semi-truck starter decides to take a little vacation.

Don’t worry! We will walk you through some handy tips and tricks to get your big rig roaring back to life, even with a stubborn starter.

So, grab a cup of joe. Sit back, and let’s show you how to start a semi-truck with a bad starter.

What Does A Semi-Truck Starter Do?

A semi-truck starter is a crucial component of your vehicle’s ignition system. Its primary function is to turn the engine over and get it started.

When you turn the key in the ignition, the starter motor receives an electrical signal from the battery. It uses that power to crank the engine, which begins the combustion process.

The starter is composed of a motor, a solenoid, and a small gear called a pinion that engages with the engine’s flywheel to start it spinning. Once the engine is running, the starter disengages and the engine takes over, continuing to run under its own power.

So, the starter is responsible for getting the engine going, which is a pretty important job! If the starter malfunctions or fails, the engine won’t be able to start, leaving you stranded and needing some repair work.

How To Care For A Semi-Truck Starter

Here are some valuable tips for caring for your semi-truck starter and preventing potential issues down the road:

White truck with fire on top


  • Keep the battery in good condition: A healthy battery is vital for the proper functioning of the starter. Regularly inspect the battery terminals for corrosion or flimsy connections. Clean the battery as needed and ensure the fittings are tight. Monitor the battery’s charge level and have it tested regularly to ensure the battery delivers sufficient power to the starter.
  • Avoid overloading the electrical system: Excessive use of electrical accessories, such as lights, radios, or power-hungry devices, can strain the starter and the overall electrical system. Be mindful of your power consumption and avoid unnecessary loads that could impact the starter’s performance.
  • Practice good starting habits: When starting the engine, avoid holding the key in the start position for an extended period. This can cause unnecessary strain on the starter motor and lead to premature wear. Instead, start the engine smoothly, releasing the key as soon as it fires up.
  • Regularly service and maintain the starter: Include the starter in your routine truck maintenance schedule. Consult your vehicle’s manual or a trusted mechanic to determine the recommended maintenance intervals for the starter. This may involve cleaning, lubricating, or inspecting specific components to ensure optimal performance and longevity.
  • Address electrical issues promptly: If you notice any electrical problems, such as dimming headlights, flickering dashboard lights, or slow cranking when starting the engine, address them promptly. Ignoring these warning signs could put additional strain on the starter and lead to more severe issues.

truck on road

  • Protect the starter from moisture and debris: The starter is located in the engine compartment, where it’s exposed to moisture, dirt, and debris. Take measures to protect it by keeping the engine compartment clean and free from excessive grime. Consider using protective coverings or shields designed for starters to prevent water or debris from directly contacting the unit.
  • Perform regular inspections: Inspect the starter for any visible signs of damage or wear. Look for loose connections, frayed wires, or any physical damage. Address any issues promptly to prevent further complications.

Remember, a little preventive care goes a long way in keeping your starter healthy and your truck running smoothly.

How To Start A Semi-Truck With A Bad Starter

A bad starter is among the most common truck problems! If your starter is a bad starter, try any of these ways to start your semi-truck.

Give It A Gentle Tapping

Sometimes, all your starter needs is a little encouragement. No, we’re not suggesting you take a hammer and hit it! Instead, give the starter a few gentle taps with a wrench or a rubber mallet. This can help free up any stuck gears or brushes that might be causing the problem. Just be careful not to hit it too hard; we’re looking for persuasion, not destruction!

Try The Auxiliary Start System

Many semi-trucks have an auxiliary start system, also known as a ‘start assist’ or ‘jump start’ feature. This nifty little system can be a lifesaver when your starter is on the fritz.

truck

Typically, you’ll find a dedicated button or switch labeled ‘auxiliary start’ somewhere in your truck’s cabin. Engage this switch, and it will bypass the primary starter, allowing you to start the engine using a secondary power source. It’s like having a backup plan for your backup plan!

Push-Start To The Rescue

Fear not if you find yourself stranded without the luxury of an auxiliary start system! Push-starting your semi-truck can be a viable option in certain situations. Here’s how to do it:

  • Gather a few strong, willing souls to help you out. Teamwork makes the dream work, after all!
  • Choose a flat or slightly downhill area with plenty of room to get rolling.
  • With your truck in neutral, have your helpers push the truck to a reasonable speed (about 5-10 mph).
  • Once you’ve gained enough momentum, quickly shift into a lower gear (typically second or third) and let out the clutch. This sudden engagement of the transmission can kick-start the engine.

If all goes well, your engine should roar back to life! Hooray for perseverance and good ol’ human power!

Seek Professional Assistance

If all else fails and your starter remains stubborn or uncooperative, it may be time to call the professionals. Reach out to a reliable mechanic or roadside assistance service to diagnose and fix the issue. They have the expertise and tools necessary to safely get your truck back on the road. Remember, it’s always better to be safe than sorry!

Final Thoughts

Starting a semi-truck with a bad starter might sound like a headache, but with the proper knowledge and a can-do attitude, you can overcome this obstacle.

Just remember, there’s no harm in seeking professional help.

If all else fails and it’s time for repairs, learn more about semi-truck repair loans, and ensure your rig stays in tip-top shape. Keep your spirits high, stay safe on the road, and happy trucking!

For the best advice on semi truck financing, head on over to Mission Financial Services.

How Hard Is It for Minority Truck Drivers to Obtain Financing

How Hard Is It for Minority Truck Drivers to Obtain Financing?

How Hard Is It for Minority Truck Drivers to Obtain Financing

Minority truck drivers often face unnecessary difficulties in securing financing for starting a trucking company. There shouldn’t be barriers in place preventing minority drivers from entering the transportation industry!

As long as you work with the right vehicle financing company, obtaining funding for your truck doesn’t have to be a challenge.

In this guide, we’ll explore whether minority truck drivers face funding challenges, and provide a step-by-step process on how to get around this.

Minority Truck Drivers: Who is a Minority Truck Driver?

Of all the truck drivers in the United States, over 84% of them are men, and over 58% are white. These trucking industry professionals are considered the majority.

Minority truck drivers refer to any professional driver that falls outside of this category. This includes women truck drivers, or truck drivers of different genders, sexualities, and racial backgrounds. For example, Latino or Hispanic, Asian, and Black truck drivers can all be considered minorities.

While these minority drivers were once a rarity in the transportation industry, trucking is becoming increasingly diverse. There’s greater minority representation across the industry, which means more career opportunities are presenting themselves for minority drivers in the trucking industry.

Is it Harder To Obtain Financing as a Minority Truck Driver?

Despite increasing diversity in the trucking industry, minority-owned trucking companies still face many added difficulties in securing financing. This is because minority groups tend to be marginalized socially and economically.

truck driver

Some minority truck drivers face discrimination in the form of refusal to be assisted, while some may face harsher application requirements. Some minority truck drivers have a weaker economic background than others and will be disadvantaged by financing options that require a strong credit history or a long history of stable bank statements.

This makes it harder to obtain financing than those who are not marginalized.

With so many owner-operated trucking companies operating in the country, restricted access to funding can make it very difficult for minority truck drivers to pursue innovative ideas and start a transportation company. This will continue to create a divide in the trucking industry.

Obtaining Truck Financing as a Minority Truck Driver

While obtaining funding as a minority truck driver may seem like a major challenge, with the right financing provider it doesn’t have to be.

Mission Financial does not discriminate against minority truck drivers and works hard to help everyone secure vehicle loans. When buying a semi-truck with financing through Mission Financial, bad credit or a lack of financial history is not taken into account. This provides a far more equal playing field for any truck drivers to get into the industry.

Here are the steps you can take as a minority truck driver to easily gain funding for your transportation business.

1. Determine Your Eligibility

The first step in securing financing for your truck is to determine your eligibility. This is where most minority truck drivers have a hard time. With Mission Financial, earning your eligibility success is an easier process.

man in truck

Four main factors are considered when determining your eligibility. These are:

  • Overall credit: Like with any financing provider, having a strong credit history will make it easier to secure funding. However, Mission Financial is a common sense lender, which means we consider more than just your credit score. This means we review your overall credit situation to understand your eligibility. Even if you have a bad credit history, it’s still possible to gain truck financing.
  • Down payment: The down payment required is based on the cost of the truck, and is usually around 20% – 30% of the truck’s purchase price. Mission offers financing on various older truck models, so paying a down payment on a brand-new truck is not necessary.
  • Time with CDL: The longer you’ve had your Commercial Driver’s License (CDL), the easier it will be to obtain funding. Drivers who’ve had their CDL for less than three years may need to pay a larger down payment.
  • Truck’s age: Mission Financial finances trucks that date back to 2000, so it’s possible to gain financing for a second-hand vehicle. However, it’s important to also consider the higher cost of maintenance and repairs if you do choose to finance an older truck.

2. Get Your Documents Together

Once eligibility has been established, you’ll need to prepare all of your documents for obtaining funding. This will help you quickly apply for a loan when you find the right truck.

Your documentation should include your:

  • Bank statements and tax returns
  • Your CDL
  • At least six references
  • Contact details
  • Proof of insurance

woman with truck

Depending on your employment situation, you may also need to provide:

  • A co-signer statement
  • LLC agreement and operating agreement
  • Articles of Incorporation and corporate resolution

3. Find Your Vehicle

When you are prepared to apply for financing, you’ll need to find your truck and negotiate its price. Make sure you carefully choose the right type of vehicle for the type of trucking business you plan to start.

4. Obtain Insurance

You’ll need to provide proof of insurance to finalize your truck financing process. Make sure to select the right type of insurance policy based on your vehicle and the type of business you operate.

5. Submit Your Documents

Once you have all of the above documentation sorted, you simply need to submit your documents to Mission Financial to get approved for truck financing.

Final Thoughts

If you want to quit your driving job and start your own trucking company, you’ll need to obtain funding. With minority truck drivers at an all-time high, there are various opportunities for new truckers to obtain funding and start their own trucking organizations.

This can help minority members of the industry achieve greater success!

By working with an organization like Mission Financial, anyone can obtain the funding they need. We have a commitment to providing fair funding opportunities to all professional drivers. Apply now to kickstart your trucking business success.

semi trucks for sale with financing

Where To Find Semi-Trucks For Sale With Financing

semi trucks for sale with financing

Has your semi-truck credit application been approved? Are you ready with your downpayment? We have great news if you want to learn where to find semi-trucks for sale with financing! Joining thousands of owner-operators in the trucking industry is a fantastic idea.

We’ll show you where to find semi-trucks for sale with financing, discuss the best places, and ensure you get your rig!

The Importance Of Finding Semi-Trucks With Financing

Investing as a semi-truck driver is a significant expense; only some have the cash flow to purchase one outright. That’s why finding semi-trucks for sale with financing is important.

Semi-truck financing allows you to spread the cost of the truck over time. This approach makes it more affordable and manageable for your business. However, some financing will require down payments.

Additionally, a loan can help you build credit, which can be beneficial when seeking funding for future business expenses. This financing allows you to grow your company and stay competitive.

Places To Find Semi-Trucks For Sale With Financing

With your first-time buyer semi-truck loan in hand, here are some places to approach for your future semi-truck purchase:

Dealerships

Dealerships are the most popular and common places to buy semi-trucks. These dealerships specialize in selling commercial trucks and have a wide range of inventory. They offer a variety of brands, models, and years. Here are some benefits of buying from a dealership:

load transportation

  • Wide Selection: Dealerships offer a wide selection of semi-trucks. This variety can be helpful when looking for a specific make, model, or year.
  • Warranty and Service: Dealerships often provide warranties and services for their semi-trucks. This can benefit drivers, giving them peace of mind knowing they can get their trucks serviced and repaired at the dealership.

Buying a semi-truck from a dealership can be an excellent option for drivers looking for a wide selection, warranty and service, and trade-in options.

Online Marketplaces For Semi-Trucks

Online marketplaces for semi-trucks have become increasingly popular. Websites like Truck Paper and Commercial Truck Trader are some of the most well-known platforms.

The benefits of shopping for semi-trucks on these online marketplaces are numerous. These platforms offer many truck models for sale. The variety makes it easier for buyers to compare and find the best one for their needs.

Many of these websites allow buyers to search for trucks based on specific criteria, such as make, model, year, and location. This can help make finding the right truck much more efficient.

Auctions For Semi-Trucks

Auctions are another option for those searching for semi-trucks for sale with financing. Here are some benefits of buying from auctions:

  • Competitive prices: Auctions offer competitive prices, which can save you money compared to buying from a dealership or private seller.
  • Access to exclusive inventory: Auctions sometimes have exclusive inventory that is not available anywhere else. This means you can purchase a rare or unique semi-truck that fits your needs perfectly.

Buying from auctions can be an excellent choice for those who want to find a good deal on a semi-truck.

Private Sellers

Private sellers can also be a good option when looking for semi-trucks for sale with financing.

signing a contract

Here are some benefits of buying from a private seller:

  • Lower prices: Private sellers are usually motivated to sell their trucks quickly and may be willing to sell for a lower cost than dealerships or online marketplaces.
  • Less competition: Since private sellers are less visible than dealerships or online marketplaces, there may be less competition for the trucks they sell.
  • Negotiation: Private sellers may be more willing to negotiate on the price. They may also have flexible terms of the sale since dealership policies or regulations do not bind them.

However, it’s essential to remember that buying from a private seller may also come with risks, such as limited warranties or guarantees and a lack of financing options. It’s important to thoroughly inspect the truck and ask for maintenance records before purchasing.

Become Your Boss With Mission Financial Services

We hope our information will help you find the perfect truck to suit your needs. Remember, at Mission Financial Services, we make the financing process easy, so you can focus on finding the right truck.

Whether you’re looking for a dealership, online marketplace, auction, or private seller, we’re here to help you every step of the way. Contact us today to pre-qualify to get started on your journey to owning your dream truck!

should i put my semi truck in my business name

Should I Put My Semi Truck In My Business Name (+ Other FAQs)

should i put my semi truck in my business name

Should I put my semi-truck in my business name? This is one of the most common questions from truck owners when purchasing a vehicle.

If you run a trucking company, your vehicles are your biggest and most important business asset. Owning trucks comes with many costs: insurance, maintenance, taxes, and more.

This means you need to be smart about how you purchase and register trucks. If you sensibly do this, you can optimize your expenses.

In this guide, we’ll cover whether you should put your truck in your personal or business name, as well as some related questions.

Should I Put My Semi Truck in My Business Name?

If you own a semi-truck as a business vehicle, one of the most common questions you’ll ask yourself is whether you should put your semi-truck in your business name or keep it as a personal asset.

While there’s no right or wrong answer, there are advantages to taking either approach.

Why Put Your Semi-Truck in Your Business Name?

Putting your semi-truck in your business name lets you separate the truck from your personal self. This can offer valuable protection of your personal assets in case something happens.

For example, if someone files a lawsuit against you, they could go after your truck as it is your personal property.

long road

This kind of issue can happen in the event of financial troubles or even a divorce. If your truck is registered as a business asset, it’s separated from your personal self. This means the truck is protected.

If you have a poor financial history or credit rating, then it could also be worth registering your truck as a business asset. This can make it easier to gain semi-truck financing for your business – instead of applying for it personally. This can also help you access semi-truck repair loans.

If you own a trucking company with multiple vehicles, then it makes sense to register these vehicles as business assets. This will help you provide coverage for all of your business vehicles more easily. It also reduces any risks associated with owning these vehicles, which can be big when you have multiple trucks.

Why Keep Your Semi-Truck in Your Personal Name?

The main reason why putting your semi-truck in your personal name is a good idea is that it’s easy.

If you are an owner-operator, there’s a good chance your business might be operating as a sole proprietorship. In this case, you have no choice but to register the truck in your name as there is no separation between yourself and your business.

In many cases, owner-operators will purchase a truck first and then register the business. In this case, the truck will first be placed under the owner’s personal name, which can make transferring the truck to your business difficult.

person reading contract

Personal or Business: Which is Best?

While it’s often easier to register your semi-truck in your name, it’s generally considered a smarter move to register it under your business. Doing so helps to protect your truck as a business asset and legally separates you from your truck in case any issues arise.

Owning the truck as a business vehicle can be beneficial for tax purposes, as maintenance costs associated with the truck can be recorded as business expenses.

Of course, one important consideration also comes down to whether you have business partners or not. If you do, then registering the truck under your business will give them a share of ownership of the truck. If it’s just you that runs the business, then this is an easier decision to make.

If you’re considering registering your truck as a business asset, it’s important to first consult with a business lawyer on the matter. They will be able to offer specific advice based on your business and personal situation.

How Does Commercial Auto Insurance Work?

If you’re wondering whether you should put your semi-truck in your business name, you’ll also want to consider commercial auto insurance.

Properly insuring your semi-truck is essential, and one of the best ways to do this is through a business vehicle insurance policy.

This type of insurance only applies to business vehicles, so you can’t access these policies if the trucks are registered as personal assets.

signing document

If your truck is registered as a personal asset, then you will also need to insure it under your personal name. Many household and vehicle insurance providers don’t have policies for semi-trucks unless they’re used as business vehicles. This can make insuring the truck a complicated and expensive process.

Commercial auto insurance gives you higher insurance amounts and will help you cover the vehicle under circumstances where a personal insurance policy wouldn’t pay the claim. This includes insurance coverage of the vehicle but also insurance for things like injuries, property damage, or collision insurance.

If your employee drives the truck and gets into an accident, then your commercial auto insurance will pay out. If the truck is insured under your name, then claiming for accidents involving other drivers can be very difficult. You might not be able to claim from a personal policy at all if you were using the truck as a business vehicle.

Commercial auto insurance can be significantly more expensive than personal insurance policies. This is because of the extra liability a trucking company has compared to a personal vehicle.

Of course, this all depends on your specific insurance policy and provider. However, as a working business vehicle, you’ll probably want to have commercial auto insurance on your semi-truck.

Should I Buy a Semi-Truck as a Business Expense or Out of My Budget?

Beyond thinking about how you will register your semi-truck, you also need to consider how you will purchase and finance the truck. Should it be a personal or business expense?

misty road

Many businesses purchase a business car, and for very good reason. By purchasing the semi-truck as a business expense, you can record your mileage and operating costs as business expenses. This can help you access some tax benefits.

Sure, you can still track your truck’s mileage and separate personal mileage from the mileage your trucking company racks up. However, it will be a lot easier to do this if the truck is a business expense.

Separating the truck financing as a business expense can also make it easier to manage your business’s finances and separate your business expenses from your personal expenses. If you finance the truck from your personal bank account and name, separating the truck as a business expense can get tricky.

However, whether you should purchase the truck as a business or personal expense comes down to your individual situation. Consider how your business is structured, and how you plan on financing the vehicle.

It’s best to speak to your tax practitioner about this to see how the cost of the vehicle can help you with taxes.

If you do purchase the vehicle under your business name, just be prepared for a different process. You’ll have to produce the right documents and ensure the vehicle is registered to the address on file with the Department of Revenue.

Should You Transfer Your Semi-Truck to Your Business?

hand

If you already own a semi-truck as a personal asset, you might want to transfer it to your business. This often happens if someone starts as a sole proprietor and then registers their trucking company as an LLC later down the line.

If you do plan to transfer ownership of the vehicle, there are some important things to keep in mind. Most importantly, the cost.

If you want your vehicle in your business name, you’ll have to repay the taxes associated with the value of the vehicle. This is because you will have to resell the vehicle from yourself to your business.

Even if you only sell the semi-truck to your business for $1, there are still taxes involved. By transferring the vehicle, you’ll have to pay these taxes for a second time. This can be an annoying and significant expense.

Should You Buy or Lease Your Vehicle?

The question of whether to buy or lease your semi-truck is one of the first things to consider when acquiring a new vehicle. As always, both options come with their advantages and disadvantages.

The obvious advantage to leasing a truck is that it’s more affordable in the short to medium term. If you don’t have a large down payment to make on the vehicle, you can start to lease the semi-truck at a relatively low monthly cost.

Depending on the type of leasing agreement you enter, you may be able to take ownership of the truck at the end of the agreement. This could make leasing a vehicle financially viable.

hands writing

The other advantage is that there’s less risk involved because you don’t own the vehicle.

Buying a vehicle comes with the advantage of owning the semi-truck straight away. This means it’s your asset, and you can sell it if you want. You can also gain tax advantages from owning the vehicle more easily.

So, leasing may mean more affordable monthly payments, but buying gives you greater control over vehicle usage and mileage. As your semi-truck is the most important asset for your trucking company, buying the vehicle often makes the most sense. However, this does depend on your specific circumstances.

And then there’s the question of whether you should lease the vehicle in your business name or personal name. While leasing is different from purchasing outright, the same principles that we’ve covered above apply to this scenario. In summary, leasing it in your personal name has benefits, but leasing it in your business name is less risky!

Conclusion

Whether you should put your semi-truck in your personal or business name depends on your individual situation.

There are many factors involved, such as insurance, taxes, your business structure and accounting, employees, and how your vehicle is funded. There’s no right or wrong answer, it just comes down to what option offers the best advantages for your business and personal scenario.

Whatever the case, it’s always best to consult with professionals to help you purchase your semi-truck as efficiently as possible. If you have any questions about financing a semi-truck, consider approaching Mission Financial Services for top-tier assistance.

financing older commercial trucks

Can You Finance an Older Semi Truck? What to Know

financing older commercial trucks

Financing older commercial trucks can feel like an uphill battle. But it’s often the smartest way for owner-operators and small fleets to get on the road without overspending.

Many lenders hesitate to work with high-mileage or older models but the right financing partner can still help you land a dependable truck at a manageable payment.

Whether you’re buying your first used semi or adding an older rig, this guide covers the benefits and challenges. It also walks through current rates and the step-by-step process.

TL;DR

  • Older commercial trucks (5 to 15+ years old) come with tighter age and mileage caps than new truck loans. Expect higher rates and stricter paperwork too.
  • 2026 rates for semi-truck financing generally run from about 6% APR for well-qualified buyers. Borrowers with credit challenges may see 25% APR or higher.
  • A $70,000 truck loan typically runs $1,350 to $2,265 a month over a 60-month term, depending on your rate.
  • Mission Financial Services works with credit scores as low as 460. We evaluate each truck’s condition individually, not by a blanket age or mileage cutoff.

What Does It Mean to Finance an Older Commercial Truck?

Financing an older commercial truck means using a loan or lease on a vehicle that’s 5 to 15 years old. It often comes with six figures on the odometer.

New truck financing comes with strict credit and age requirements. Older truck financing instead focuses on getting you into road-ready equipment at a lower price point.

Semi-truck financing options range from traditional banks to specialized equipment lenders built for older rigs.

You’ll make monthly payments plus interest over an agreed term, just like with a newer truck loan. The difference is that many mainstream lenders cap the age or mileage they’ll finance. That’s why you need a lender that specifically offers financing for older rigs.

New vs. Used Commercial Trucks: Weighing the Trade-Offs

Choosing between a new and a used commercial truck comes down to price, risk, and upfront budget. Here’s how the two compare.

Factor New Truck Used or Older Truck
Purchase Price $170,000+ on average Around $61,000 on average
Loan Approval Stricter credit and income requirements Often easier to qualify, even with imperfect credit
Depreciation Loses value fastest in the first 2 to 3 years Already past the steepest part of the depreciation curve
Repairs and Technology Advanced emissions and telematics systems, costly when they fail Simpler systems, but repairs tend to happen more often
Warranty Coverage Usually covered under a manufacturer warranty Rarely covered; budget for repairs yourself
Financing Rates Often lower APRs from mainstream lenders Slightly higher APRs; a specialized lender usually helps

Where Used Trucks Win

Older trucks carry a smaller price tag, which lowers your financing burden. That frees up cash for fuel, insurance, and permits.

A smaller loan amount also makes approval easier, even with imperfect credit.

Where New Trucks Win

A new truck comes with a manufacturer warranty, so unexpected repair bills are less likely in the early years. Maintenance costs are also more predictable, since there’s no unknown history from a previous owner.

New trucks meet current emissions standards out of the gate, too, which matters as EPA 2027 approaches. That can mean fewer compliance surprises down the road, even though the upfront price is steeper.

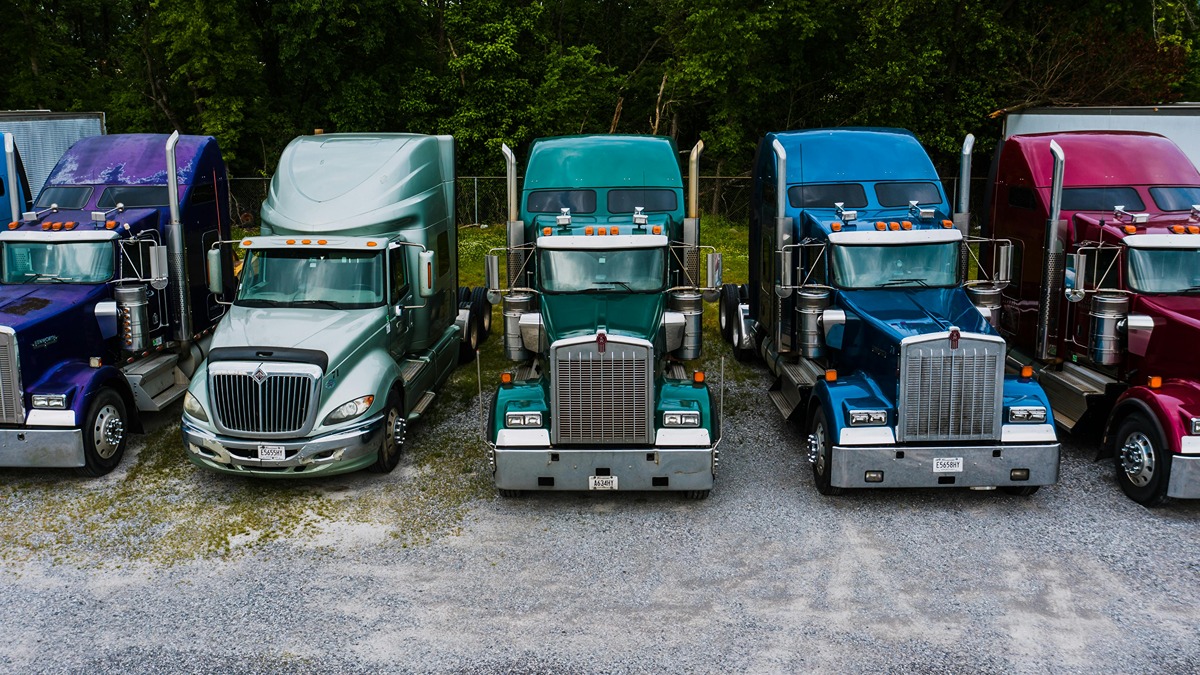
A lineup of semi trucks in different colors parked at a truck stop, representing the range of vehicles to evaluate when deciding to replace fleet vehicles

Why Do Some Lenders Avoid Financing Older Trucks?

Not every lender will finance an older commercial truck. Traditional banks often avoid them for three main reasons.

Age and Mileage Restrictions

Many lenders set strict limits on truck age and mileage. Older vehicles carry higher financial risk in a lender’s eyes.

As a truck accumulates years and miles, resale value drops and repair costs climb. That makes it harder for a lender to recover its money in a default.

For that reason, a traditional bank may refuse to finance a rig over 7 to 10 years old. The same goes for trucks with more than 700,000 miles on the odometer.

Safety and Emissions Standards

Older trucks may not meet current emissions or safety regulatory requirements, especially in states with strict environmental rules. Lenders see this as a risk.

Noncompliant equipment could face fines, operational restrictions, or costly upgrades. Any of those could affect your ability to keep up with payments.

Higher Risk of Breakdowns

The older the truck, the greater the chance of a breakdown. Lenders view this as a risk because the truck itself is the collateral.

If it loses value too quickly or becomes inoperable, the lender has less to recover in a default. This is why working with a specialized lender matters. We understand the realities of older equipment and offer financing even when other companies won’t.

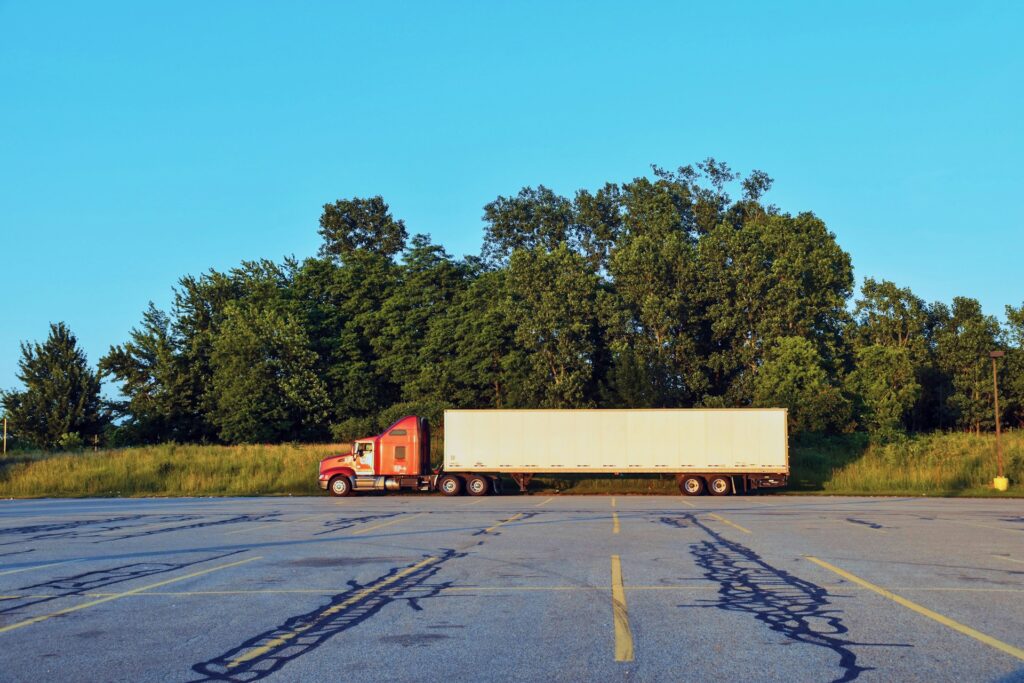
Red semi-truck with a white cargo trailer parked in an empty lot at golden hour, representing the older commercial trucks owner-operators often finance

How Tariffs and EPA 2027 Are Reshaping the Older-Truck Market

Tariffs and the upcoming EPA 2027 emissions rule are pushing more buyers toward used trucks in 2026. Both trends are tightening supply and pushing prices up.

New Class 8 prices have climbed roughly $10,000 due to tariffs on components, on top of years of steady increases.

At the same time, fleets are pulling purchases forward ahead of EPA 2027. The rule is expected to add several thousand dollars more to new truck prices once it takes effect.

That pre-buy activity is pulling late-model used trucks off the market. It’s also nudging used pricing upward.

For owner-operators shopping for an older rig, acting sooner may get you a better deal. It’s part of why working with a fast-moving lender matters more than ever.

How Much Does It Cost to Finance an Older Commercial Truck?

The cost of financing an older semi-truck depends on multiple factors: credit profile, down payment, vehicle age, mileage, and term. As of 2026, interest rates typically fall into three broad bands.

Credit Profile Typical APR Est. Payment on $70,000 (60-mo term)
Strong credit, established business 6% to 12% $1,350 to $1,555
Average credit, newer operators 12% to 20% $1,555 to $1,855
Credit challenges, startups 20% to 30%+ $1,855 to $2,265+

Estimated payments assume a $70,000 loan over a 60-month term and are for illustration only. Your actual rate and payment depend on the lender, down payment, and truck condition.

Loan terms also matter. Shorter terms mean higher monthly payments but less interest paid over time. Stretching a loan to 60 months lowers the payment but raises the total interest cost.

Truck age and condition factor in as well. A 5- to 7-year-old truck in solid shape usually qualifies for better terms. A 12-year-old, high-mileage unit typically won’t.

These costs are lower upfront than new truck financing. But because interest rates run higher on older equipment, your total financing cost over time may end up greater. That’s why it pays to work with a lender that balances flexible approvals with fair terms.

man in suit

Requirements for Older Semi-Truck Financing

Financing an older commercial truck comes with a few more hurdles than buying new equipment. Lenders weigh several factors before approving a loan for a high-mileage rig.

Requirement What Lenders Typically Want
Credit Score 650+ at traditional banks; as low as ~460 with Mission Financial Services
Down Payment 10% to 30% of purchase price; a larger down payment improves approval odds
Truck Age and Mileage Many lenders cap at 7 to 10 years or 700,000 miles; we finance used trucks up to 15 years old
CDL Experience At least 3 years of verified driving experience; less experience may still qualify with a larger down payment
Business Documentation Proof of income, recent bank statements, or tax returns
Insurance Proof of commercial truck insurance with at least a $1,000 deductible
Title and Registration Clean title and updated registration; salvage titles are much harder to finance

Keep in mind older trucks rarely carry a manufacturer’s warranty. Factor potential repair costs into your budget before you sign.

It’s also worth asking about prepayment penalties, since paying off a loan early can sometimes cost extra.

Meeting these requirements shows lenders you’re a serious operator. Even if you fall short on credit history, a specialized lender gives you a better shot at approval.

How To Secure Your Older Truck Loan in 5 Steps

Financing an older commercial truck doesn’t have to be complicated. With the right approach and the right lender, you can move from application to funding quickly.

Here’s a five-step process that works for most truckers.

White bus on road near mountain

Step 1: Decide Between a Lease or a Loan

Your first choice is whether to lease or finance outright. A commercial truck lease gives you use of the truck for a set period with lower monthly payments. At the end of the term, you can return it, extend the lease, or buy the vehicle.

Truck leasing companies typically ask for less money down than a purchase loan. A loan lets you buy the truck and build equity as you pay it down. Upfront costs and monthly payments may be higher, but you own the truck once the loan is complete.

Mission Financial Services structures every deal as a purchase contract, not a lease. If a true lease fits your situation better, you’d work with a leasing company or dealer instead.

Step 2: Understand Your Credit History and Score

Credit history plays a major role in approval and interest rates. A higher score gets you lower rates and better terms, but imperfect credit still leaves you options. Other factors, like time in business and down payment size, affect your rate too.

Mission Financial Services works with drivers who have scores as low as 460. We’re a common-sense lender, so we weigh your overall credit history, not just the number on your report. That makes financing possible for first-time buyers and drivers with bad credit.

Step 3: Get Pre-Approved

Fill out a short semi-truck loan application to see exactly how much you can finance before you start shopping. That makes negotiating with dealers easier and keeps you from wasting time on trucks outside your budget.

Mission Financial Services offers a fast online credit application. Our team reviews every submission and guarantees a response within four hours.

big truck

Step 4: Choose the Right Older Truck

Once you know your budget, look for the best used truck for your business needs. Reliable older trucks from brands like Kenworth, Peterbilt, Freightliner, Mack, and Volvo hold up well.

Proven engines from Cummins, Detroit, and Paccar can run past 500,000 miles with the right care. Check the truck’s age and mileage against your budget.

Ask the seller for accident records and maintenance logs before you commit. Confirm the truck matches your hauling needs, whether that’s long-haul freight, regional delivery, or specialty cargo.

Step 5: Submit Documentation and Get Funded

After selecting your truck, provide your lender with the make, model, mileage, and purchase price. You’ll also need proof of insurance, title documents, and income verification. Most lenders will ask for your Social Security number too.

Once approved, funding is released to your account and you can get on the road.

Alternatives If You Can’t Finance an Older Semi-Truck

If financing an older truck isn’t an option right now, truck leasing and other options can still get you moving.

  • Lease-to-Own Programs: Some dealers and lenders offer funding programs that let you lease an older truck, then buy it later. This spreads out costs while you build equity.
  • Refinancing an Existing Loan: If you already own a financed truck, refinancing could free up cash or lower your payment. That can make it easier to fund a second truck.
  • Title Loans: If you own a truck outright, a commercial vehicle title loan uses your existing equipment as collateral. It’s a fast way to access cash.
  • Zero-Down Options: Some lenders offer zero-down financing for qualified buyers. This can help if you don’t have cash for a down payment right now.
  • Cash Purchase with a Smaller Loan: For lower-cost trucks, combine savings with a smaller loan. This reduces your monthly burden and makes approval easier.

cars on road

3 Tips to Improve Your Chances of Approval

Getting approved for older-truck financing often comes down to preparation. These three steps can set you up for success before you apply.

Strengthen Your Credit Profile

Even small improvements make a difference. Pay down existing debt where possible, dispute errors on your credit report, and avoid missed payments before applying.

Lenders see consistent payment history as a sign you’ll handle loan installments reliably.

Save for a Larger Down Payment

A bigger down payment lowers the amount you need to borrow. It also shows lenders you’re invested in the truck.

For older rigs, aim to save 20% to 30% of the purchase price. It can also offset the higher interest rates that sometimes come with used truck loans. Comparing a few offers side by side helps you find competitive rates.

Work With a Lender That Understands Older Equipment

Traditional banks often reject applications for older trucks over age or mileage caps. We regularly approve drivers that mainstream institutions turn away.

That includes drivers recovering from bankruptcy or navigating lender protection issues. If you’re financing multiple trucks for a growing fleet, ask about volume-based terms too. If your freight volume swings seasonally, ask whether payment structures can flex with your seasonal cash flow.

Conclusion

Financing older commercial trucks is one of the smartest ways for independent drivers and small fleets to control costs. You still get access to reliable equipment.

From lower purchase prices and simpler repairs to easier approval, older trucks can be the right call when managed carefully.

Traditional lenders often turn away high-mileage rigs. Mission Financial Services makes financing possible for customers with bad credit or small budgets. We’re a direct lender in 48 states and a preferred dealership partner in 28 more. Our regional offices span the country.

Ready to finance your next truck? Start your credit application with Mission Financial Services today. Get on the road with flexible terms built for truckers like you.
Frequently Asked Questions

Who finances older semi-trucks?

Specialized equipment lenders, credit unions, and lenders like Mission Financial Services typically finance older semi-trucks. Traditional banks often cap financing at 7 to 10 years old. Mission Financial Services finances trucks up to 15 years old.

What credit score is needed to finance a semi-truck?

Traditional banks generally want a credit score of 650 or higher. Specialized lenders like Mission Financial Services consider applicants with scores as low as 460. A stronger score still gets you access to the best rates.

How much is a $70,000 truck payment?

A $70,000 truck loan typically runs $1,350 to $2,265 a month over a 60-month term, depending on your rate. Well-qualified buyers land at the low end. Borrowers with credit challenges pay more.

How many years can you finance a semi-truck?

Most semi-truck loans run 24 to 60 months. Some lenders extend qualified buyers to 72 or even 84 months. Older-truck loans usually stay closer to 60 months, since resale value drops faster on higher-mileage equipment.

Archives

Sign Me Up!

Stay up to date with the latest news in the commercial trucking industry.

Contact Us
close slider