Office: (404) 975-4800

Business

Section 179 and Semi-Truck Purchases: What Owners Should Know

Section 179 and Semi-Truck Purchases: What Owners Should Know

Row of Class 8 semi trucks in white, blue, black and orange parked side by side in a lot under a clear sky

Section 179 lets you deduct a qualifying semi-truck’s full purchase price in the same tax year it starts working. For 2026, the limit is $2,560,000, so a Class 8 truck fits well inside it.

This guide covers what qualifies, how the year-end deadline works, how financing fits in, and the mistakes to avoid.

TL;DR

  • The 2026 Section 179 limit is $2,560,000, and it starts phasing out once purchases pass $4,090,000.
  • A semi-truck qualifies if it’s used over 50% for business and placed in service by December 31.
  • Financed trucks qualify, so you can deduct the full cost while paying for the truck over time.
  • Bonus depreciation is now permanent at 100% for property acquired after January 19, 2025.

Note: Tax rules depend on your situation. Get advice from a qualified tax professional before you buy a truck for tax reasons.

What Is Section 179?

Section 179 is part of the Internal Revenue Code. It lets a business deduct qualifying equipment in the year it’s placed in service. Without it, you’d recover capital expenditures like a truck through depreciation over several years. Section 179 moves that whole deduction into year one, which means immediate tax savings.

For tax years beginning in 2026, the IRS set these limits in Revenue Procedure 2025-32:

  • Maximum deduction: $2,560,000
  • Phase-out threshold: The limit drops dollar for dollar once total qualifying purchases pass $4,090,000.
  • SUV cap: $32,000 for sport utility vehicles, which doesn’t apply to semi-trucks.

Most owner-operators and small business owners never get close to the phase-out. One or two trucks a year fit easily inside the limit.

Does a Semi-Truck Qualify for Section 179?

Yes, a semi-truck qualifies for Section 179 when it meets three tests.

  • Business use percentage must be over 50%: You use the truck more than half the time for your trucking business.
  • Placed in service this tax year: The truck must be working in your business before the tax year ends.
  • Acquired from an unrelated seller: Buying from a close family member or a business you control doesn’t count.

These rules come from IRS Publication 946, which explains how to depreciate business property.
Line of red, white, blue and yellow semi truck cabs parked outside a truck parts building, showing heavy commercial vehicles that can count toward a year-end Section 179 semi truck purchase

Used Trucks and Trailers

Used trucks qualify too, as long as the truck is new to your business. Trailers and other trucking equipment can also qualify.

A well-kept used commercial truck can give you the same first-year deduction as a new one, on a smaller loan.

Why Gross Vehicle Weight Rating Matters

Gross vehicle weight rating (GVWR) is the maximum loaded weight a manufacturer rates a vehicle for. It decides which vehicle limits apply.

  • 6,000 pounds or less: Passenger vehicles here face the tightest yearly depreciation caps.
  • 6,001 to 14,000 pounds: SUVs in this range get a higher deduction, capped at $32,000.
  • Over 14,000 pounds: Heavy commercial vehicles skip the SUV cap, so you can deduct the entire purchase price.

Some commercial vans also escape the SUV cap, such as cargo vans with no seating behind the driver.

A Class 8 semi-truck has a GVWR above 33,000 pounds, so neither cap applies.

For a semi-truck, the only dollar limit is the overall Section 179 maximum.

How Much Can You Deduct in 2026?

You can deduct a qualifying truck’s full price, up to $2,560,000, but not more than your business’s taxable income. This is called the business income limit. If your deduction is bigger than your taxable income from the business, the extra carries forward to future years.

Here’s a simple example:

Say you buy a $120,000 used truck and your business earns enough to absorb the full deduction. If all that income is taxed at 24% federally, the deduction could cut your tax bill by up to $28,800.

Your real savings depend on your income, state taxes, and business structure. A tax advisor can run your numbers before you buy. You can claim it alongside other truck driver tax deductions like fuel, maintenance, and insurance.

Section 179 vs. Bonus Depreciation vs. MACRS

Bonus depreciation and standard MACRS depreciation also recover a truck’s cost. They differ from Section 179 in timing and limits.

Method How it works Limits
Section 179 Deduct the full cost in year one $2,560,000 cap and the business income limit
Bonus depreciation Deduct 100% of the cost in year one No dollar cap or business income limit
MACRS Spread the cost over several years Set recovery periods for different assets

How Bonus Depreciation Works

Bonus depreciation is a first-year depreciation deduction for a set percentage of an asset’s cost. It’s now permanent at 100% for qualified property acquired after January 19, 2025 (IRS).

The One, Big, Beautiful Bill Act made that change. Before it, bonus depreciation was shrinking each year.

Unlike Section 179, bonus depreciation isn’t capped by your business income. It can create a loss you carry forward.

When Spreading Out Deductions Makes Sense

A big first-year deduction isn’t always the best move. If this year’s income is low, a large deduction may save you very little.

Standard MACRS depreciation (the IRS’s default system) spreads the deduction across future years. That can be worth more if you expect higher income later.

You claim Section 179 on IRS Form 4562. Your tax professional can help you choose a method when they file it.
White box truck and dark semi truck parked at a truck stop at sunset, with a car carrier loaded with vehicles on the right

Year-End Timing: Placed in Service by December 31

To claim Section 179 for 2026, the truck must be placed in service by December 31, 2026. That assumes a calendar tax year.

Placed in service means the truck is ready and available for its intended use. Signing a purchase order isn’t enough. A truck still at the dealer, waiting on repairs, or missing insurance on December 31 likely won’t qualify for 2026.

In our experience, December deals take longer than buyers expect. Titles, inspections, insurance, and holiday closures all slow things down. We’d start the financing process by early December at the latest. Getting pre-approved first lets you move as soon as you find the right truck.

Some fleets are also buying trucks ahead of EPA 2027 emission rules, which could tighten inventory at year-end.

Financing and Section 179

Yes, a financed truck qualifies for a Section 179 deduction. You can deduct the full cost this year, even though you pay for the truck over time.

IRS Publication 946 counts debt obligations as part of an asset’s cost. So your deduction is based on the purchase price, not only your down payment. The deduction is the same whether you pay cash or finance the truck.

That can help your cash flow. The tax savings arrive with this year’s return, while the payments spread across your loan term.

Our loans are purchase contracts, so you own the truck from day one. A true lease works differently. Capital leases (often $1 buyout leases) usually count as purchases, so the lessee claims Section 179. With operating leases, the leasing company usually takes the depreciation. Weighing leasing a semi-truck vs. buying one is worth doing before year-end for that reason.

If you’re buying more than one truck, small fleet loans can finance several vehicles at once.

Common Section 179 Mistakes to Avoid

Most Section 179 problems come from timing, business use, or buying for the wrong reasons. Watch for these:

  • Buying only for the deduction: A deduction saves you part of the cost, not all of it. Buy a truck because your business needs it.
  • Letting business use drop: If business use falls to 50% or less, you may owe back part of the deduction.
  • Skipping the paperwork: Keep mileage logs and business records to back up your claim in case of an audit.
  • Selling the truck early: Selling a fully deducted truck can trigger depreciation recapture, which is taxed as ordinary income.
  • Assuming your state matches: Section 179 is a federal deduction. Some states don’t follow it or federal bonus depreciation rules.
  • Missing the deadline: A truck delivered on January 2 counts toward next year, not this one.
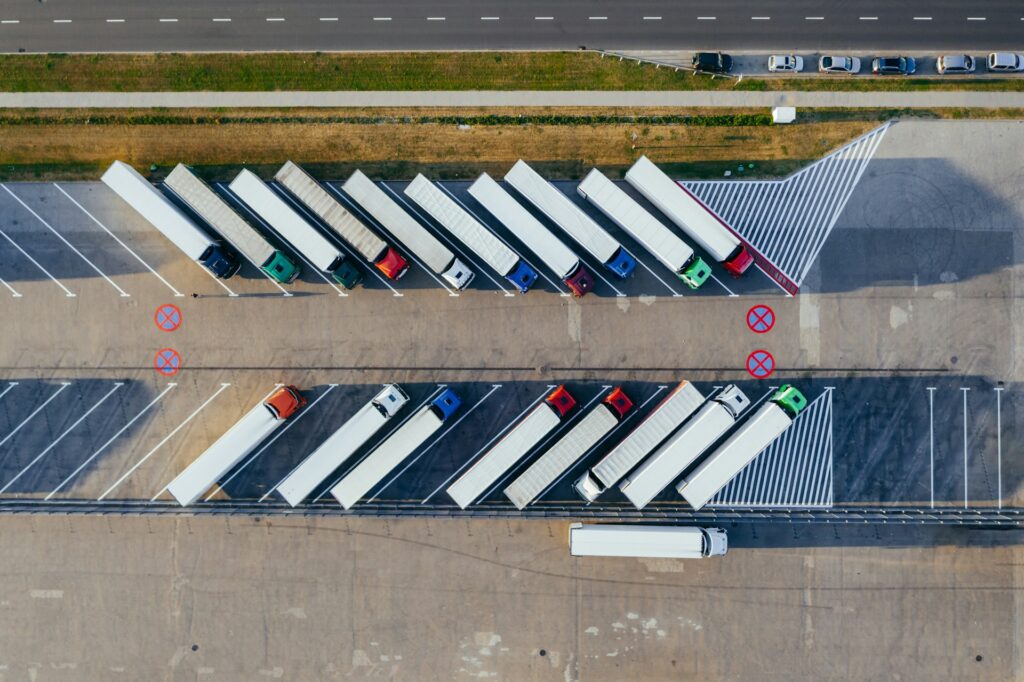
Aerial view of semi trucks with white trailers parked in angled rows at a freight lot, the kind of equipment that can qualify for a Section 179 deduction

Why You Should Talk to a Tax Professional

A tax professional can tell you whether Section 179, bonus depreciation, or MACRS gives you the biggest benefit. They’ll check your business income limit, state rules, and how your business structure affects the deduction.

Bring your purchase agreement, loan contract, and delivery date. Those documents prove the cost and the placed-in-service date.

Final Thoughts

A year-end Section 179 semi-truck purchase can become a large first-year deduction. To qualify, the truck must be in service by December 31 and used mostly for business.

Talk to your tax professional first, then line up financing early so the truck is working before the year ends.

If you’re buying before December 31, start your credit application, and we’ll get back to you within four hours.

Frequently Asked Questions

Does a Used Semi-Truck Qualify for Section 179?

Yes, a used semi-truck qualifies if it’s new to your business and used more than 50% for business.

Can I Take Section 179 on a Financed Truck?

Yes, you can take Section 179 on a financed truck. The Section 179 deduction is based on the truck’s full cost, including the amount you borrow.

What’s the Deadline for Section 179 in 2026?

The truck must be placed in service by December 31, 2026, for calendar-year businesses. Buying it isn’t enough. It must be ready to work.

How Much Can I Deduct Under Section 179 in 2026?

You can deduct up to $2,560,000 in 2026, limited to your business’s taxable income. The limit starts phasing out above $4,090,000 in purchases.
10 Fleet Management Best Practices That Keep Your Trucking Business Profitable

10 Fleet Management Best Practices That Keep Your Trucking Business Profitable

Smiling man in a beanie and black jacket leans against a wall near a lot of parked semi trucks

The best fleet management practices come down to controlling costs, preventing breakdowns, and keeping drivers safe and compliant.

For a small fleet, that means tracking cost per mile, following a preventive maintenance schedule, and using telematics. It also means managing fuel, training drivers, and planning when to replace trucks.

Margins are thin right now, so a few cents saved per mile adds up by year-end. We work with owner-operators and small fleets every day, and the ones that last treat these practices as routine.

Below, we cover 10 best practices, the KPIs to track, and answers to common fleet manager questions.

What Is Fleet Management?

Fleet management (sometimes called fleet vehicle management) is how you run your trucks, drivers, and costs. Done well, it makes sure every truck earns more than it costs to run.

Its core elements are maintenance, fuel, safety, compliance, and financing. For a fleet of 1–10 trucks, the owner often handles most fleet operations personally.

When the owner also runs dispatch, small fleet management depends on simple systems more than fancy tools.

10 Fleet Management Best Practices

A solid fleet management strategy builds from the foundation (knowing your numbers) up to long-term planning. Start with the first three if you’re just getting organized.

1. Know Your Cost Per Mile

Your cost per mile tells you whether each load makes or loses money.

ATRI puts the 2025 industry-average operating cost at $2.336 per mile, a record high. Without fuel, costs were $1.854 per mile.

Your numbers will differ, so calculate cost per mile for commercial trucking with your own figures.

Update it every month. A rate that paid well in spring might not cover your costs by fall.

2. Follow a Preventive Maintenance Schedule

Preventive maintenance (some shops call it preventative maintenance) means servicing trucks on a set schedule, before parts fail. It’s cheaper than paying for unscheduled breakdowns and missed loads.

Repair and maintenance costs rose 8.6% in 2025, one of the biggest increases of any cost line.

Build your schedule around mileage and engine hours. Use a commercial truck maintenance checklist that covers oil, filters, brakes, tires, and the aftertreatment system.

Fleet maintenance software can send service reminders by mileage, so no truck runs past its due date.

Keep a small parts inventory for the items you replace most. Filters, belts, and bulbs sitting on a shelf beat a two-day wait for delivery.

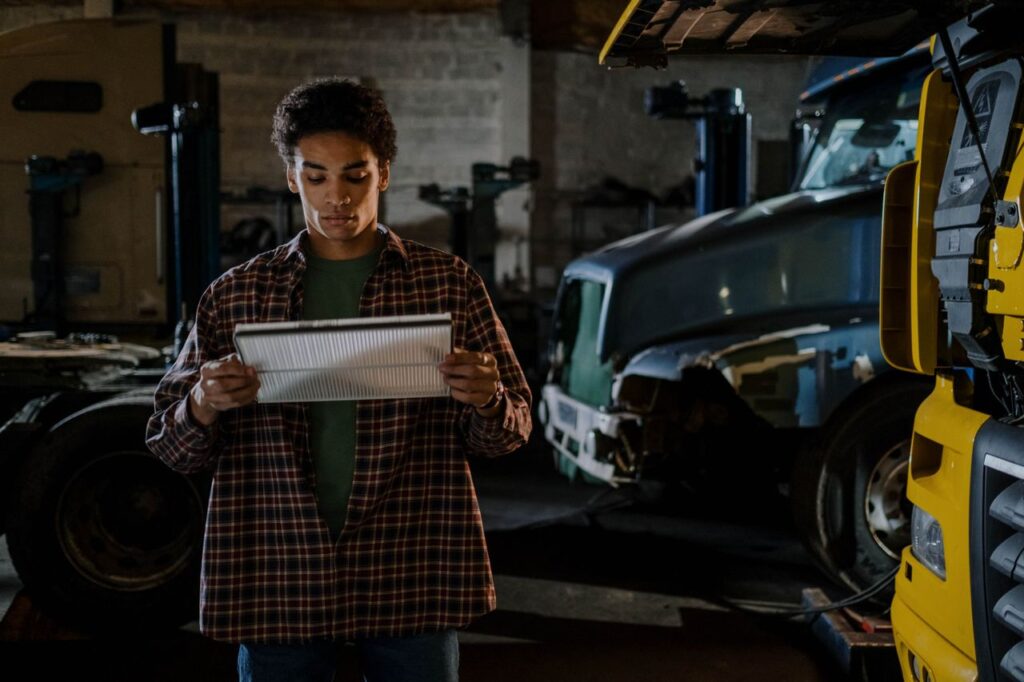
Technician in a plaid shirt inspects a truck air filter in a repair shop during preventive maintenance

3. Make Inspections a Daily Habit

Daily inspections catch potential problems before they turn into roadside violations or breakdowns.

Federal rules require carriers to systematically inspect, repair, and maintain their trucks. Drivers must file driver vehicle inspection reports when they find a defect. Repairs cost less when you address issues as soon as a driver reports them.

Every truck also needs an annual inspection. You’ll need to keep those records for 14 months.

Give drivers a pre-trip inspection checklist so nothing gets skipped on a busy morning.

4. Use Telematics and Fleet Management Software

Telematics devices increase visibility across your whole fleet. They track location, speed, idling, fuel use, and engine fault codes in real time.

Fleet management software turns that data into reports that help you make informed decisions about routes, repairs, and drivers.

You likely already have part of a fleet management system. Most trucks need an electronic logging device (ELD) that records driving time from the engine.

When comparing trucking software for small fleets, check whether the ELD includes GPS tracking, maintenance alerts, and driver scorecards. Most of these digital tools also come with mobile apps, so you can check a fault code from your phone.

5. Manage Fuel Consumption

Fuel is one of your highest costs, so fuel-efficient driving and maintenance pay off fast.

Idling burns fuel without moving freight. Long-haul trucks burn more than a billion gallons of fuel a year idling during rest stops.

Focus your fuel management on these areas:

  • Set idle limits and track them with telematics.
  • Use a fuel card to control spending and flag odd purchases.
  • Keep tires at the right pressure.
  • Plan routes to cut empty miles and avoid traffic.

Route optimization software automates much of efficient route planning. Lower cruising speeds and driver coaching are also cost-effective fuel-efficiency strategies that don’t need new equipment.

6. Build a Driver Safety Program

A driver safety program sets clear rules, trains drivers, and tracks driver performance over time. When you improve safety, you get fewer accidents, lower insurance costs, and less wear on your trucks.

Start with these basics:

  • Written policies on speeding, phone use, and following distance
  • Driver training when someone joins and refreshers every year
  • Scorecards that track hard braking, speeding, and idling
  • Rewards for drivers with clean records

Keep the scorecards fair and share them so drivers can monitor progress. Nobody likes being graded in secret.

Pair the scorecards with practical safety tips for commercial truck drivers, like adding following distance in rain and snow.

Semi truck with a curtain-side trailer driving on an empty divided highway under a cloudy sky

7. Stay on Top of Compliance

Compliance keeps your trucks on the road and your authority in good standing. Violations can mean fines, out-of-service orders, and higher insurance premiums.

Hours-of-service rules let property-carrying drivers drive 11 hours after 10 consecutive hours off duty (FMCSA).

Keep driver files, inspection reports, and maintenance records organized and easy to pull. Organized records also make it easier to prepare for roadside inspections.

8. Track the Right KPIs

Key performance indicators (KPIs) show whether your fleet performance is improving or slipping. Pick four or five key metrics and review them monthly.

KPI What it tells you
Cost per mile Whether your rates cover your costs
Revenue per mile How well your loads pay
Fuel economy (MPG) How efficiently each truck and driver uses fuel
Idle time How much fuel you’re burning while parked
Maintenance cost per mile Which trucks are getting expensive to keep
Downtime How many days each truck sits out of service
Empty miles How often trucks run without a paying load
Safety events Hard braking, speeding, and accidents per driver

Operations leaders at large carriers can track dozens of KPIs. In our experience, small fleets get the most from three: cost per mile, maintenance cost per mile, and downtime.

Reviewing those three each month helps you identify areas where one truck costs more than the rest.

9. Protect Your Fleet Data

Your telematics, ELD, and dispatch systems hold sensitive data, so protect those logins as carefully as your bank account.

  • Turn on two-factor authentication/login for every fleet platform.
  • Give each driver and dispatcher their own login.
  • Remove access the day someone leaves.
  • Be wary of emails asking you to “verify” load or payment details.

Good data security also protects you from freight fraud and double brokering scams.

10. Plan Vehicle Replacement and Financing Early

Replacing a truck before repair costs spiral protects your cash flow. Waiting until it dies usually means buying in a hurry.

Carriers ran trucks an average of 633,772 miles before replacing them in 2025. That was up nearly 50,000 miles, as weak rates pushed carriers to keep trucks longer.

Track each truck’s maintenance cost per mile. A steady climb is usually the first sign it’s time to replace the vehicle.

Line up financing before you need it. Our small fleet loans help owner-operators add or replace trucks without draining their reserves.

Person counting cash over financial reports, a phone calculator, and a laptop while budgeting for a truck purchase

Final Thoughts

The key takeaways from this guide are to know your numbers, maintain your trucks, and keep drivers safe and compliant.

Start with cost per mile, preventive maintenance, and daily inspections. Then add telematics and KPIs as your fleet grows.

When it’s time to add or replace a truck, contact Mission Financial to talk through your fleet financing options.

Frequently Asked Questions

What Are the 5 Pillars of Fleet Management?

There’s no official list. A common way to split effective fleet management is into five areas: cost control, maintenance, safety, compliance, and technology.

What Are the Best Practices for Fleet Maintenance?

Service trucks on a set schedule, require daily inspections, and fix defects before the truck goes back out. Keep records for every repair, and track maintenance costs for each truck.

What Are the KPIs for Fleet Management?

The most useful KPIs are cost per mile, revenue per mile, fuel economy, idle time, and downtime. Maintenance cost per mile and safety events matter too.

How Can a Small Fleet Reduce Costs?

Cut idling, stay on top of preventive maintenance, and plan routes to reduce empty miles. Shopping your insurance every year is another simple way to reduce fleet costs.

How to Reduce Fleet Costs and Improve Your Bottom Line

How to Reduce Fleet Costs and Improve Your Bottom Line

Close-up of hands stacking coins into growing piles, representing steady financial gains from reducing fleet costs

Running a truck costs more in 2026 than at any point on record. If you’re managing 1 to 10 trucks, every extra cent per mile eats directly into your margin.

This guide breaks down where fleet costs come from and how to calculate your real numbers. And it covers the strategies that actually move them, from fuel and maintenance to financing and insurance.

TL;DR

  • The average cost to run a truck hit $2.336 per mile in 2025, the highest on record, according to ATRI.
  • Diesel prices have jumped over $1.70 a gallon in the past year, so fuel savings matter more than ever.
  • Tracking cost per mile by truck, not by fleet, is the fastest way to spot which vehicles are losing you money.
  • Idling, driver behavior, and preventive maintenance are the quickest wins. Financing and insurance decisions drive the bigger, longer-term savings.

What Is Driving Up Fleet Costs Right Now?

Fleet management costs are rising because almost every major expense category went up in 2025. Fixed costs like insurance stay fairly steady. Variable costs and indirect costs, fuel, tolls, and repairs, are climbing fastest for fleet managers and owner-operators alike.

ATRI’s 2026 report found average operating costs to run a truck reached $2.336 per mile in 2025. That’s up 3.4% from $2.260 the year before, the highest per-mile cost on record.

Repair and maintenance costs rose 8.6% to $0.404 per mile. Aging trucks are especially prone to these higher maintenance costs as parts wear out.

Tolls jumped 13.2%, driver benefits climbed 6.6%, and tire costs rose 6.4%. Truck and trailer lease payments also increased, up 3.6% to roughly $0.40 per mile.

Small fleets spent less on vehicle acquisition in 2025 than in 2024. That’s a sign many are holding off on new fleet vehicles while operational costs settle.

Diesel prices also spiked hard in 2026. The EIA’s weekly survey put the national average retail diesel price at $5.454 per gallon in mid-August. That’s up more than $1.70 from a year earlier. That swing alone can wipe out a season’s margin for a small fleet.

White semi truck with a trailer driving on a two-lane highway past forested mountains

How Much Does It Cost to Run Your Truck?

The two numbers that matter most are total cost of ownership (TCO) and cost per mile (CPM).

TCO adds up everything you spend on a truck over its vehicle life. That’s purchase or financing costs, fuel, maintenance, insurance, tolls, administrative costs, and driver pay, minus resale value.

For example, say you finance a truck for $150,000 and spend $400,000 more on fuel, repairs, and insurance over five years. Your TCO is $550,000 minus whatever you sell it for at the end.

CPM divides that total by the miles the truck drove over the same period.

A truck with a $550,000 TCO that ran 500,000 miles over five years costs $1.10 per mile to run. That single number tells you whether a load, a lane, or a rate is actually worth taking.

Here’s what CPM and TCO help you do:

  • Spot the one truck losing money on repairs before it drains your cash.
  • Decide whether a load or lane covers your real cost to run, not just your fuel and driver pay.
  • Know when a truck has crossed from a cost-efficient asset into a money pit, so you can plan a repair, sale, or replacement instead of reacting to a breakdown.
  • Compare financing, insurance, or leasing offers against your actual numbers instead of guessing.

Running the math per truck, every month, is the only way to catch a problem while it’s still cheap.

5 Best Strategies to Reduce Costs for Small Fleets

The strategies that move the needle fall into five areas: fuel, maintenance, technology, financing, and insurance. Some pay off within weeks. Others take longer but deliver bigger, more lasting savings.

Here’s how to tackle each one to help reduce fleet expenses.

Coins in a glass jar with a small plant sprouting from them, symbolizing how small changes can grow into real savings on fleet costs

1. Cut Fuel Costs

Fuel is one of the highest costs in your budget, and it’s tied directly to fuel consumption for every truck.

Start by cutting excessive idling. The U.S. Department of Energy estimates that idling wastes more than 6 billion gallons of fuel every year across U.S. vehicles. That costs over $11 billion at a $2-per-gallon baseline.

Cutting idling during rest periods is one of the simplest ways to reduce fuel consumption.

Next, address driving habits. Aggressive driving, speeding, hard braking, and rapid acceleration can lower fuel economy by 15% to 30% at highway speeds. In stop-and-go traffic, the loss climbs to 10% to 40%.

Learning to anticipate traffic flow and brake gradually protects your fuel budget. If you’re due for a replacement, moving toward more fuel-efficient vehicles compounds these savings over time.

A few other ways to reduce fleet costs pay off quickly, without new equipment:

  • Keep tires properly inflated and aligned. Proper tire care is one of the cheapest ways to improve fuel efficiency.
  • Use fuel cards to track spending by driver and station. This helps you optimize fuel consumption and catch unusual purchases early.
  • Plan routes more efficiently to cut empty miles and avoid unnecessary detours.

Together, these habits add up to real fleet efficiency gains for smaller operations. We break down more tactics in our guide to fuel-efficiency strategies for semi-trucks.

2. Lower Maintenance and Repair Costs

You can lower repair costs by catching small problems before they become expensive ones. Reactive repairs, the kind that follow a breakdown, almost always cost more than a scheduled fix.

A single costly breakdown can spiral into thousands of dollars in emergency repair costs. On top of that, you lose days waiting on a shop appointment.

A proactive fleet maintenance program of oil changes, tire rotations, and inspections keeps small issues from becoming major failures.

Many small fleets are updating their maintenance procedures to include predictive maintenance. That means using engine hours and sensor data to schedule maintenance before a part fails. Predictive maintenance also helps you avoid unnecessary service, since parts get replaced based on real wear.

A clean maintenance history for each truck also helps you spot patterns and avoid repeat maintenance expenses.

Train yourself or your drivers to catch early warning signs, too. A failing carrier bearing, for example, often gives off clear signals before it fails. Catching it early is far cheaper than a roadside breakdown and helps protect the truck’s vehicle lifespan.

Set up a repeatable pre-trip and maintenance routine so vehicle repairs don’t pile up unnoticed.

Two technicians review a fleet maintenance checklist together in front of a blue semi truck in a service bay.

3. Use Telematics and GPS Tracking

Telematics data, GPS tracking, and fleet management software give you the cost visibility to see where money is being wasted.

These systems combine fleet tracking, vehicle location, and driver behavior data in real time. That lets you monitor driver behavior without guessing from fuel receipts and mileage logs.

Telematics helps in several ways:

  • It can trigger maintenance alerts based on vehicle condition, flagging problems before they become a shop visit.
  • It can lower fuel costs. Fleets using GPS tracking reported an average 12% decrease in fuel costs. Much of that comes from catching idling and aggressive driving early.
  • It supports route planning and optimizing routes, cutting empty miles and out-of-route stops that quietly drain your fuel budget.

Together, these capabilities raise operational efficiency without adding headcount.

For small fleets, the value is in catching patterns early. That might be a truck with poor vehicle utilization or weak asset utilization. It could also be a route that runs long or a driver who brakes hard.

Left unaddressed, each adds up over a year.

4. Review Financing and Leasing Decisions

Every truck eventually reaches a point where repair and maintenance costs outpace what it can still earn. Holding onto an aging truck past that point usually costs more than replacing it, even with a new loan payment. When you do replace it, how you pay for the truck matters as much as when you buy it.

Start by reviewing current commercial truck financing rates before you commit to a loan. Rates shift, and locking in an old quote can cost you thousands over the life of the loan.

Leasing a semi-truck instead of buying is worth considering too. It’s especially useful if cash is tight or you won’t keep the truck long. As a rule of thumb, financing suits fleets running the truck for years with cash to weather a slow month. Leasing suits fleets that want to preserve cash flow now or avoid the resale risk of owning it.

Truck driver sitting in the cab of a semi truck reviewing paperwork on a clipboard before a trip

5. Lower Insurance Costs

You lower fleet insurance costs mainly by reducing risk and proving it. Insurers increasingly look at real driving data instead of just claims history. Fleets that adopt safer habits often qualify for lower insurance premiums over time.

Dash cams are one direct way to support this. They provide evidence in the event of an incident, which can protect you from liability. Over time, that evidence supports a case for lower premiums. Our guide to the best dash cams for semi trucks covers what to look for.

Beyond equipment, consistent driver training and a clean maintenance record both shape how insurers assess your risk.

Shopping your policy every year or two, rather than renewing automatically, helps you avoid paying more than the market rate.

Where Should You Start Cutting Fleet Costs Today?

Start with your numbers. Calculate cost per mile for each truck, not just your fleet as a whole. That’s the fastest way to reduce costs you can’t otherwise see. From there, tackle idling, driver behavior, and fuel card monitoring first. Those usually show results within weeks.

Preventive maintenance and telematics take longer to pay off, but they save money more consistently over time. Financing and insurance decisions matter most over the life of the truck. Review them at least once a year instead of letting old terms roll forward.

At Mission Financial Services, we’ve worked with owner-operators and small fleets across the country. The businesses managing costs best treat financing as part of their overall fleet management strategy, not an afterthought. Whether you need a repair loan, operating capital, or financing for your next truck, we’re here to help.

When to Replace Fleet Vehicles: Signs It’s Time to Upgrade

When to Replace Fleet Vehicles: Signs It’s Time to Upgrade

Three white box trucks parked side by side at loading dock bays, front view in evening light

Most fleets aim for a vehicle replacement policy of 3-5 years or 400,000-500,000 miles (for Class 8 vehicles).

You should replace a fleet vehicle when it costs more to keep than to swap out, usually because of one or more of these signs:

  • a single repair over 50% of the truck’s value
  • annual maintenance above 150% of your fleet’s average
  • downtime that keeps climbing
  • resale value that’s dropping fast

Fleet managers running several trucks face this decision on repeat, often for more than one vehicle at a time. Getting that timing right can save you thousands over the life of your fleet operations.

Here’s how to spot the signs and calculate the right moment to replace.

TL;DR

  • A single repair that costs more than half a truck’s value, or annual maintenance that runs above 150% of your fleet’s average, is a strong signal to replace instead of repair.
  • Cost per mile is the clearest number to track. It rolls fuel, repairs, downtime, and financing into one figure you can compare truck to truck.
  • Resale value drops fastest in the first few years, so selling before a major breakdown almost always protects more of your investment.
  • Section 179 and bonus depreciation can make replacing a truck this year cheaper than it looks on paper.
  • MFS works with owner-operators and small fleets to structure financing around the right replacement timeline, not just the sale price.

What Is a Fleet Vehicle Replacement Strategy?

A fleet vehicle replacement strategy is a plan for deciding when a truck moves from “keep repairing” to “time to replace.”

Instead of guessing based on gut feeling, you track a handful of numbers: repair costs, downtime, mileage, and resale value.

An effective fleet replacement strategy also accounts for usage patterns, since a truck running long hauls wears differently than one used for regional runs.

For a one-truck operation, this can be as simple as a spreadsheet you update every quarter on a fleet replacement schedule. For a small fleet of five to ten trucks, it means ranking each vehicle against the others, based on where each one sits in its vehicle lifecycle, so you know which one to replace first.

Trucks at different points in their vehicle lifecycles often need very different plans.

A row of white delivery vans and box trucks parked in a lot lined with trees, illustrating a small fleet ready for replacement planning

5 Signs It’s Time to Replace a Fleet Vehicle

When several of these signs show up together, it’s usually time to plan a replacement instead of another repair.

1. Hefty Repair Costs

Compare a truck’s repair spending over the past 12 months with similar trucks in the same vehicle class, or with that truck’s own history.

As vehicles age, frequent repairs and rising maintenance costs creep up gradually. So it helps to watch repair frequency over time and track those costs.

Once total maintenance costs cross a threshold you’ve set in advance, it’s time to consider replacing that vehicle. If one repair costs more than half of what the truck is worth, replacement usually makes more financial sense than fixing it again.

Major repairs on aging vehicles usually have to do with engine, transmission, or drivetrain work, and ongoing repairs on a truck past its prime can cost more than a truck payment would.

2. Downtime Keeps Getting Worse

Track how many days each truck sits in the shop every quarter. A truck that goes from two days down to five, then nine, is telling you something even if the individual repair bills still look manageable.

Missed loads and rescheduled deliveries add downtime costs that never show up on a repair invoice.

3. Cost per Mile Is Increasing

Cost per mile pulls fuel, maintenance, insurance, depreciation, and downtime into one number, which makes it the clearest way to compare an aging truck against a newer one and see your true total cost of ownership.

According to the American Transportation Research Institute, industry-average operational costs to run a truck reached $2.336 per mile in 2025, up 3.4% from the year before, with repair and maintenance costs climbing 8.6% to 21.5 cents per mile on their own.

If your operating costs are rising faster than that, your truck is likely past its prime. Newer vehicles also tend to be more fuel-efficient, which brings down your overall operating expenses even before you count fewer repairs.

Rear view of a semi truck hauling a covered trailer on a two-lane highway through a desert mountain pass

4. The Truck Keeps Failing Inspections

A single failed inspection can be bad luck. Repeat inspection failures involving brakes, tires, steering, or lighting point to a bigger problem.

Under the North American Standard Out-of-Service Criteria, an inspector can pull a truck from service on the spot if a defect creates an immediate safety hazard, and a truck with repeat violations indicates that its condition is declining faster than routine maintenance can keep up with.

5. Resale Value Is Dropping Fast

Trucks lose value fastest in their first few years (20-25%). Then the depreciation curve flattens while maintenance costs start to rise.

Selling vehicles before a major component failure almost always preserves more resale value than waiting until an aging truck can barely make it under its own power.

Older fleet vehicles tend to carry more unexpected costs the longer you hold onto them.

Newer models also tend to come with updated driver safety features, and reliable equipment supports higher driver satisfaction.

How to Calculate Your Replacement Point

Cost per mile is calculated as your total operating and ownership costs divided by miles driven.

Fuel, maintenance, repairs, insurance, depreciation, and downtime are the key factors, and using the same categories for every truck keeps the comparison fair.

Run this calculation quarterly for each truck in your fleet.

When a truck’s cost per mile starts climbing instead of holding steady or dropping, you’ve found your optimal replacement point.

Comparing the projected cost of keeping a truck against the cost of replacing it gives you lifecycle cost projections you can plan around.

Simple Replacement Schedule for a Small Fleet

You don’t need enterprise fleet software to run a replacement schedule well. A strong fleet replacement strategy comes from reviewing the same data on a set schedule, not from reacting to breakdowns.

Review each truck’s cost per mile, downtime days, and repair spending every quarter.

Rank your trucks from most to least expensive to keep running.

Plan financing for your top candidate before it fails, not after.

Many fleet professionals treat this as a cycle of continuous improvement: review, rank, finance, replace, then start again, which keeps fleet optimization and replacement decisions grounded in your actual numbers instead of guesswork.

Small fleet management gets harder as you add trucks, since each vehicle needs its own repair history, downtime log, and replacement timeline rather than one blanket rule for the whole operation.

A lineup of semi trucks in different colors parked at a truck stop, representing the range of vehicles to evaluate when deciding to replace fleet vehicles

How Financing Rules Can Change Your Replacement Timeline

In our experience financing trucks for owner-operators across the country, we’ve found that tax rules can change the math on replacement timing.

For 2026, businesses can deduct up to $2,560,000 in qualifying equipment under Section 179, with the deduction phasing out once total equipment purchases for the year exceed $4,090,000.

Most semi-trucks and other heavy vehicles over 6,000 pounds GVWR aren’t subject to the lower Section 179 cap that applies to SUVs, so a qualifying truck can often be expensed in the year you buy it when combined with bonus depreciation.

That can make financing a replacement now more affordable, and the cost savings can be significant once you factor in fewer repairs.

Speak with your accountant before you count on this, since Section 179 is limited by your taxable business income and requires more than 50% business use.

Financing Options for Replacing an Older Truck

We’ve found that owner-operators replacing a truck usually fall into one of a few situations, and the right financing depends on which one fits. Some are moving up to new fleet vehicles, while others are simply trading one set of older vehicles for something more reliable.

If your credit and down payment are solid, zero-down semi truck financing can help you preserve cash during the transition instead of tying it up in a down payment.

If you’d rather ease into ownership with lower payments upfront, lease-to-own structures let you build toward buying the truck over time instead of financing the full price on day one.

Either way, lining up financing before a truck fails puts you in a much stronger position than scrambling to replace it after a breakdown.

Mission Financial works with owner-operators every day to structure financing around their timeline, not just their credit score. Reach out and we’ll help you find the right fit before your next repair bill makes the decision for you.

Frequently Asked Questions

How often should I replace a semi truck?

There’s no single mileage or age that works for every truck, but many fleets set a baseline around 400,000 to 500,000 miles or three to five years of service, since that’s typically when maintenance costs start climbing ahead of a truck’s first major engine overhaul.

Duty cycle, repair history, and how hard the truck works matter just as much as age alone. Most owner-operators use that baseline as a starting point, then rely on cost per mile and repair cost thresholds to fine-tune the actual replacement decision for each truck.

Is it better to repair or replace an older truck?

Compare the repair estimate with the truck’s current market value and your recent maintenance spending. If a single repair costs more than half the truck’s value, or annual maintenance runs above 150% of similar trucks in your fleet, replacement usually pays off faster than another repair.

Can I finance a truck with high mileage?

Yes. Lenders look at the full picture, including maintenance records, remaining useful life, and your business’s cash flow, not just the odometer. Financing options exist for older and higher-mileage trucks, so a high number on the dash doesn’t rule out approval on its own.

FMCSA Motus Registration System: What Owner-Operators Need To Know

FMCSA Motus Registration System: What Owner-Operators Need To Know

FMCSA Motus (1)

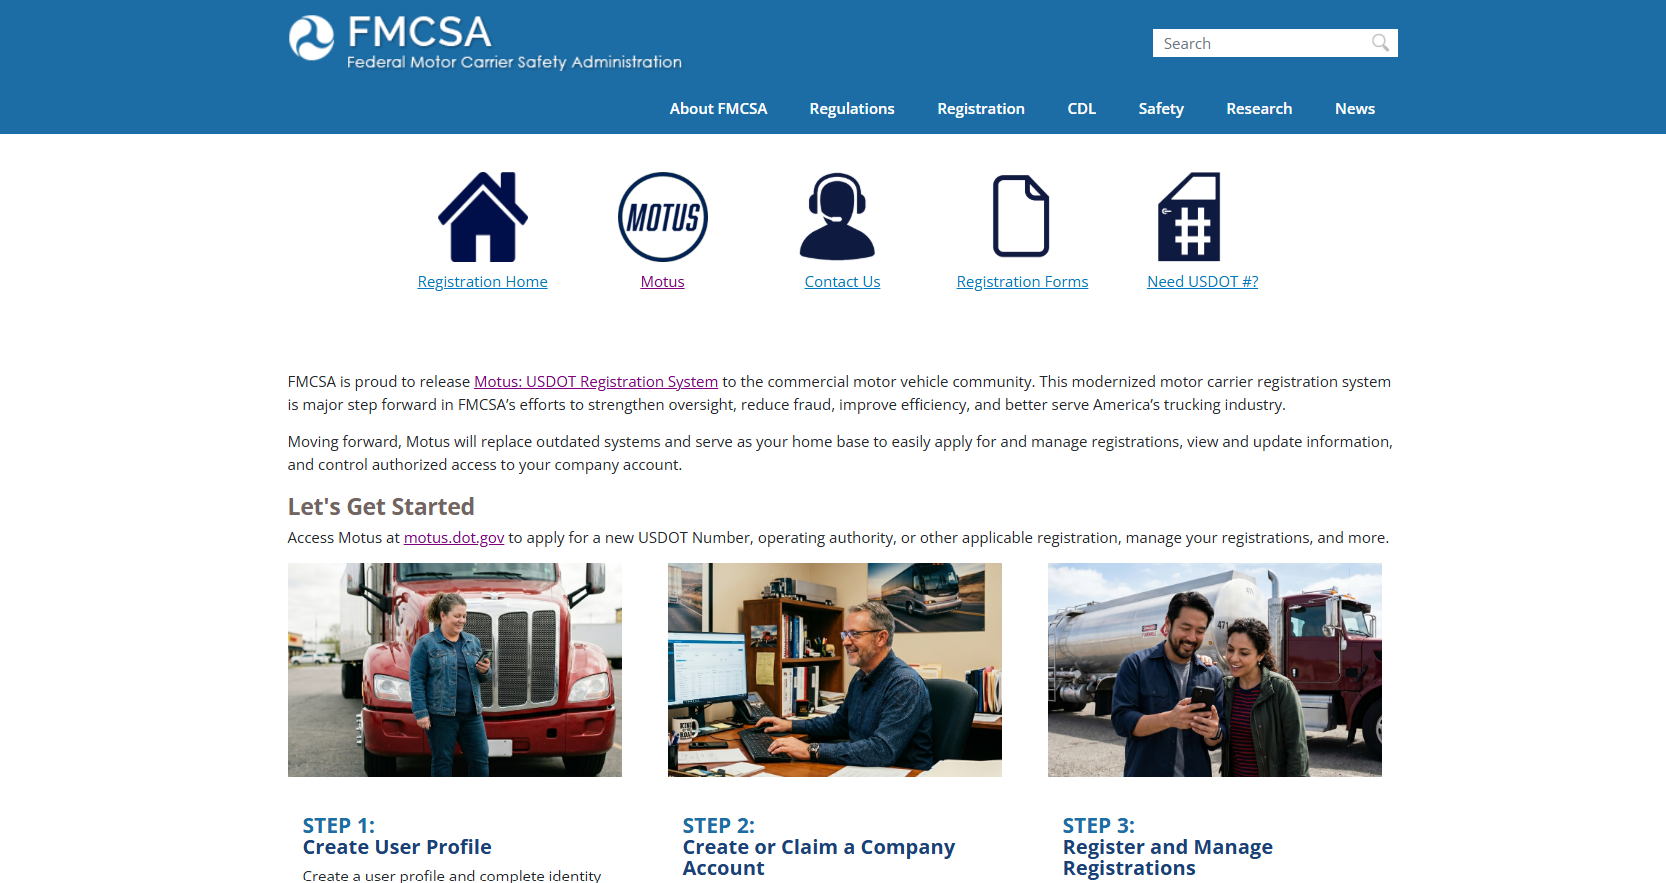
If you’ve logged into the FMCSA Portal recently, you’ve probably noticed something new staring back at you. That’s Motus, the agency’s new registration platform. It’s not a small update. It’s the biggest change to federal carrier registration in over a decade, and it lands alongside a broader wave of trucking industry regulations owner-operators are already tracking this year.

Here’s a clear breakdown of what changed, what stayed the same, and what you should do next.

TL;DR

FMCSA’s new Motus registration system replaced the old FMCSA Portal and URS in May 2026. Your MC number and USDOT number aren’t changing, and fees are the same as before ($300 per authority, free USDOT number).

The big changes are a required Login.gov identity verification (photo ID and facial scan, done by the owner personally) and a single dashboard for registration, insurance filings, and biennial updates.

Carriers are seeing longer processing times since launch, so apply early and double-check your account details, especially the Login.gov email tied to your company official.

FMCSA also paused USDOT deactivations for missed biennial updates since June 1, 2026, but that grace period is temporary.

What Is The FMCSA Motus Registration System?

Motus is the Federal Motor Carrier Safety Administration’s new online registration platform. It replaces the old Unified Registration System (URS) and consolidates several outdated tools into one dashboard.

From Motus, you can apply for a USDOT number, request operating authority, file your biennial update, and manage who has access to your company account.

FMCSA rolled Motus out in two phases:

  • Phase one launched in December 2025. It only applied to supporting companies, like BOC-3 filers and insurance providers.
  • Phase two opened Motus to every regulated entity, including motor carriers, brokers, and freight forwarders, in May 2026. FMCSA also retired the legacy URS and Licensing and Insurance filing systems that same week, so Motus is now the only path for new registrations and updates.

Why FMCSA Built A New System

For years, FMCSA registration lived across several separate systems that didn’t connect with each other. That included the Unified Registration System (URS), the Motor Carrier Management Information System (MCMIS), and the Licensing and Insurance System.

Each one held a different piece of a carrier’s record. For example, a carrier’s insurance status might update in one system without syncing to another.

That fragmentation created real openings for fraud.

Someone could hijack a legitimate carrier’s USDOT number and use it to book loads that never get delivered – a scheme known as double brokering. Others impersonated real carriers using stolen identity details, or registered a business at a fake address, like a P.O. box or a shared mail drop, just to look established on paper.

FMCSA has publicly warned carriers about this kind of identity theft for years, and has also flagged cases involving foreign actors targeting freight and cargo.

The purpose of Motus is to close those gaps.

It pulls registration, insurance filings, and compliance history into one centralized environment. And every account must have a verified Login.gov identity instead of a simple username and password.

That makes it much harder for someone to change a carrier’s contact information, hijack a DOT number, or set up a shell business using a fake address. Most schemes rely on that kind of unauthorized account access, so tightening it at the source should cut down on a lot of the scams carriers deal with today.

FMCSA Motus (3)

What Changed And What Didn’t

Here’s a look at what’s changed under Motus, what hasn’t, and where FMCSA’s own guidance stands right now.

MC Numbers Are Not Going Away

You may have heard that MC numbers are being phased out or eliminated. FMCSA has confirmed that that is not part of this Motus rollout.

Docket number prefixes (MC, MX, and FF) aren’t changing. Your existing USDOT number and docket number stay exactly as they are, and they remain the primary identifier for regulated entities.

USDOT Suffixes Only Apply To New Registrants

Motus does add letter suffixes to USDOT numbers, like a “-C” for a property carrier or a “-B” for a broker. But these suffixes currently apply only to companies registering for the first time.

If you already have a USDOT number, you won’t see a suffix added to it right now. FMCSA hasn’t announced a timeline for changing that.

Identity Verification Is Real And Strict

Motus requires the company official to verify their identity through Login.gov, which includes a photo ID scan and facial verification. This has to be done personally by the company owner or an authorized employee. It cannot be delegated to a consultant or a third-party service.

No New Permits, No BOC-3 Changes, Yet

FMCSA has confirmed that Motus does not introduce a new “Safety Registration” program at launch, and it hasn’t changed how BOC-3 process agent filings work.

Both of those have been floated as possible future changes, but neither is in effect today.

Registration Fees Haven’t Gone Up

Motus is a new system, not a new fee schedule. A USDOT number is still free. Operating authority still costs $300 per authority type, paid at the time you apply. BOC-3 filings and insurance costs work the same way they always have.

FMCSA Motus (1)

How To Claim Your USDOT Number In Motus

If you already operate under a USDOT number, you’ll need to claim your existing record rather than start over.

Here’s the general process:

  1. Log into Motus using the same Login.gov email tied to your old FMCSA Portal account.
  2. Complete identity verification, including the photo ID and facial scan step.
  3. Confirm your USDOT number is linked to your profile when it appears.
  4. Review your business information, including your address and vehicle count, for accuracy.
  5. Submit your claim for FMCSA review.

If your Login.gov email doesn’t match what’s on file, check your FMCSA Portal account first and confirm who’s listed as the company official. If that person has left the business or the email is outdated, update it in the Portal before you attempt to claim your number in Motus.

If you’re still locked out after that, call FMCSA’s Registration Customer Service Center or submit a ticket through Ask FMCSA and ask them to link your account to the correct record.

Expect Some Delays Right Now

Since Motus launched, a lot of carriers have reported longer wait times than usual. New authority applications, BOC-3 updates, and insurance filings have all been slower to process while FMCSA works through the backlog from the system switch. Some carriers are seeing this take several weeks rather than the near-instant approvals the old system sometimes offered.

If you’re applying for a new authority or making an urgent change, build in extra time. Submit early, double-check every field before you hit submit, and don’t assume a delay means something’s wrong with your application.

Behind On Your Biennial Update? Here’s Some Breathing Room

Every carrier has to file a biennial update every 24 months, based on the second-to-last digit of your USDOT number.

Missing that deadline normally deactivates your number. But since the Motus launch caused access problems for a lot of carriers, FMCSA has temporarily paused inactivations tied to missed updates since June 1, 2026.

That pause is temporary and FMCSA hasn’t said when it will end. If you’re behind on your update, don’t wait for the deadline to move again. File as soon as your Motus account lets you.

FMCSA Motus (2)

Why This Matters Beyond Compliance

An active, accurate USDOT record affects more than roadside inspections.

When you apply for operating authority to grow into new lanes, or when you’re financing your next truck, lenders and brokers check your FMCSA status before they’ll work with you.

A lapsed or inaccurate registration can slow down a loan approval or a load booking just as easily as it can trigger an out-of-service order.

A Quick Checklist For Getting Motus-Ready

If you haven’t touched your FMCSA Portal account in a while, run through this list:

  • Confirm your Login.gov email matches your FMCSA Portal company official on file.
  • Make sure the company official is the actual owner or an authorized employee, not an outside consultant.
  • Check whether your biennial update is due this year, based on your USDOT number’s last digits.
  • Gather a government-issued photo ID before you attempt identity verification.
  • Review your business address and vehicle count for accuracy before you submit anything.

Carriers who are just getting started, or who are working through a start-up checklist for their first truck, should plan for this identity verification step from day one. It’s now a standard part of getting your authority in place.

The Bottom Line

Motus is a real shift in how FMCSA manages carrier data, but it’s not the dramatic overhaul some headlines suggest. Your MC number is safe for now. Your USDOT number won’t suddenly grow a suffix.

What has changed is the login process, the identity checks, and where you go to manage your registration.

Take the time to confirm your account details are accurate. It’s a small task now that can save you a lot of trouble later, whether that trouble shows up at a roadside inspection or during a truck financing application.

If you’re weighing your options for financing your next truck, having a clean, current FMCSA record is one less thing standing between you and an approval.

Fleet Risk Management: Best Strategies for 2026

Fleet Risk Management: Best Strategies for 2026

Hand stopping a row of dominoes from falling, representing proactive fleet risk management

Running a semi-truck or small fleet in 2026 means more moving parts than ever. Tighter regulations, rising insurance premiums, and unpredictable repair costs all stack up fast. One bad incident can set an owner-operator back by months.

Effective fleet risk management is what keeps those risks from snowballing. If you’re operating one to ten trucks, this guide breaks down exactly what you need to know and do.

What Is Fleet Risk Management?

Fleet risk management is a proactive approach to identifying, evaluating, and reducing the physical and regulatory risks that come with operating commercial vehicles. It covers everything from driver behavior and vehicle maintenance to FMCSA compliance documentation.

Most fleets only react after something goes wrong. A proactive approach means building systems to spot and address risks before they cause damage.

In fleet operations, risk looks like accidents, breakdowns, cargo loss, regulatory fines, and insurance hikes. Any one of these can hit hard.

That’s why it’s important to identify exposure, assess likelihood and impact, put controls in place, document what you did, and review performance regularly.

Fleets that build this habit reduce risk before it becomes a problem.

Why It Matters More for Small Fleets

Large carriers absorb setbacks more easily. Owner-operators can’t. One at-fault accident or out-of-service violation can shut down your income. Your insurance rates take the hit for years. Building even a basic fleet risk management plan creates a real buffer between a bad week and a business crisis.

Chess piece knocking down king, symbolizing risk management strategy

The Biggest Fleet Risks Facing Owner-Operators in 2026

Understanding where fleet risk actually comes from is the first step in managing it. Here are the four areas that hit small fleets hardest.

Driver Safety and Behavior

Driver behavior causes more incidents than any other single factor. Speeding, distracted driving, and fatigue are the most common culprits. In 2022, large trucks were involved in approximately 503,000 police-reported crashes in the U.S., including 5,279 fatal crashes. One at-fault accident can spike your insurance premiums and follow your record for years.

Unsafe driving practices like harsh braking, rapid acceleration, and driver distraction aren’t just safety risks. They also wear down your truck faster and burn more fuel.

Fleet managers who track driver performance monthly catch these patterns earlier and address them before they escalate.

Vehicle Breakdowns and Deferred Maintenance

Skipping regular maintenance to save money costs far more in the long run. Vehicle-related factors, including tire issues, were recorded in 4 percent of large trucks involved in fatal crashes in 2022.

When a truck breaks down, you have to pay the repair bill and you also lose revenue for every day it sits idle. Vehicle downtime is expensive. Staying ahead of trouble codes, tire pressure, and brake wear through regular maintenance is the only way to control it.

Regulatory Non-Compliance

ELD mandates, hours of service rules, and DVIR requirements are all mandatory under federal regulations. The FMCSA’s Compliance, Safety, Accountability (CSA) program tracks violations over 24 months. Even small violations can accumulate into a score that affects your insurance rates and ability to book loads.

Falling behind on compliance documentation creates risk that builds slowly in the background. By the time a DOT inspection surfaces a problem, the window to fix it has already closed.

Cargo and Vehicle Theft

Theft is an underrated financial risk for owner-operators hauling valuable loads. Beyond the value of what’s stolen, you’re also looking at missed delivery penalties and insurance claims. Your liability exposure can extend well past the load itself.

Building cargo security into your overall risk strategy is worth the time.

Ratchet straps securing wooden cargo on a commercial truck bed

5 Effective Fleet Risk Management Strategies for 2026

A strong fleet risk management plan doesn’t have to be complicated. Here’s what actually helps owner-operators and small fleet owners mitigate risk and improve fleet safety in 2026.

1. Build a Written Driver Safety Policy

Safe driving practices need to be written down, not just talked about. A formal policy defines acceptable behavior behind the wheel including speed limits, rules around phone use, and mandatory rest requirements.

It also needs a clear process for how violations get documented and how you coach drivers after incidents.

Building a safety-first company culture starts with clear, written standards. We’ve found that fleets with consistent driver training programs see fewer repeat violations and lower insurance claims over time.

Coaching drivers on specific behaviors (like harsh braking or distracted driving) is far more effective than a general safety reminder. Make training a regular rhythm, not a one-time event.

2. Commit to a Preventive Maintenance Schedule

Fleet maintenance is the backbone of risk reduction. Set scheduled intervals for tires, brakes, engine checks, and lights. Complete pre-trip and post-trip inspections as required under FMCSA’s DVIR rules.

Skipping inspections is a compliance gap. Staying current on maintenance records and catching trouble codes early keeps your CSA score clean and reduces vehicle downtime. A truck that’s properly maintained earns more and costs less. It also protects your fleet efficiency over the long haul.

3. Stay Compliant with FMCSA Rules Year-Round

Fleet compliance requires daily execution, not a scramble before inspection season. ELD logs need to be accurate. HOS records need to be audit-ready at all times.

The Commercial Vehicle Safety Alliance (CVSA) publishes the inspection standards that roadside officers use. Knowing what they’re checking for helps you stay ahead of it.

Keep your compliance documentation organized and up to date. Fleets that know how to prepare for roadside inspections don’t need to stress when road-check season arrives.

4. Use Telematics and Fleet Technology

Telematics systems are among the most cost-effective tools for managing fleet data and mitigating risks. GPS tracking, dashcams, and real-time monitoring of driver performance give fleet managers visibility into patterns before they become incidents. Catching harsh braking or rapid acceleration early means you can coach drivers and protect your equipment.

Even basic fleet management software tracks speeding events, harsh braking, and idle time. That data tells you where risk is concentrating across your fleet. The investment almost always pays for itself compared to one preventable accident or out-of-service violation.

5. Have a Clear Incident Response Plan

Knowing what to do after an accident is as important as preventing one. When something goes wrong, the first 24 hours define everything that follows. Your insurance claim, your CSA record, and your legal exposure all depend on what you do next.

Document everything immediately. Take photos at the scene, collect driver statements, and pull your ELD logs and maintenance records for that vehicle.

In our experience, fleets that handle incident response well have a written protocol ready before anything happens. Having that process documented means your driver knows exactly what to do, even under stress. Thorough accident reporting gives your insurer what they need to process claims quickly. It also protects you if the incident is disputed later.

Fleet manager taking notes while reviewing fleet risk management strategies

How Financing Fits Into Your Risk Management Plan

We’ve seen firsthand how financing decisions directly impact a fleet’s ability to stay safe and compliant. Running a truck that’s past due for repairs because cash is tight is a risk, not a strategy.

Don’t Let Repair Costs Force You to Run an Unsafe Truck

Cash flow pressure is real for owner-operators. But delaying repairs to keep a truck moving creates bigger problems down the road. A commercial truck repair loan lets you handle maintenance costs without throwing off your cash flow.

Getting the truck fixed now costs far less than a tow bill or an accident caused by worn brakes.

Upgrading Aging Vehicles That Are Becoming a Liability

At some point, an older truck starts costing more in repairs and vehicle downtime than financing a replacement would. That’s when it’s worth looking at an owner-operator loan to upgrade to safer, more reliable equipment. Newer trucks come with better safety features and fewer surprise repair bills.

Access Capital Quickly When You Need It

When unexpected costs hit, fast access to capital matters. A commercial vehicle title loan lets you borrow against your truck’s title while keeping it on the road. If you’ve had some credit challenges, bad credit loan options are available too.

Having financing options ready is part of building a resilient fleet operation.

Conclusion

Fleet risk management is a daily discipline. Staying proactive about driver safety, vehicle maintenance, and regulatory compliance protects your trucks, your income, and your business. The payoff is real: lower insurance premiums, fewer breakdowns, and a cleaner CSA score that works in your favor.

At Mission Financial Services, we work with owner-operators and small fleets every day. In our experience, the fleets that stay safest are also the ones that stay financially flexible.

Whether you need repair financing, equipment upgrades, or quick access to capital, we’re here to help. Reach out to us today to find the right lending solution for your operation.

Archives

Sign Me Up!

Stay up to date with the latest news in the commercial trucking industry.

Contact Us
close slider