Office: (404) 975-4800

Commercial Financing

What Credit Score Do You Need to Finance a Semi Truck?

What Credit Score Do You Need to Finance a Semi Truck?

Wooden letter tiles spelling “credit” on a rustic wood table, with loose tiles scattered around it

There’s no single minimum credit score to finance a semi truck, because every lender sets its own cutoff. Banks usually want a score above 700. Specialty truck lenders often work with scores in the 500s and 600s, and some go lower.

Below, we cover how your score affects your rate and down payment. We also explain what else lenders weigh and how to improve your odds.

TL;DR

  • Banks typically want a credit score above 700 for semi-truck financing.
  • Specialty and online lenders set minimums as low as 550, and some consider scores in the 400s.
  • Borrowers with scores under 680 usually pay 2 to 5 percentage points more in interest.
  • Lenders also weigh your CDL experience, time in business, down payment, and the truck itself.

Typical Credit Score Requirements for Semi Truck Loans

Credit requirements vary by lender type, but you can expect a stricter review than you’d get for a standard auto loan on a personal vehicle.

Commercial truck lenders usually check your personal credit score first, since new owner-operators rarely have a business credit score yet. They use your FICO score to sort applicants into credit tiers. FICO scores run from 300 to 850 and fall into five bands (myFICO).

FICO band Score range What it usually means for truck financing
Exceptional and very good 740 to 850 Bank and SBA loans are realistic, with the lowest rates
Good 670 to 739 Most lenders will approve you, but a score under 680 can add to your rate
Fair 580 to 669 Specialty truck lenders are your best bet, with higher rates and bigger down payments
Poor Below 580 Approval depends on your personal credit history, experience, and down payment

Banks typically want scores above 700, and online equipment lenders can have minimums as low as 550. Bank-backed SBA loans can finance trucks and other equipment for up to 10 years.

We go further for many applicants with flexible commercial truck financing. In some cases, we can finance scores as low as the 400s, depending on your overall credit.
Laptop screen showing an 825 credit score rated excellent on a credit monitoring dashboard

How Your Credit Score Affects Loan Terms for Commercial Truck Financing

Your credit score shapes three parts of your loan: the interest rate, the down payment, and your approval odds.

Interest Rates

Lower scores mean higher rates. FreightWaves found that specialty lenders typically charge 7% to 12% for qualified borrowers. At most specialty lenders, borrowers with scores under 680 pay roughly 2 to 5 percentage points more.

In our experience, rates for challenged credit usually land near 18% to 20%.

Here’s what a 5-point difference looks like on a $40,000 loan over 48 months:

  • At 15%: You’d pay about $1,113 a month and about $13,400 in total interest.
  • At 20%: You’d pay about $1,217 a month and about $18,400 in total interest.

That’s about $104 more each month and roughly $5,000 more over the life of the loan.

Your credit score isn’t the only factor. Your commercial truck financing rates also depend on the loan term and the truck’s age.

Down Payments

Lenders ask for a bigger down payment when your credit score is lower. A bigger down payment reduces lender risk and lowers your loan balance.

Borrowers with good credit usually put 10% to 20% of the purchase price down. Strong credit can also open up zero-down semi-truck financing with some lenders.

Weaker credit or a shorter business history pushes that higher. For example, a borrower with a 620 score and 18 months in business might need 25% to 30% down. On a $100,000 truck, that’s $25,000 to $30,000 upfront.

Approval Likelihood

A higher score lets you compare offers from banks, credit unions, and specialty lenders. A lower score narrows your options, but it doesn’t necessarily close them completely.

However, a bankruptcy or repossession within the last year would make approval much harder. Older marks matter less, especially with a steady payment record since.
Person holding a credit card while typing on a laptop, applying for semi truck financing online

What Lenders Look at Besides Your Credit Score

Most commercial truck lenders review your whole application, not only the number on your credit report. We call ourselves a common-sense lender for that reason.

Trucking Experience

Lenders want proof you can run a truck safely and profitably. A Class A CDL is the starting point.

We look for at least three years of verified driving experience. Newer drivers with a larger down payment are reviewed case by case.

If you plan to hire a driver instead, financing a semi-truck without a CDL follows different rules.

Time in Business

Banks usually want at least two years in business, and newer businesses often pay higher rates. A written business plan showing your expected lanes, rates, and costs gives a lender more to go on.

If you want to finance multiple trucks, your payment history on existing truck loans counts heavily.

An active DOT number and MC authority show you’re set up to haul. Choosing the best business structure for a trucking business also helps you build business credit over time.

Business Revenue and Bank Statements

Lenders usually ask for three to six months of business bank statements and two years of tax returns. They use them to check your annual revenue, cash flow, and debt-to-income ratio. Steady revenue through slow freight months helps your case.

Keep business and personal accounts separate. Mixed accounts make it harder for a lender to see what your trucking business earns.

Expect most specialty lenders to ask for a personal guarantee too. That makes you personally liable if your business can’t repay. Read the financing agreement carefully before you sign.

The Truck You Choose

The truck is the lender’s collateral, so the make, model, year, and mileage of your Class 8 truck all matter.

You’ll usually submit a spec sheet with the VIN number, engine, transmission, and mileage. Trucks over 10 years old with very high mileage are harder to finance. Mileage over 500,000 can add a risk premium to your rate.

We recommend a truck under 10 years old in good condition. It keeps maintenance costs down and helps your loan terms.
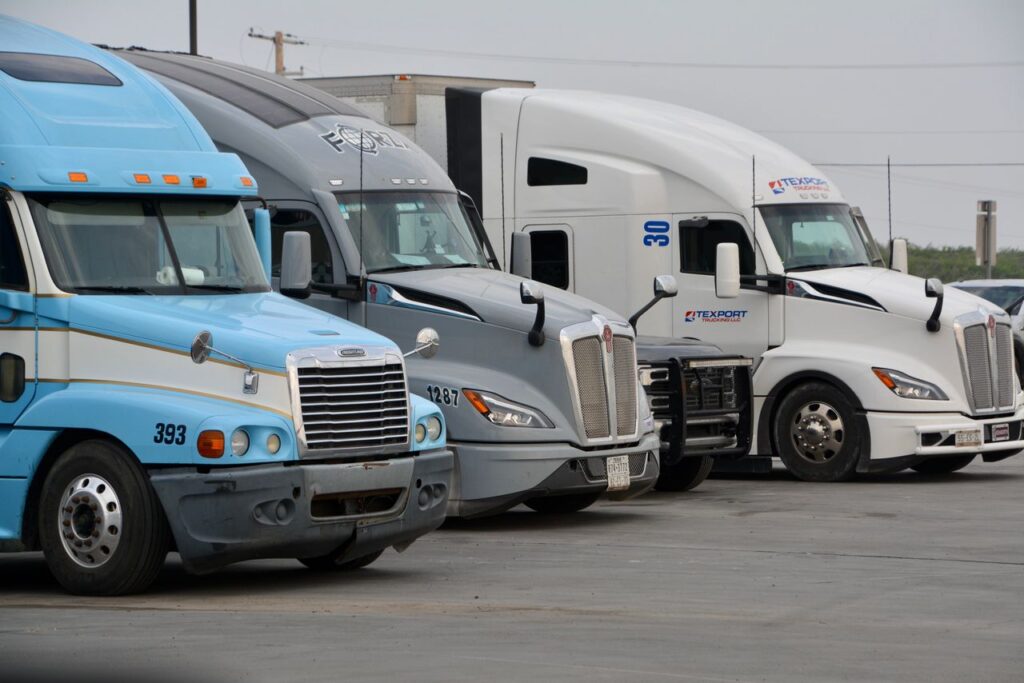
Three Class 8 semi trucks in light blue, gray, and white parked side by side in a truck lot

How to Get Approved With Challenged Credit

You can improve your approval odds before you apply, even with a low score. These steps make the biggest difference.

Check Your Credit Reports First

Errors on your credit report can drag down your score. You can check your reports from all three credit bureaus for free every week (FTC).

Dispute anything that’s wrong before your loan application. Errors can slow down the whole financing process.

Rebuild Your Credit Score

According to myFICO, payment history makes up 35% of a FICO score, so on-time payments help the most. Debt levels make up another 30%.

Pay every bill on time and pay down credit card balances. Avoid opening new accounts in the months before you apply.

Rebuilding credit takes months, so start well before you shop for a truck.

When a lender checks your credit for a loan application, it’s called a hard inquiry. Each one usually takes less than five points off your FICO score (myFICO). The effect fades after a year, so getting quotes from multiple lenders won’t sink your score.

Ask whether a lender can prequalify you with a soft credit pull, which doesn’t affect your score.

Save a Bigger Down Payment

A larger down payment lowers your loan balance and the lender’s risk. It’s the fastest way to offset a low credit score. A trade-in can count toward it, too.

It also means lower monthly payments, which leaves more cash for fuel costs, insurance, and maintenance.

Pick an Affordable Truck

The truck’s price sets your loan size, so a cheaper truck usually means an easier approval. Check how much a semi-truck costs before you set a budget. A well-kept used commercial truck often hits the right balance of price and reliability.

Your budget should also cover insurance, registration, fuel, and maintenance. Those costs start the day you take the keys.

Leasing is another route some drivers use to get started. It can look cheaper upfront because lease payments usually run lower than loan payments. However, you don’t own the truck at the end. So none of those payments build equity. Leases can also cap your annual miles and charge for excess wear, which hurts on long-haul routes. Our loans are purchase contracts, and we don’t offer leases.

If you plan to stay in trucking, buying builds equity you can trade in or sell later. Comparing leasing a semi-truck vs. buying one can help you run the numbers.
White semi truck pulling a dry van trailer down a highway on a sunny day, a common purchase for owner-operators checking what credit score they need to finance a semi truck

Final Thoughts

Your credit score matters for semi-truck financing, but it’s only one of the requirements that lenders weigh.

Banks usually want 700 or higher. Specialty lenders that focus on owner-operator financing look at your experience, down payment, and the truck too.

If your credit isn’t perfect, start your credit application anyway. We’ll review your full history and get back to you within four hours.

Frequently Asked Questions

Can I Finance a Semi-Truck With a 500 Credit Score?

Yes, some lenders will finance a semi truck with a 500 credit score. Expect a higher rate and a down payment of 20% to 30%. We review your overall credit, not only the score.

Can I Finance a Semi With Bad Credit?

Yes, specialty lenders, like Mission Financial, offer bad credit semi-truck loans. Collections, charge-offs, and older bankruptcies don’t automatically rule you out.

How Hard Is It to Get Financed for a Semi-Truck?

Financing a semi-truck is hard with a bank but much easier with a specialty truck lender. Your experience, down payment, and the truck’s condition matter as much as your score.

New drivers can look at first-time buyer semi-truck loans, which are built for applicants without a trucking track record.

How Much Is a Monthly Payment on a $70,000 Truck?

A $70,000 loan over 60 months costs about $1,557 a month at 12% or about $1,855 at 20%. Taxes, fees, and insurance aren’t included.
Hidden Costs in Truck Financing: What Lenders Don’t Put in the Ad

Hidden Costs in Truck Financing: What Lenders Don’t Put in the Ad

Man in a blue shirt looking up thoughtfully against a background of dollar signs while weighing truck financing costs

Truck loan ads often lead with a rate near 8%. Once fees, credit adjustments, and loan terms are added, the true cost is usually higher.

This guide covers the fees, terms, and requirements that raise your total cost. It ends with questions to ask before you sign.

TL;DR

  • Advertised truck loan rates start around 7.9% to 8.5%, but real APRs run from about 6% to 35%.
  • Compare the annual percentage rate (APR), not the interest rate, because the APR includes most fees.
  • Origination fees, documentation fees, and dealer add-ons can add thousands to what you finance.
  • Long loan terms, prepayment penalties, and personal guarantees raise your cost and your risk.

Why the Advertised Rate Isn’t the Rate Most Truckers Pay

An advertised rate is a best-case number. It usually goes to borrowers with strong credit, a newer truck, and years in business.

FreightWaves’ May 2026 review of the truck financing market found advertised starting interest rates of 7.9% to 8.5%.

Real APRs ranged from roughly 6% to 35%, depending on credit, lender type, time in business, and the truck. The same review found:

  • Traditional bank loans run about 4% to 8% APR, but banks usually want scores above 700.
  • A credit score below 680 can add roughly 2 to 5 percentage points at most specialty lenders.
  • Less than two years in business, or a truck over seven years old, can add a risk premium.
  • A 620-score carrier buying a 2017 truck with 650,000 miles could see rates of 15% to 25%.

Lenders only quote your real rate after credit checks and a full application. Your commercial truck financing rates depend on your whole file, not on the number in an ad.

Smartphone calculator on printed financial charts beside a notebook and laptop, used to work out hidden costs in truck financing

Interest Rate vs. APR: Which Number Should You Compare?

Compare the annual percentage rate (APR). The APR combines your interest rate with most upfront loan fees. That gives you a more complete yearly cost of borrowing than the rate alone.

Here’s how a single fee changes the math. Take a $100,000 loan at 8% for 60 months with a $2,500 origination fee.

The payment is about $2,028 a month. But if the lender deducts the fee from your funds, you only receive $97,500.

That pushes the APR to about 9.1%, even though the ad still says 8%.

APR doesn’t cover everything, though. Insurance, late fees, and prepayment penalties usually aren’t part of it.

Commercial lenders don’t always list an APR on a truck loan quote. If yours doesn’t, ask for it in writing before you sign.

Loan Fees That Don’t Show Up in the Ad

Fees cause most of the gap between an ad and a signed contract. These are the ones seen most often.

Origination and Documentation Fees

An origination fee covers the lender’s cost to set up your loan. A documentation fee covers the paperwork and filing.

Both can be a flat amount or a percentage of the loan. Ask for each one in dollars, in writing, before you sign.

Also ask whether any fees come out of the funds you receive at funding. For small fleets, these fees repeat on every truck you finance.

We list ours up front. Our dealership contracts, for example, include a $495 loan doc fee and a 16% prepaid finance charge. A prepaid finance charge is a finance cost paid when the loan starts. It’s built into your APR.

Dealer Fees and Add-Ons

Dealerships can add document fees, dealer preparation charges, extended warranties, and service contracts to the sales order.

Some add-ons are worth it. A service contract can save you from a major engine bill on an older truck. Others only raise the amount you finance, and you pay interest on every dollar of it.

Some dealers also earn a spread on the loans they arrange, which can raise your rate.

Sales Tax, Registration, and Licensing Fees

Sales tax and title costs depend on your state. So do registration and licensing fees. These additional costs can add thousands to the out-the-door price.

Interstate carriers also pay apportioned registration, which splits commercial truck license plate costs across the states they run.

Then there’s the federal heavy vehicle use tax. It applies to trucks at 55,000 pounds or more and reaches $550 a year above 75,000 pounds (IRS).

Buying new? Most heavy trucks and tractors carry a 12% federal excise tax on the first retail sale. Ask whether the dealer’s purchase price includes it. Used trucks don’t pay it again.

Man stacking piles of coins, representing costs

Loan Terms That Raise Your Total Cost

A long-term loan or a prepayment penalty can cost more than any single fee. Check these three terms closely.

Longer Loan Terms

A longer loan term gives you lower monthly payments but raises the total interest you pay. Here’s a $100,000 loan at 12%:

Loan term Monthly payment Total interest
60 months About $2,224 About $33,500
84 months About $1,765 About $48,300

The lower payment costs about $14,800 more in interest. Meanwhile, maintenance costs climb every year you own the truck.

A long term can also leave you owing more than the truck’s resale value, especially on an older truck.

We’ve found that shorter terms usually work out better for owner-operators. You build equity faster, and the loan ends before the big repair years start.

Prepayment Penalties

A prepayment penalty is a fee for paying off your loan early. Some lenders charge one, and others don’t.

Ask about it before you sign, especially on a long-term loan. A penalty can wipe out the savings from refinancing or selling the truck early.

We don’t charge a prepayment penalty. Our loans are simple interest contracts, so paying early reduces the interest you owe.

Personal Guarantees

A personal guarantee makes you personally responsible for the debt if your business can’t pay. Your home, savings, and other assets could be at risk.

Most specialty and online truck lenders require one. So does the SBA on most of its loans.

Ask whether the guarantee is limited to a set dollar amount or unlimited. An unlimited guarantee puts all of your personal assets at risk.

Three men talking and smiling around a laptop at an office table while reviewing truck loan options

Insurance and Down Payment Costs to Budget For

Every lender requires insurance and a down payment, and both hit your cash flow before your first load.

Required Insurance Coverage

Lenders require coverage that protects the truck, usually physical damage coverage on top of your liability policy.

Ask about the required deductible and whether the lender must be listed as loss payee. Get insurance quotes before you commit to a truck.

After a total loss, GAP insurance for semi-trucks covers what you owe beyond the truck’s value.

Down Payment and Cash Reserves

Most lenders want 10% to 20% down from borrowers with good credit. Weaker credit or less time in business can push that to 25% or 30%.

A larger down payment lowers your payment and can help with loan approval when your credit is thin.

Plan the down payment as its own expense. Paying it from your operating reserves can leave you short on fuel costs and unexpected repairs.

A zero-down semi-truck financing offer may look easier, but you finance more and pay interest on it all.

Questions to Ask Before You Sign a Truck Loan

The right questions expose hidden fees before they become part of your debt. Ask every lender these:

  • What is the APR, and how does it compare with the interest rate?
  • What fees are included, and how much is each one in dollars?
  • Is there a prepayment penalty?
  • Do I need a personal guarantee, and is it limited or unlimited?
  • What insurance do you require, and what deductible?
  • What is the total amount I’ll repay over the full loan term?
  • Is there a balloon payment at the end?

Get the answers in writing. If a lender won’t put a fee in writing, ask why before you go any further.

Signed contracts also come with lender protections, so read those terms as closely as the rate.

Borrowers who skip these questions are the ones most likely to find their truck financing costs more than expected.

Person holding a pencil over a notebook while using a calculator to add up truck loan fees and costs

Final Thoughts

The rate in a truck loan ad is only the starting point. Fees, loan terms, insurance, and the down payment all shape what you’ll pay.

Compare APRs and total repayment, not monthly payments alone. Get every fee in writing before you sign.

If you want a lender that lists its fees up front, start your credit application. We’ll get back to you within four hours.

Frequently Asked Questions

Is Financing a Truck a Good Idea?

Financing a truck is a good idea when its revenue covers the payment, insurance, and maintenance with room to spare. A truck is a business investment, and financing lets you start earning without paying cash.

What Is Low-Cost Financing?

Low-cost financing means a low APR, few fees, and a term short enough to limit total interest. The lowest advertised rate isn’t always the lowest total cost.

Are There Hidden Fees in Truck Loans?

Yes, truck loans often include origination, documentation, and dealer fees that aren’t in the ad. Ask for a written list of every fee before you sign.

Can I Pay Off a Truck Loan Early?

Usually, yes. Some lenders charge a prepayment penalty, so check your contract first. We don’t charge one on our contracts.

How to Refinance a Semi-Truck Loan (And When You Should)

How to Refinance a Semi-Truck Loan (And When You Should)

Truck owner reviewing paperwork on a clipboard with a mechanic in front of a blue semi truck.

To refinance a semi-truck loan, you take out a new loan that pays off your current one. The new lender then holds the lien on your title until you pay off the loan.

Most owner-operators refinance for a lower rate, a smaller monthly payment, or a way out of a bad lease-purchase deal.

At Mission Financial, we refinance truck loans and finance lease-purchase buyouts. We’ve seen which deals save drivers money and which ones only add months of payments.

What Is Semi-Truck Loan Refinancing?

Semi-truck loan refinancing means replacing your current truck loan with a new one that has different terms. The new lender pays off your old loan, and you make payments to the new lender instead. It’s a type of equipment financing, and your truck stays as the collateral.

When Does It Make Sense to Refinance a Semi-Truck Loan?

Refinancing makes sense when the new loan costs you less in total or fixes a cash flow problem. It doesn’t make sense when fees or a longer term wipe out the savings.

Good Reasons to Refinance

  • Your credit has improved: A higher credit score than when you bought the truck can qualify you for a lower rate.
  • Your payment is squeezing your cash flow: Lower monthly payments free up money for fuel, insurance, and slow freight weeks.
  • You’re stuck in a lease-purchase deal: A buyout loan makes the truck yours, with no carrier controlling your loads.
  • You’re juggling business debts: Rolling existing debt into a single monthly payment helps only if the combined rate is lower.

When Refinancing Won’t Help

  • You’re upside down: If you owe more than the truck is worth, expect lenders to want a larger down payment.
  • Your loan has a big prepayment penalty: The penalty can cancel out what you’d save on interest.
  • The truck is aging out: High-mileage trucks often only qualify for short terms or higher rates.

In our experience, the drivers who save the most refinance after a solid run of on-time payments. By then, their credit score usually reflects that history.

Young driver sitting in the open cab of a yellow commercial truck, looking back over his shoulder.

How to Refinance a Semi-Truck Loan in 6 Steps

The process for a refinance looks a lot like getting your original loan.

1. Review Your Current Loan Terms

Start with your last statement and your loan contract. Write down these numbers:

  • Your current interest rate and APR
  • The remaining balance and the number of payments left on your financing term
  • Your payoff amount, which sets your new loan amount (ask for a written payoff quote)
  • Any prepayment penalty or early payoff fee

A prepayment penalty is a fee some lenders charge if you pay a loan off early. Many commercial truck contracts carry clauses like this.

Also check whether your loan uses simple interest. With a simple interest contract, paying early cuts your interest. Some precomputed loans don’t give you that break.

2. Check Your Credit Score

Pull your credit report before any lender does. Look for errors and old collections you can clear up.

Most truck lenders check your personal credit with a hard credit pull. Established businesses may also have their business credit reviewed.

A hard inquiry usually takes less than five points off a FICO score.

FICO groups mortgage, auto, and student loan inquiries made within 14 to 45 days into one. A commercial truck inquiry may not get that treatment, so keep your shopping to a tight window.

3. Find Out What Your Truck Is Worth

Lenders compare your loan balance to the truck’s value. They call this loan-to-value, and if the balance is higher, you’re upside down. That gap shapes your down payment requirements. A used truck can be worth far less than its purchase price.

Check recent sale prices for similar trucks. If you’re upside down, GAP coverage for semi-trucks pays the difference if the truck is totaled.

4. Gather Your Documents

Most lenders will ask for:

  • Your current loan statement and payoff quote
  • The truck’s title and registration
  • Your CDL or driver’s license
  • Recent bank statements or tax returns
  • Proof of insurance
  • A spec sheet with the year, make, model, VIN, and mileage

Running an LLC or corporation? Add your operating agreement or articles of incorporation.

A newer trucking business with little history may need a business plan that shows how the truck brings in revenue.

Trucking business owner reviewing paperwork and filling out a financing application at a desk

5. Compare Lenders on APR and Terms

Compare lenders on APR. It includes fees, so it shows the full cost of the loan.

FreightWaves reports commercial truck loan APRs in 2026 run from about 6% to 35%.

Ask each lender if it charges an application fee. Be wary of any lender that claims to guarantee approval before it reviews your file.

Our guide to commercial truck financing rates explains what moves your rate across refinancing options.

6. Sign the New Loan and Transfer the Lien

Once you’re approved, check the rate, term, payment, fees, and payoff rules before you sign.

Your new lender pays off the old loan and records itself as the lienholder. Keep making old payments until the payoff is confirmed, or you risk a late fee and a credit ding.

How Much Can You Save by Refinancing?

Your savings depend on the rate drop, the term, and fees. Here’s an example with a $35,000 balance and 30 months left at 27% APR. Figures are estimates and exclude fees.

Option Monthly payment Total interest left
Keep current loan (27%, 30 months) About $1,617 About $13,509
Refinance at 20% for 30 months About $1,492 About $9,761
Refinance at 20% for 36 months About $1,301 About $11,826

The 30-month refinance is best for saving money, cutting interest costs by about $3,748. The 36-month option frees up about $316 a month. Stretch the term too far, though, and the extra interest eats your savings.

Common Refinancing Mistakes to Avoid

Most refinancing mistakes come from focusing on the monthly payment and ignoring the total cost.

  • Ignoring fees: Doc fees, title fees, and prepayment penalties all add to your equipment costs.
  • Overextending the term: A loan that outlasts the truck’s working life leaves you paying for a parked rig.
  • Paying off the truck with a personal loan: Unsecured loans have no collateral, so lenders price in more risk. The debt also sits in your name, not the business’s.
  • Hiding problems: Lenders find past repossessions or liens anyway, and surprises slow approval.
  • Skipping tax advice: A new loan can change your interest deduction, so check with your CPA or financial advisor.

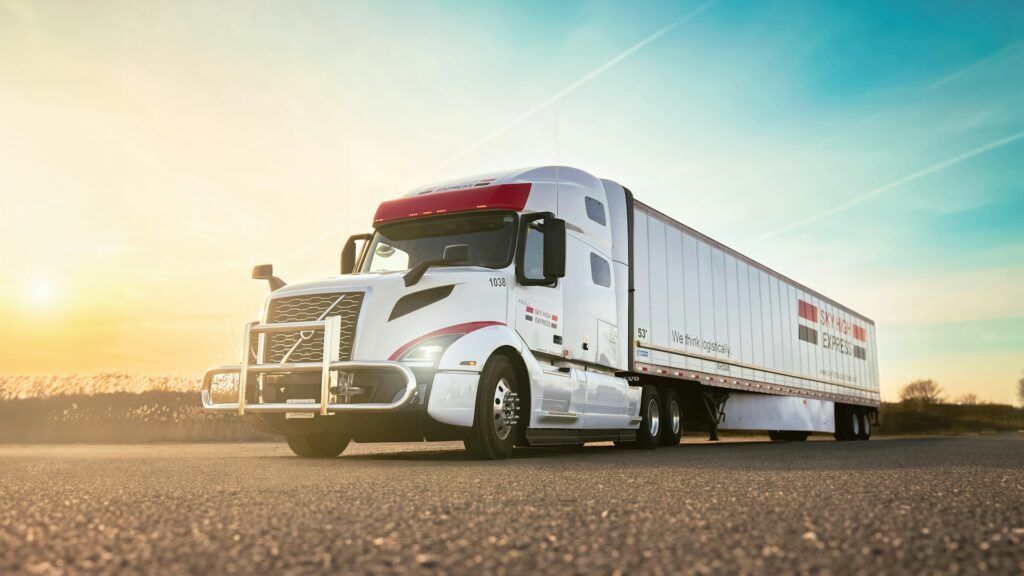
White semi truck with a 53-foot dry van trailer parked on an asphalt lot at sunset.

How Refinancing Works at Mission Financial

We refinance semi-truck loans and lease-purchase buyouts for owner-operators and small fleets in every state except Alaska and Hawaii.

  • Short terms: Refinance terms run up to 36 months, and payments typically don’t exceed $1,300 a month.
  • No prepayment penalty: Our loans are simple interest contracts, so you can pay extra and save on interest.
  • Overall credit: We weigh your full credit history, down payment, and truck along with your score.
  • Credit building: We report to all major credit bureaus, so on-time payments help rebuild your credit.

Our financing options go beyond refinancing. We also finance used truck purchases from dealers and private sellers, small fleet loans for multiple trucks, and first trucks for a new owner-operator.

Worried about your score? Our bad credit truck loans are built for drivers other lenders turn down.

Final Thoughts

Run the numbers on total cost, check for prepayment penalties, and shop lenders within 14 days.

Ready to see what you’d save? Fill out our credit application, and we’ll get back to you within four hours.

Frequently Asked Questions

What is the 2% rule for refinancing?

The 2% rule is a mortgage rule of thumb. It says to refinance if you can cut your rate by two points. For truck loans, compare total interest plus fees on both loans instead.

Can I lower my monthly payments by refinancing my semi-truck loan?

Yes. A lower rate, a longer term, or both will lower your payment, but a longer term usually adds interest.

How does refinancing a semi-truck loan affect my credit score?

Expect a small, short-term dip from the hard inquiry. On-time payments on the new loan help your score recover.

Can I refinance a semi-truck loan with bad credit?

Yes, with the right lender. A lower credit score or challenged credit shortens your list of lenders, but it doesn’t empty it.

What Is Trucking Equipment Financing and How Does It Work?

What Is Trucking Equipment Financing and How Does It Work?

Person counting cash over financial reports, a phone calculator, and a laptop while budgeting for a truck purchase

Trucking equipment financing is a loan or lease that pays for the trucks, trailers, and other gear your business needs. You pay it back in fixed monthly payments over a set term.

The equipment itself is the collateral. That makes approval easier than with an unsecured business loan, even if your credit has a few dings.

What Is Trucking Equipment Financing?

Trucking equipment financing is funding for the business equipment that keeps your loads moving. Common examples include:

  • New and used semi trucks and other commercial vehicles
  • Dry van, reefer, and flatbed trailers
  • Box trucks and dump trucks
  • Specialized equipment, like refrigeration units, liftgates, or tires

Equipment financing companies fund restaurant equipment, medical equipment, manufacturing equipment, and plenty more. In 2023, 82% of businesses that acquired equipment or software used some form of financing.

A semi truck is the biggest capital investment most owner-operators make. Few can buy equipment outright, given what a semi truck costs. Most buyers finance instead. The best fit is a lender who knows the trucking industry and how age, mileage, and engine affect value.

New equipment adds a 12% federal excise tax to the first retail sale of most heavy trucks and trailers (26 U.S. Code 4051).

How Does Trucking Equipment Financing Work?

A lender pays the seller for the equipment, and you repay the lender over time with interest. Here’s how it typically plays out:

  1. You pick the truck or trailer and get a written quote from the seller.
  2. You apply with a lender and make a down payment.
  3. The lender pays the seller and records a lien on the title.
  4. You make monthly payments until the loan is paid off.
  5. The lender releases the lien, and the equipment is fully yours.

If you stop paying, the lender can repossess the equipment, which is why approval is easier than for unsecured loans.

Person using a calculator and writing figures on paper to estimate semi-truck loan payments

Example of Equipment Financing

Say you buy a used semi truck for $50,000 and put 25% down ($12,500). You finance the remaining $37,500 at a 20% contract rate for 42 months.

Your payment would be about $1,249 a month, with about $14,943 in total interest.

Our 16% prepaid finance charge and $495 doc fee add about $6,500 on top of that. If you roll them into the loan, your payment comes to about $1,465 a month.

Always compare lenders on APR, since it includes fees as well as the contract rate.

Types of Trucking Equipment Financing

The main equipment financing options are equipment loans, leases, bank loans, SBA loans, and dealer financing.

Equipment Loans

An equipment loan is a business loan you use to purchase equipment, like a specific truck or trailer. You own it from day one, and the lender holds a lien until you pay it off.

Some lenders call this an Equipment Finance Agreement (EFA). Lenders structure financing around the truck’s age, the loan amount, and your credit, so terms vary.

Equipment Leasing

With equipment leasing, the leasing company owns the truck. You pay to use it for a set term. Leases usually come with lower upfront costs than a purchase.

  • Capital lease: Works like a purchase. You usually buy the equipment at the end for a set residual price.
  • Operating lease: Works like a rental. You return the equipment at the end, often with mileage limits.

Bank and Credit Union Loans

Banks and credit unions usually offer the lowest interest rates, but they’re the hardest to qualify for.

They favor established businesses with 2+ years of history, strong credit, and a newer truck. Many banks don’t finance commercial trucks at all.

Specialty truck lenders finance the used trucks banks turn down, with equipment financing solutions built for owner-operators.

SBA Loans

The Small Business Administration guarantees loans made by partner lenders, which helps borrowers get longer terms.

SBA 7(a) loans go up to $5 million, and you can use them to finance equipment (SBA).

SBA 504 loans work through certified development companies. They only cover equipment with at least 10 years of useful life left. That likely rules out most used trucks.

Approval involves a stack of paperwork, so SBA loans suit planned equipment purchases better than quick buys.

Dealer and Manufacturer Financing

Dealers and truck makers often arrange financing at the point of sale. It’s convenient, and new-truck promotions can be hard to beat if your credit is strong.

Compare the dealer’s offer with at least one outside lender before you sign. Mission Financial is a preferred lender for dealerships, so you can often use us through the dealer, too.

Two men shaking hands and smiling in front of a blue semi-truck, one wearing a cap and overalls with a lanyard, the other in a plaid shirt.

What Credit Score Do You Need for Equipment Financing?

There’s no single minimum credit score. Each lender sets its own.

Banks usually want a score above 700, plus two or more years in business. Online lenders go as low as 550.

Some lenders check business credit scores too. If you’ve just formed your LLC, though, lenders usually rely on your personal credit.

We’ve helped owner-operators get loans with credit scores as low as 460. We look at your overall credit, including on-time payments on your home or car. Past bankruptcies and repossessions don’t rule out bad credit truck loans if they’re more than a year old.

Equipment Financing Rates and Down Payments

FreightWaves puts commercial truck loan APRs in 2026 at about 6% to 35%. Well-qualified borrowers pay 4% to 8% at banks and 7% to 12% at specialty lenders.

Specialty lenders offer terms up to 84 months. Trucks over 10 years old with 700,000+ miles get harder to finance, though some lenders go up to 15 years.

Our contract rates run from 18% to 29.95%, with terms up to 42 months. Trucks from 2012 and newer can qualify for 48 months.

Those rates are higher because we approve credit profiles that banks turn down. We also finance trucks as far back as model year 2000.

First-time buyers with us typically put down 20% to 30%.

Rates shift with the market, so check current commercial truck financing rates before you sign. Your term matters just as much, since how long you finance a commercial truck changes your total interest.

Pros and Cons of Trucking Equipment Financing

Financing gets you working equipment without a huge cash outlay, but you pay interest and risk losing the truck.

Close-up of a hand using a desk calculator next to a keyboard to work out monthly payments

Advantages of Financing

  • Keeps working capital free: Your cash stays available for fuel, insurance, and repairs.
  • Builds equity: Every payment brings you closer to owning the truck outright.
  • Easier approval: The equipment secures the loan, so lenders take on less risk.
  • Tax benefits: The tax code’s Section 179 lets you expense up to $2,560,000 of qualifying equipment in 2026 (IRS).

Property acquired after January 19, 2025, can also get 100% bonus depreciation.

With a loan, you can’t deduct the whole monthly payment. You deduct the interest and write off the truck through depreciation or Section 179.

The rules depend on your setup, so talk to a tax professional before you count on a deduction. Our list of truck driver tax deductions covers other write-offs owner-operators can claim.

Potential Challenges and Risks

  • Interest adds up: Higher rates for weaker credit can add thousands to the total cost.
  • Down payment: You’ll still need cash upfront.
  • Depreciation: Trucks lose value, so you can end up owing more than the truck is worth.
  • Personal guarantees: Many lenders make you personally responsible if the business can’t pay.

A personal guarantee puts your personal assets on the line, even if you’ve set up an LLC. An LLC can still protect you from business debts you haven’t guaranteed, so your trucking company’s business structure matters.

How to Apply for Trucking Equipment Financing

Getting your financial documents ready before you shop speeds up approval. Most lenders ask for the same basics:

  • A completed credit application
  • Your CDL
  • Recent bank statements or tax returns
  • A written quote or bill of sale for the equipment
  • A spec sheet with the year, make, model, VIN, and mileage
  • Proof of insurance
  • Your LLC agreement or articles of incorporation (the filing that forms a corporation), if you have them

Some lenders also ask for business licenses or operating authority, like an MC number.

Trucking business owner reviewing paperwork and filling out a financing application at a desk

Final Thoughts

Trucking equipment financing lets you put a truck or trailer to work now and pay for it over time. Compare loans, leases, and SBA options on total cost, along with the monthly payment.

When you’ve found the right truck, start your credit application with Mission Financial.

Frequently Asked Questions

Is Collateral Required for Equipment Financing?

Yes, but the equipment you’re buying usually serves as the collateral. Some lenders ask for other business assets as extra collateral if your credit is weak.

What Is the Minimum Credit Score to Buy a Semi Truck?

It depends on the lender. Banks usually want a score above 700, while Mission Financial Services has approved scores as low as 460.

Can Startups Get Trucking Equipment Financing?

Yes. Many lenders work with a new trucking company, though you’ll likely need a bigger down payment. Mission Financial Services’ first-time buyer loans are built for new owner-operators.

How Long Can You Finance a Commercial Truck?

How Long Can You Finance a Commercial Truck?

A white semi truck pulling a curtain-side trailer drives down a rural highway under a clear blue sky.

Most commercial truck loans run between 24 and 84 months. The exact length depends on the truck’s age, your credit history, and your down payment.

In our experience with owner-operators and small fleets in the trucking industry, the right term isn’t the longest one. It’s about matching the loan to how long the truck will actually earn money.

This guide covers typical loan terms for your trucking business, what stretches them, and how to find the right fit.

TL;DR

  • Commercial truck loan terms typically run 24 to 84 months. Most owner-operators land in the 36 to 72 month range (3 to 6 years).
  • Newer trucks with strong buyer credit can stretch to 84 months. Older or high-mileage trucks usually top out at 60 months.
  • SBA 7(a) loans allow up to 10 years for equipment. Most truck purchases don’t need the full term.
  • Credit score, down payment, truck age, and lender type all affect how long you can finance.
  • Shorter terms cost less overall. Longer terms free up cash flow. The right pick depends on how you plan to use the truck.

How Long Can You Finance a Commercial Truck?

You can typically finance a commercial truck for 24 to 84 months. Banks and credit unions often cap terms around 60 months. Specialty commercial truck lenders regularly extend terms to 72 or 84 months for well-qualified buyers.

Most lenders also weigh whether you’re buying a new semi-truck or a used one before setting your final term.

Where you land in that range depends on the truck and the borrower. A late-model truck with low mileage and a buyer with strong credit supports a longer term. An older, high-mileage truck, or a first-time buyer with thin credit, usually gets a shorter one.

Lenders want the loan to end before the truck’s usable life does.

Rates and terms move together too. Our guide to current commercial truck financing rates breaks down what different credit profiles can expect right now.

Hand holding a fan of hundred-dollar bills for a semi truck loan down payment

What Loan Terms Are Available for Commercial Truck Financing?

Loan terms for commercial trucks fall into three general bands. Each one fits a different buyer: an owner-operator, a growing fleet, or a landscaping company financing its first box truck.

Short-Term Loans: 12 to 36 Months

Short terms suit buyers who want to build equity fast and pay less interest overall. A shorter term also usually comes with a lower interest rate. They’re common for older trucks and smaller loan amounts. Monthly payments run higher, but you own the truck outright much sooner.

Mid-Range Terms: 36 to 72 Months

This is where most owner-operators land. It balances a manageable monthly payment against a total interest cost that doesn’t spiral. Many lenders offer flexible terms in this range, which helps match the payment schedule to seasonal revenue swings.

Mid-range terms work well for used trucks in solid condition and average to good credit.

Extended Terms: 72 to 84 Months

Extended terms are reserved for newer, higher-value trucks and buyers with strong credit and business history. They mean lower monthly payments, but more interest paid over the life of the loan. You may also owe more than the truck is worth for a stretch of the loan.

What Factors Determine Your Commercial Truck Loan Term?

Four things drive how long a lender will let you finance a truck. They are your credit, the truck’s age, your down payment, and your lender type. Together, these four factors shape your financing terms more than anything else.

Your Credit Score and Business History

A stronger credit profile opens the door to longer terms and lower rates.

Traditional banks often want a personal credit score in the high 600s or above. They typically ask for a personal guarantee on top of that. Specialty and alternative lenders will work with scores well below that, sometimes into the 500s. In exchange, they often ask for a shorter term or a bigger down payment.

First-time buyers with limited credit history usually see fewer term options until they build a track record.

Lenders also treat different business entities differently. An LLC with steady business revenue may see better approval odds than a brand-new sole proprietorship.

You’ll typically need to show proof of a commercial driver’s license alongside your application too.

If your credit needs work, approval is still possible. Our guide on bad credit semi-truck financing covers what to expect.

Business owner calculating monthly payments for commercial truck financing

New vs. Used Truck Age

Newer trucks support longer terms. They have more useful life left and hold their value longer. A new semi truck with low mileage will often qualify for the full 84-month window. Newer models frequently deliver better fuel efficiency too and come with a manufacturer warranty.

Used vehicles tend to depreciate faster, so lenders shorten the term accordingly.

Older or higher-mileage units come with shorter available terms since lenders don’t want a loan outlasting the truck’s productive years.

Down Payment Size

A larger down payment lowers the lender’s risk. And it often unlocks a longer term or a better rate.

Down payments on commercial trucks commonly range from 5% to 30% of the purchase price. Good credit borrowers typically fall into the 10 to 15% down payment range.

A used truck with a lower purchase price often needs a smaller down payment in dollar terms. Some lenders will also accept additional collateral, such as a second vehicle, in place of a bigger down payment.

Sales tax, title fees, and other closing costs are usually rolled into the loan rather than paid separately.

First-time buyers usually sit at the higher end of the down payment range.

If putting money down isn’t an option right now, see our breakdown of zero-down semi-truck financing. It offers lower upfront costs in exchange for a higher rate.

Lender Type

Banks tend to offer the lowest rates but the shortest terms and strictest credit rules. Established businesses with years of steady revenue often qualify for the most competitive rates across all lender types.

Specialty commercial truck lenders often stretch terms further and work with a wider range of credit profiles. The truck serves as collateral for the loan, which gives them more flexibility.

Online and alternative lenders sit somewhere in between, trading flexibility for a higher rate.

Truck driver behind the wheel with a model semi truck on the dashboard

Can You Finance a Commercial Truck for Longer Than 84 Months?

Yes, but it’s uncommon outside of SBA financing. An SBA 7(a) loan is designed to help small businesses secure equipment terms up to 10 years. This can include a commercial vehicle used in your business. Most SBA loans also require a personal guarantee from the business owner. These loans involve more paperwork and can slow the approval process significantly. They’re worth a look if you want the lowest possible payment and meet the SBA’s business criteria.

Outside of SBA lending, most conventional and specialty truck lenders cap terms at 84 months. That’s roughly where a truck’s depreciation curve and the loan balance stop lining up. A much longer term risks leaving you owing more than the truck is worth.

Tax treatment matters here too. Under Section 179, businesses can often deduct a truck’s full purchase price in the year it’s placed in service. This beats spreading the deduction across several years, per IRS Publication 946. That upfront tax benefit is worth weighing alongside your loan term. It can help offset the cost of a shorter, higher-payment loan.

Should You Choose a Longer or Shorter Loan Term?

Neither option is automatically better. It depends on your cash flow and how long you plan to keep the truck. It also depends on how much interest you’re willing to pay.

When a Longer Term Makes Sense

Choose a longer term if you need lower payments to protect cash flow for fuel, repairs, and insurance. It also fits if you plan to keep the truck for its full service life. The same goes for multiple trucks financed together during a fleet expansion, since it preserves cash for growth.

When a Shorter Term Makes Sense

Choose a shorter term if your business has steady revenue and you want to build equity fast. It’s also the better fit for an older truck. You don’t want to still owe money on it once major repairs start piling up.

Owner-operator standing with arms crossed in front of his semi truck

Semi Truck Financing vs. Leasing: Which Fits Your Timeline?

Financing turns a commercial vehicle into a long-term asset you own outright. Leasing trades that ownership for lower payments and more flexibility.

If your business needs are still changing, leasing may fit better than a long-term loan. Our guide on whether leasing a semi truck is right for you breaks down the trade-offs.

If you already know you want to keep the truck long-term, financing is usually the more cost-effective route.

How To Choose the Right Loan Term for Your Truck

Start with your monthly budget. Look at what you can comfortably pay after fuel, insurance, maintenance, and permits, and work backward from there.

Then think about how long the truck will realistically stay productive in your operation. A term that outlasts the truck’s useful life tends to cause problems later, even when the payment looks manageable today. Ask your lender for a full payment schedule and check for prepayment penalties before you sign.

We’ve found that borrowers who compare the annual percentage rate, not just the sticker rate, end up with better financing. A shorter term with a higher payment can still cost less than a longer one that looks easier on paper.

The best term is the one that fits your financial situation today, not just the truck’s price tag.

Ready to Find Your Loan Term?

We know every borrower’s situation looks a little different. The truck, the credit profile, and the down payment all pull your loan term in different directions.

Finding the right financing means matching your loan term to your truck and your business, not the lowest payment alone.

Our team at Mission Financial Services can pull your options together fast. We’ll walk you through the trade-offs in plain language. Then we’ll help you land on financing that actually fits your business, not just your budget.

Frequently Asked Questions

What is the average commercial truck loan term?

Most commercial truck loans run 36 to 72 months. Newer trucks and stronger credit can extend that to 84 months. Older or high-mileage trucks often max out at 60 months or less.

Can I get a 10-year loan for a semi-truck?

It’s possible through an SBA 7(a) equipment loan, which allows terms up to 10 years. A standard semi-truck loan through a bank or specialty lender rarely stretches past 84 months.

Does a bigger down payment get me a longer loan term?

It can. A larger down payment lowers the lender’s risk. That sometimes opens the door to a longer term or a better rate, especially on an older or higher-mileage truck.

Parts & Labor Costs Up 27% Since 2019: Why Fleet Financing Has to Be Part of Your Maintenance Strategy

Parts & Labor Costs Up 27% Since 2019: Why Fleet Financing Has to Be Part of Your Maintenance Strategy

Potential Semi Truck Buyer

Combined truck parts and labor expenses have surged across the trucking industry over the last several years. Combined fleet maintenance costs increased 27.4% between 2020 and 2025, while labor expenses alone jumped 33.5%.

For owner-operators and small fleets, maintenance is no longer just a repair problem. It has become a cash flow problem, a downtime problem, and increasingly, a financing problem.

Running older trucks longer used to look like the cheaper option. Today, rising labor rates, expensive parts, technician shortages, and repeated breakdowns are changing things.

That shift is forcing many operators to rethink the relationship between maintenance and financing. In many situations, financing newer equipment may create less operational risk than continuing to run aging trucks into the ground.

Fleet Maintenance Costs Are Rising Faster Than Many Fleets Expected

The latest Decisiv/TMC benchmarking data shows how aggressively fleet maintenance costs have climbed across the industry.

Between 2020 and 2025:

  • Combined parts and labor costs increased 27.4%
  • Labor costs rose 33.5%
  • Parts costs climbed 23.8%

Several major repair categories saw especially sharp increases:

  • Cab and sheet metal costs rose nearly 64%
  • Rear axle repair costs increased 20.6%
  • Wheels, hubs, and bearings climbed 15.5%
  • Filter kit costs rose another 11.9%

Those increases affect nearly every type of fleet vehicle, from long-haul sleepers to vocational equipment and regional delivery trucks.

Even fleets with strong preventive maintenance programs are struggling to control rising maintenance expenses because pricing pressure now affects labor, parts sourcing, diagnostics, and downtime simultaneously.

For small fleets operating with tighter margins, those higher costs add pressure quickly.

Truck drivers handshaking making business agreement

Fleet Management Cost Analysis: Why Repair Bills Are Climbing Across The Industry

Several operational pressures are driving higher repair invoices across trucking.

Technician Shortages Are Driving Labor Costs Higher

Qualified diesel technicians remain difficult to recruit across much of the country. Shops are paying higher wages to attract experienced technicians, which pushes hourly labor rates higher for fleets and owner-operators.

At the same time, many repair facilities are dealing with scheduling backlogs that keep trucks parked longer before work even begins.

That downtime compounds expenses fast.

A truck sitting for four days waiting on diagnostics still generates insurance costs, truck payments, permit obligations, and lost revenue. For smaller operations, every parked truck immediately affects cash flow and dispatch capacity.

Parts Inflation Has Become a Major Problem

Parts inflation now drives a large share of rising maintenance costs across commercial trucking. The issue extends far beyond major engine failures.

Several factors continue pushing repair invoices higher at the same time, including supply chain disruptions, tariffs, and labor availability.

Fleets are seeing higher pricing across:

  • Rear axle components
  • Bearings and hubs
  • Brake systems
  • Air compressor components
  • Cooling systems
  • Filter systems
  • Electrical components

For aging semi trucks, those costs stack quickly because older equipment often needs repairs across multiple systems at once instead of isolated component replacements.

Aging Semi Trucks Require More High-Dollar Repairs

As heavy-duty trucks accumulate mileage, they often transition from predictable service intervals into expensive component failures.

That’s when fleets begin dealing with repeated repairs involving:

  • Diesel Particulate Filter (DPF) systems
  • Selective Catalytic Reduction (SCR) systems
  • Turbochargers
  • Cooling failures
  • Electrical diagnostics
  • Transmission work
  • Emissions-related sensors

The issue usually isn’t one catastrophic repair. Instead, fleets often enter a cycle where trucks require repeated high-dollar repairs every few months. One quarter may involve turbocharger work. The next may involve emissions diagnostics, wheel-end repairs, or cooling system failures.

At that point, maintenance spending becomes increasingly expensive long-term and much harder to forecast accurately.

Trucker New Purchase

Why Maintenance Strategy Is Now a Financing Decision

Many trucking businesses used to separate maintenance planning from capital planning. The old mindset was just to keep the truck running as long as possible.

But today, rising fleet maintenance costs are making operators ask a different question: At what point does repair volatility become more expensive than replacement financing?

And that is changing how fleets evaluate equipment ownership.

A stronger fleet management cost analysis can help fleet managers understand whether they’re actually reducing operating expenses or simply delaying larger repair bills.

For many small operations, financing newer equipment can help:

  • Reduce catastrophic repair exposure
  • Improve uptime consistency
  • Stabilize monthly operating costs
  • Reduce emergency cash drain
  • Improve reliability
  • Reduce downtime risk
  • Support long-term business growth

Predictable monthly payments are often easier to manage than unpredictable repair spikes.

A financed truck with stable operating performance may create less financial risk than an older paid-off truck generating repeated $8,000 to $15,000 repair events throughout the year.

The Hidden Cost of Running Older Trucks Too Long

Repair invoices rarely show the full operational impact of aging equipment. Older trucks can look cheaper because they’re paid off, but repeated downtime and unpredictable scheduling can erase those savings fast.

Here’s how:

  • Downtime can cost more than the repair itself: Missed loads, tow bills, hotel expenses, rental equipment, driver disruptions, delayed delivery schedules, and lost customer confidence can all hit at once. For small fleets, even one parked truck can hurt weekly revenue and dispatch efficiency.
  • Emergency repairs usually cost more: Breakdowns rarely happen at convenient times. Fleets may face rush parts sourcing, higher rates from repair shops, roadside service premiums, secondary component damage, and expedited towing costs.
  • Unplanned repairs make it harder to reduce costs: It’s easier to schedule maintenance than react to a truck that fails mid-route. Planned work gives owners more control over timing, parts, and shop availability.
  • Older trucks don’t always save money: A paid-off truck may still become expensive if it keeps generating repair bills, downtime, and lost revenue. At a certain point, replacing equipment can help owners save money without sacrificing quality or reliability.
  • Repair volatility makes financial planning harder: Large repair spikes can disrupt payroll timing, fuel purchasing, insurance payments, expansion plans, working capital, and driver scheduling. That volatility creates stress for small businesses trying to protect uptime and customer relationships.

How Small Fleets Should Evaluate Repair Costs vs Replacement Costs

Replacement decisions should rely on operational data, not emotion or habit.

Fleet owners should evaluate:

  • Monthly repair spend per truck
  • Downtime frequency
  • Cost per mile
  • Revenue lost during repairs
  • Maintenance trends over 12 months
  • Repeat repair patterns

Fleets using fleet management software or internal maintenance data can track repairs by mileage, downtime, and vehicle wear, so decisions are based on actual operating trends instead of guesswork.

For example, a truck generating multiple large repair events annually may cost more operationally than replacing the equipment with newer, financed models.

new modern truck in the parking lot of the dealership. Heavy Duty Transportation and Automotive Industry Theme

Signs Your Fleet May Be Reaching A Replacement Point

At a certain point, the truck stops functioning like a productive business asset and starts operating like a financial liability.

Common warning signs include:

  • Repairs are becoming more frequent
  • Major systems are failing repeatedly
  • Downtime is hurting customer relationships
  • Drivers are losing confidence in the equipment
  • Parts delays extend repair timelines
  • Maintenance spending is becoming unpredictable
  • Driver behavior and mileage trends are increasing repair frequency

How To Prepare Financially Before Replacing Equipment

Before replacing equipment, look beyond the latest repair invoice and evaluate the bigger operating picture.

Review repair frequency, average monthly maintenance spend, downtime patterns, cost-per-mile trends, and how often trucks are sitting instead of generating revenue. A truck that constantly needs repairs may quietly drain profitability even if it’s fully paid off.

Build a full operating budget, not just a payment estimate. Include

  • Fuel
  • Insurance
  • Maintenance reserves
  • Driver pay
  • Loan payments
  • Registration costs
  • Compliance expenses
  • Fixed costs like taxes and permits

Breaking expenses into fixed and variable categories helps fleets understand the true total cost of ownership and identify where they might be able to reduce expenses before financing another truck.

It’s also smart to organize financing documents early. Buyers who prepare ahead of time usually have more flexibility when the right truck becomes available.

Mission Financial Services helps owner-operators and small fleets approach replacement decisions strategically, not reactively.

Whether you’re trying to replace unreliable equipment, protect cash flow from escalating repair bills, or expand without overextending your business, we can help you with financing options that support long-term operational stability.

New trucks for sale

Conclusion

Rising fleet maintenance costs are no longer a slow-moving industry trend. They have become a major operational pressure point for fleets of every size.

Higher labor rates, expensive parts, technician shortages, and growing downtime are forcing trucking businesses to rethink how long aging equipment should remain on the road.

For many owner-operators and small fleets, financing newer equipment isn’t simply about adding trucks. It’s about improving reliability, protecting cash flow, reducing downtime exposure, and creating more predictable operating costs.

At Mission Financial Services, we know you only make money when your trucks are on the road.

If repair bills keep cutting into your cash flow, we can help you look at financing options for repairs or fleet growth, even if your credit history isn’t perfect.

Start your credit application today and get one step closer to a truck that works as hard as you do.

Archives

Sign Me Up!

Stay up to date with the latest news in the commercial trucking industry.

Contact Us
close slider