Office: (404) 975-4800

Uncategorized

report bad driving

Reporting A Semi Truck Driver

report bad driving
Have you ever witnessed truck drivers driving unsafely and wondered if there was anything you could do to stop them? Well, you can report their unsafe driving to relevant authorities so they can address the issue before it’s too late.

Unsafe truck drivers put all road users at risk of severe injuries or death from fatal accidents. The Federal Motor Carrier Safety Administration (FMCSA) and other state bodies provide several avenues to report such dangerous truck drivers and minimize these risks.

Learn how to report a semi-truck driver effectively below and help promote road safety.

Why You Should Report Unsafe Driving

Truck accidents have become increasingly common across the U.S. as their numbers continue to increase annually. In 2021, for instance, there were over half a million (523,796) truck accidents, up from 415,444 incidents the previous year.

FMCSA, in one of their truck crash causation studies, cites driver-related errors as the top cause of most truck accidents.

By reporting unsafe truck drivers, you alert the relevant authorities to conduct an investigation and address the issue before the dangerous truck driver causes an accident and injures people. Reporting unsafe truck drivers ensures our roads stay safe for everyone.
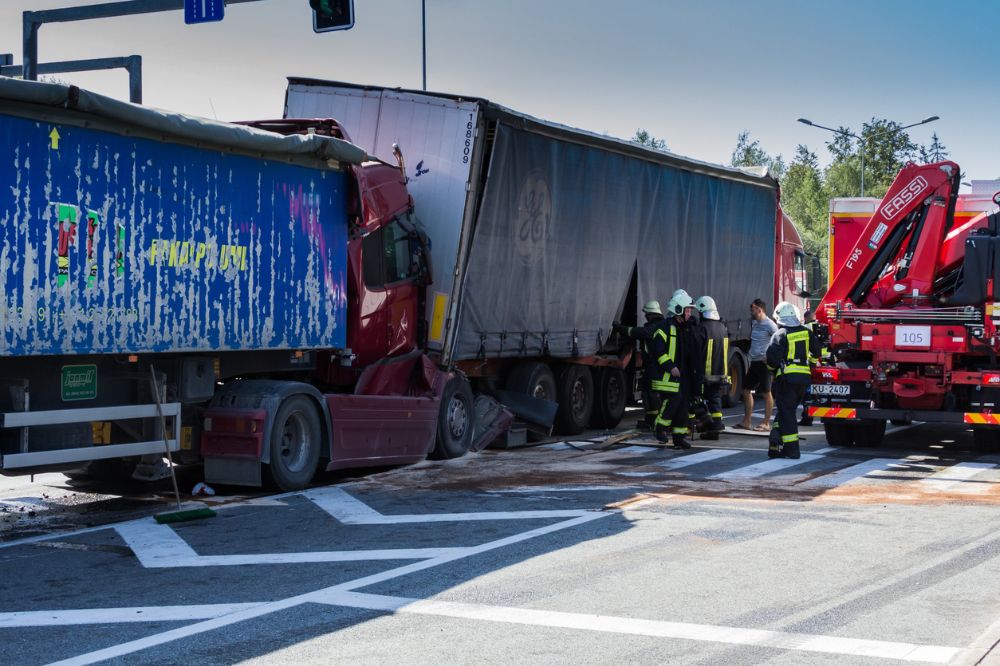
truck accident

Unsafe Truck Driving Practices

A reckless driver violates road regulations willfully, disregarding their safety and the safety of other drivers. Such erratic behavior almost always leads to fatal accidents that cause catastrophic injuries. Some dangerous truck driving behaviors you should take note of and report include the following:

Illegal Passing

Large trucks limit on-road visibility for other drivers due to their large size. Because of this, transportation rules in most states prohibit professional drivers from passing on a curve, hill, and on the right.

Illegal passing happens when semi-truck drivers violate these regulations, limiting visibility for other drivers who require clear sight lines to avoid accidents. This unsafe driving behavior often leads to a semi-truck running other vehicles off the road.

Speeding

Some truck drivers drive too fast when trying to meet their demanding pick-up and drop-off schedules. Statistics from the Federal Highway Administration (FHA) reveal that speeding truckers often cause serious accidents that lead to fatalities because of increased forceful impact during a collision.

Failing to Yield

Most trucks don’t have the right of way. If you observe a semi-truck driver failing to yield to other drivers, report them as they’re likely to cause dangerous head-on and T-bone collisions.

Swerving

In most cases, swerving is a sign of an underlying problem that might affect the driver’s ability to control their vehicle, leading to a truck crash. The driver might be distracted, under the influence, or experiencing a medical emergency. It’s best to report such cases as emergencies (more on how to do this below).
speeding truck

Following Too Closely

Trucks require long distances and time to stop. Semi-truck drivers who follow other vehicles too closely can cause rear-end collisions, especially during heavy traffic and bad weather.

Camping in the Left Lane

Most states ban slow vehicles from using left lanes as their default driving lane on interstate or multi-lane highways. The left lanes are mostly for passing. Camping in the left lane, therefore, is a safety violation.

It’s an unsafe driving practice that forces vehicles to pass large trucks on the right side, where there are massive blind spots. This increases the chances of accidents occurring.

Where to Make a Report

If a truck driver’s unsafe behavior behind the wheel puts other road users in immediate danger, call 911 and report an emergency. Life-threatening driving behavior, such as swerving, counts as an emergency. The police will intercept the truck before an accident occurs.

For non-emergency cases, there are a few options for reporting an unsafe driver’s conduct, depending on your location and circumstances. Some of these include:

File a Complaint With the FMCSA

Reporting safety violations to the FMCSA is a highly effective method for maintaining road safety. The FMCSA investigates each complaint, penalizes the involved parties, and records them in the national consumer complaint database.

These complaints become a permanent part of a trucking company’s driving record, prompting companies to take necessary measures to ensure safe driving and avoid reputational damage or severe penalties.

Contact FMCSA by calling 1-888-DOT-SAFT (1-888-368-7238) or fill out their consumer safety violation complaint form if you’ve witnessed unsafe driving behaviors on an interstate highway.
highway patrol

Contact the Highway Patrol

To report unsafe truck drivers on intrastate roads, file a complaint with the state’s Department of Transportation, highway patrol office, or the Public Utilities Commission. These agencies oversee the safety of roads within each state and can respond quickly to prevent truck crashes.

Provide relevant information to support your complaint, including any distinguishing characteristics of the unsafe driver and vehicle, as explained below.

Report Them to Their Employer

Most trucking companies provide a phone number you can call to report any commercial vehicle driver operating their trucks unsafely. You’ll almost always find this number on the conspicuous ‘How’s my driving’ sticker at the back of many commercial trucks.

You can also email the safety director of a trucking company explaining the unsafe driving practice along with other relevant details. A responsible trucking company will appreciate your report and evaluate the truck driver to see whether they’re fit to remain behind the wheel.

What Information To Report

Your report about an unsafe driver should include specific information relevant authorities can use to conduct an investigation, such as:

  • The location where you witnessed the road safety violations. Specify whether the road is intra- or inter-state, its name or number, plus any cross streets, mile markers, road signs, intersections, and exits relevant authorities can use to pinpoint the location.
  • A detailed description of the truck and the driver – providing any stand-out characteristics, like vehicle make and color, helps a lot
  • Identifying information about the trucking company, such as the company name and logo
  • License plate number plus the Department of Transportation (DOT) number
  • The time and date of your observation
  • An explanation of the unsafe behavior

call 911

How Do You Report a Trucking Company Anonymously?

Reporting a trucking company that encourages unsafe driving among its employees is similar to reporting an individual truck driver. You use the same channels and follow the same procedures we’ve discussed.

The only difference is – you’ll have to specify why you think the trucking company allows or supports unsafe driving practices as opposed to it being an individual trucker’s poor driving habit. Have you seen most of the company’s trucks speeding past your home repeatedly despite being driven by different drivers?

Some people fear harassment or retaliation by the trucking company and might not want to go to court or actively participate in any investigations. In this case, you can make an anonymous complaint, although it might be harder to investigate.

You have every right to withhold your name and other personal details when calling in a complaint. You can also omit your personal info when filling out a complaint form and use the ‘anonymous’ tag where your name is mandatory.

Avoid providing false identification info, as this counts as a crime. Sending a letter providing the necessary details only to the relevant authority also helps to hide your identity.

Final Thoughts

When you notice an unsafe truck driver, keep yourself safe first. Drive away from the dangerous driver, and avoid tailgating, speeding up, or engaging in unsafe driving behaviors while trying to collect information to make your complaint.

You can also report unsafe driving by a trucker to a truck accident lawyer, if you or your loved ones get injured in a truck accident. The right truck accident lawyer will help you get maximum compensation for medical bills, lost wages, and all other damages sustained.

We’ve prepared several guides to help you understand how to handle a truck accident and find the most competent truck accident lawyers afterward. Check out our blog to learn more about this.
semi truck owner (1)

How To Be A Successful Semi Truck Owner Operator

semi truck owner (1)

Running your own trucking business may be a dream. However, there’s a lot that goes into being a successful semi truck owner-operator, and it’s essential that you know all the different elements involved in managing a business.

Follow this guide to learn some of the most important tactics and responsibilities that owner-operators should show.
What is an Owner-Operator?
An owner-operator is an individual who owns and operates their own trucking business.

Instead of working as an employee for a trucking company, an owner-operator owns the truck they drive and may either work independently or lease their services to carriers or logistics companies.

A successful owner-operator is responsible for managing their truck, handling maintenance costs, fuel expenses, insurance, and other overheads associated with running a trucking business.

Owner-operators can choose their routes and schedules and sometimes negotiate their compensation rates.

Tips to Becoming a Successful Owner-Operator

If you own a semi-truck, then establishing a successful owner-operator business is undoubtedly appealing. Here are a few essential tips for truck owner-operators to keep in mind.

Ensure You Have Enough Experience

Gaining experience is crucial before transitioning into an owner-operator role within the trucking industry.

Working as a truck driver provides invaluable knowledge about the nuances of the job, from managing different cargo types to understanding diverse routes and handling various situations on the road.

Acquiring hands-on experience also familiarizes individuals with different equipment, truck maintenance, industry regulations, and the administrative aspects of the business. You’ll probably also need to hold and use your commercial driver’s license for some time to help you get better rates on truck financing and commercial insurance.

Create a Business Plan

Crafting a comprehensive business plan is essential to the success of any owner-operator business.

This plan should outline your business goals in detail. This might involve expanding a fleet, specializing in certain cargo types, or targeting specific geographic areas.

It’s crucial also to perform thorough market research, identify your target audience, study your competitors, and pinpoint your unique selling propositions. Within your business plan, include a detailed financial strategy.

business plan

Assess Your Finances

Understanding your costs is an essential step in starting any kind of business. As you’ll be running your own truck and operating your own business, all costs involved are your responsibility.

Your financial evaluation should cover startup costs, including the purchase or lease of a truck, insurance, permits, and licenses. Understanding ongoing expenses such as fuel, maintenance, repairs, and taxes is also crucial.

Distinguishing between fixed costs (insurance, truck payments) and variable costs (fuel, maintenance) is essential for gaining a clear picture of the financial health of your business.

You’ll need to realistically understand your finances and know how to track them in order to run a successful owner-operator business.

Understand Freight Cycles

A comprehensive understanding of freight cycles for commercial motor vehicles is vital for your operational success.

Study seasonal trends and industry cycles to help anticipate busy and slow periods in freight demand.

You’ll want to diversify your client base or adapt your services during slower periods to maintain consistent income. During peak seasons, you can develop strategies to capitalize on increased demand by efficiently planning routes and securing higher-paying contracts.

Know How to Generate Revenue

Owner-operators can make money in the trucking industry in a couple of different ways.

Explore different types of commercial trucking opportunities such as load boards, freight brokers, direct contracts with shippers, or participation in dedicated freight programs offered by larger companies. Building a solid network within the industry is also crucial for securing repeat business and referrals.

credit score

Have a Maintenance Reserve

Being a small business owner can be expensive – especially when you have to maintain a commercial truck.

Make sure that you allocate funds for truck maintenance and unexpected repairs. By setting aside a portion of earnings into a designated maintenance reserve, unexpected breakdowns, and repairs can be managed without causing financial strain or disrupting business operations.

Regularly scheduled preventive maintenance helps avoid costly breakdowns and extends the lifespan of your equipment, ensuring continued smooth operations.

Protect Your Credit

Maintaining strong credit is a vital element of your owner-operator career.

Ask other owner-operators, and they’ll tell you that good credit is so much more than just a way to help your cash flow; it’s a way to manage your business.

Timely bill payments, responsible debt management, and regular monitoring of credit reports help you achieve a good credit score. A good credit score opens up better financing options, lower interest rates on loans, and increased credibility when negotiating contracts or leases.

Create Your Own Schedule

The flexibility of being an owner-operator means you can create personalized schedules that maximize productivity.

Effective route planning, workload balancing, and rest period management are essential for running a trucking operation.

deals

Negotiate Your Own Deals

Developing strong negotiation skills is essential for owner-operators to secure the rates, terms, and contracts they want.

Understanding market rates, industry standards, and the value of services helps you confidently manage negotiations. Building strong relationships while negotiating fosters mutually beneficial agreements that prioritize long-term partnerships and profitability.

This is essential for a successful owner-operator business.

Final Thoughts

If you own and operate your commercial truck, you must have solid business management skills and trucking abilities. Follow the tips above, and you’ll be in an excellent position to manage a successful business.

If you want to purchase a semi-truck, you’ll need to gain the right financing. Get in touch with us at Mission Financial Services to make acquiring financing an easy process.

truck leasing

Comprehensive Guide To Commercial Truck Leasing in 2026

truck leasing

There are two main ways to get a commercial truck: buying one or leasing one.

Commercial truck leasing comes with lower upfront costs. And it cuts out a lot of the risk that comes with owning a truck outright. Still, leasing has trade-offs that catch plenty of owner-operators off guard.

In our experience, the leasing decision usually comes down to cash flow. It also depends on how long you actually need the truck.

This guide covers the lease types and the real costs. We’ll also walk through the questions worth asking before you sign anything.

What Is Commercial Truck Leasing?

Commercial truck leasing means renting a truck for a set period instead of buying it outright. You sign a contract between the lessee, the one using the truck, and the lessor, who owns or leases out the truck.

Under most leases, you pay a monthly fee to use the truck for an agreed period. The contract usually covers maintenance duties, mileage caps, insurance requirements, and penalties for excess wear and tear.

Most commercial leases fall into one of three categories.

Full-Service Leasing

This type of lease covers most of the costs tied to running the truck. That includes maintenance, repairs, insurance, and sometimes registration fees. It’s a solid fit if you want to minimize downtime and keep monthly costs predictable.

Finance Lease

Also called a capital lease, this option works more like a loan. The lessee takes on most ownership responsibilities, like maintenance and insurance. The truck still stays titled to the lessor.

Operating Lease

An operating lease is short-term, and the lessee doesn’t take on the risks tied to ownership. This structure makes it easier to upgrade to a newer truck once the term ends.

Closed-End vs Open-End Leases

Beyond the lease type, you’ll also run into closed-end and open-end structures. Each one handles the truck’s end-of-term value a little differently.

Closed-End Leases

A closed-end lease is often called a walk-away lease. The leasing company sets the truck’s residual value up front. You simply turn the truck in once the term ends.

Mileage limits typically run between 12,000 and 15,000 miles a year. You’ll pay extra for any miles or wear and tear above that.

Open-End Leases

With an open-end lease, you and the leasing company agree on a residual value together. You carry the risk if the truck’s actual value comes in lower at lease-end.

A Terminal Rental Adjustment Clause (TRAC) lease is the most common example in commercial trucking. If the truck sells for more than the residual, you get the difference back. If it sells for less, you cover the gap.

truck lease agreement

Essential Elements of a Commercial Truck Lease

Lease agreements vary widely, but a solid contract should spell out a handful of things before you sign anything. Here’s what we always tell drivers to check for.

  • Identification of parties: Name both the lessor and the lessee clearly.
  • Description of the truck: List the make, model, year, VIN, and any added equipment.
  • Lease term: Look for a clear start date, end date, and total length.
  • Payment terms: This covers the monthly amount, due dates, and any late fees.
  • Maintenance and repairs: State who handles preventive maintenance, repairs, and related costs.
  • Usage restrictions: Mileage limits, geographic restrictions, and prohibited uses should be clear.
  • Return conditions: This covers the truck’s required condition at turn-in, plus excess wear-and-tear charges.
  • Insurance requirements: Most interstate carriers need at least $750,000 in liability coverage under the FMCSA’s minimum financial responsibility rules. Your lease should spell out what’s required on top of that.
  • Early termination or buyout options: Check whether you can end the lease early. Also confirm what it costs to buy the truck at the end of the term.

Key Leasing Terms To Know

Lease contracts come loaded with industry jargon. Knowing these terms ahead of time helps you avoid surprises at signing.

  • Acquisition fee: Covers admin costs like credit checks and paperwork. Also called a bank fee.
  • Capitalized cost (cap cost): The truck’s agreed value at lease start, plus taxes and fees.
  • Residual value: The truck’s projected value at lease-end, used to set your monthly payment.
  • Money factor: A decimal some lessors use to calculate the interest portion of your payment.
  • Disposition fee: Covers the cost of prepping and selling the truck if you turn it in.
  • Security deposit: An upfront amount some lessors require at the start of the lease. It’s typically refundable at the end of the term, provided you’ve met all the contract conditions.

Leasing vs Purchasing: Which Makes Sense?

Should you lease or buy? Each option comes with real trade-offs. Leasing offers several clear benefits: lower upfront costs, predictable monthly payments, and easier access to newer trucks. You don’t build equity, though, and the long-term costs can add up fast.

Buying involves a bigger upfront investment, but you walk away owning a real asset. You also take on the full maintenance bill and the risk of depreciation hitting resale value down the road. Some owner-operators finance the purchase through an SBA-backed equipment loan instead of a conventional bank loan. This can soften the upfront cash requirement.

We’ve seen plenty of owner-operators choose ownership once they have the credit history and down payment to make it work. Leasing still has its place, especially for substitute vehicles or short-term contracts that keep a fleet running.

truck inspection

Commercial Truck Lease Pros and Cons:

Pros

  • Lower initial costs, sometimes with no down payment required
  • More predictable monthly payments
  • Lease payments may be tax-deductible as a business expense
  • Some leases bundle in maintenance coverage
  • Easier access to newer truck models once the term ends
  • On-time lease payments can strengthen your business credit history, which makes it easier to qualify for loans down the road
  • Full-service leases let you focus on hauling rather than managing maintenance logistics

Cons

  • You don’t build ownership equity in the truck
  • Mileage limits and usage restrictions are common
  • Long-term leasing costs can exceed the cost of ownership

The Lease-to-Own Option

Some leasing companies offer a lease-to-own arrangement, where a portion of each monthly payment goes toward the truck’s purchase price. At the end of the term, you make one final lump-sum payment to own it outright.

This is a useful path for drivers who want to build toward ownership. It avoids taking on the full purchase cost from day one.

It’s worth asking any lessor whether a lease-to-own option is available before you commit to a standard lease.

Costs To Consider When Leasing Commercial Trucks

Leasing a commercial truck comes with several layers of cost beyond the headline monthly payment. Here’s a breakdown of what to expect.

  • Monthly lease payments: This is the main cost, and it varies based on lease type, truck model, and term length.
  • Down payment or initial fees: Some leases require a security deposit or first month’s payment up front.
  • Maintenance and repairs: Depending on your lease type, you might cover these separately or have them bundled into your payment. Keeping up with the maintenance schedule is also tied directly to the truck’s performance, and most lessors will charge penalties at turn-in if it’s been neglected.
  • Insurance: Lessees typically need their own commercial truck insurance coverage to protect their business and meet the coverage minimums the lessor requires.
  • Excess mileage or usage fees: Going over your mileage cap usually triggers a per-mile charge.
  • Taxes and fees: Expect registration costs and administrative fees layered on top of your payment.
  • Early termination fees: Ending a lease early often comes with a penalty.

Estimating Your Fuel Costs

Fuel is one of the biggest variable costs tied to any leased truck. You can estimate it with a simple formula.

Divide your planned mileage by your truck’s fuel efficiency, then multiply by the current price per gallon.

truck lease pros and cons

Is Leasing the Right Fit for Your Operation?

Leasing tends to make the most sense for short-term needs. Think covering a temporary contract, testing a new route, or keeping a backup truck running when customers are counting on your schedule. It can also help newer operators who don’t yet have the credit history or down payment for a purchase.

That said, there are situations where leasing works against you. Watch out for these scenarios.

  • You run high mileage: Most commercial truck leases cap annual miles between 10,000 and 15,000. If your routes regularly push past that, overage charges can wipe out the cost advantage of leasing.
  • You haul hazmat: Some lessors won’t take on the risk. Hazmat operations often limit your pool of willing lessors significantly.
  • You need to hold the title: Certain regulatory requirements, contracts, or tax incentives require you to own the vehicle outright. A leased truck won’t qualify in those situations.
  • You operate mostly off-highway: Heavy off-road use can take vehicles outside what most lessors will accept for their fleet.

Buying usually wins out for drivers who plan to keep the same truck for years. It also makes sense if you run heavy mileage or want equity to borrow against later. If you’re scaling from one truck to a small fleet, compare lease terms against financing options built for fleet growth.

What Lessors Look For

Qualifying for a commercial truck lease works similarly to qualifying for a loan. Lessors typically review your personal and business credit scores. They also look at how long your business has been operating and whether you can show steady revenue.

Drivers with lower credit scores can still get approved, though the terms will vary. If your credit is thin or damaged, a standard lease may not be your best option. A financing option designed for owner-operators often gives you more flexibility.

Questions To Ask Before You Sign a Lease

Before signing anything, run through these questions with the leasing company.

  • What are the mileage limits, and what’s the exact overage charge per mile?
  • What are the turn-in conditions, and how is “normal wear and tear” defined?
  • What happens if you can’t meet the payment terms?
  • What’s the full price of the truck, including any ancillary services?
  • Are there hidden fees, and what exactly do they cover?
  • Is a lease-to-own option available, and what are the buyout terms?

costs

Final Thoughts

Leasing a truck can look appealing on the surface. In our experience, ownership usually pencils out better for drivers who keep running the same routes for years. Affordable vehicle financing makes purchasing a commercial truck a realistic option, even for first-time buyers or drivers rebuilding their credit.

Get in touch with Mission Financial Services to find the right funding for your next truck

Hotshot Commercial Truck Insurance

Hotshot Commercial Truck Insurance

hotshot

Many different types of trucking businesses exist – with hotshot trucking being a popular area.

As this is a unique type of trucking, it comes with its specialized insurance requirements. This is why hotshot trucking operators need the right insurance policy that matches their business needs and operations.

If you only offer hotshot trucking services, taking out a regular commercial trucking insurance policy could waste money.

To help you out, here are some of the critical things you need to know about hotshot commercial truck insurance.

What is Hot Shot Trucking?

Hot shot trucking is a trucking and delivery service that involves transporting relatively small, time-sensitive loads. With hot shot trucking, you use smaller trucks, typically one-ton or medium-duty trucks. These are classified as less-than-truckload (LTL) vehicles.

Unlike traditional freight services that use large semi-trucks or tractor-trailers, hot shot trucking utilizes smaller vehicles that can quickly transport goods and cargo to their destination.

Hot shot trucking can cater to various industries, including oil and gas, construction, agriculture, and manufacturing, where the fast delivery of smaller loads is necessary.

The advantage of hot shot trucking is faster delivery times and more personalized service compared to larger freight carriers. This niche transportation service is valuable for its flexibility, speed, and quick response to time-sensitive transport needs.

Who Needs Hotshot Trucking Insurance?

Hotshot trucking insurance is essential for anyone who offers this trucking service.

This insurance is essential for owner-operators running smaller trucks or small trucking companies specializing in rapid delivery. Freelance drivers offering on-demand services may also need a hotshot trucking insurance policy.

Hotshot truckers require specialized insurance coverage to protect against liabilities, cargo damage, and unforeseen incidents on the road.

Getting the right hotshot trucking insurance provides financial protection and peace of mind for the transporter and their clients in the event of accidents or mishaps during transit.

Hot Shot Trucking Coverage

Hotshot trucking insurance refers to commercial trucking insurance that can be applied to specialized hotshot truckers. Coverage can include:

  • Liability Insurance: Covers bodily injury or property damage liabilities arising from accidents while operating the truck.
  • Comprehensive Insurance: Protects against non-collision incidents like theft, vandalism, or natural disasters.
  • Collision Insurance: Covers damages to the truck resulting from collisions.
  • Cargo Insurance: Protects the value of the cargo being transported against damage, loss, or theft during transit.
  • Loading and Unloading Insurance: Covers liabilities during loading or unloading cargo.
  • Towing and Storage Insurance: Covers costs related to towing and storing the truck in case of breakdowns or accidents.
  • Bobtail Coverage Insurance: Covers the truck when operated without a trailer, such as when driving back to the home base.
  • Downtime Insurance: Provides coverage for income lost due to downtime resulting from accidents or covered incidents.
  • Earned Freight Insurance: Covers the income lost if the cargo can’t be delivered due to a covered incident.
  • Equipment Coverage: Protects additional equipment used for transportation, such as trailers, chains, and tarps.
  • Debris Removal Insurance: Covers costs associated with the removal of debris resulting from covered incidents.
  • Broadened Pollution Insurance: Covers liabilities for environmental damage caused by hazardous material spills during transit.
  • Loss Mitigation Insurance: Covers expenses incurred to prevent further damage or loss after an incident occurs.
  • Medical Payments Insurance: Covers medical expenses for injuries sustained by the driver or passengers in the truck.
  • Family Emergency Expenses Insurance: Provides coverage for emergency expenses incurred by the driver’s family due to a covered incident.
  • GAP Coverage: This covers the difference between the truck’s actual cash value and the amount still owed on a lease or loan in the event of a total loss.
  • Umbrella Insurance: Provides additional liability coverage beyond the limits of primary insurance policies.

Cost of Hotshot Trucking Insurance

The cost of hotshot trucking insurance policies varies based on a range of factors.

Most importantly, your premiums depend on what types of coverage you have. The more comprehensive coverage your policy offers, the more expensive your insurance will be.

The following factors can also affect how much your insurance policy costs:

  • Type of equipment being covered
  • Coverage limits
  • Driving history
  • Cargo
  • Location
  • Deductibles

The bottom line is the more you need to be covered, the more expensive your policy will be.

Lowering the Cost of Hotshot Insurance

Want to get the best deal on hotshot trucking insurance? It’s possible to lower the cost of your premiums by:

  • Comparing quotes to see which company offers the best deal
  • Increase deductibles to lower your monthly premiums
  • Get only essential cover to reduce how much you pay

If you want to purchase hotshot insurance on a budget, only cover the essentials. This could add risks over the long run, but it will decrease your monthly premiums.

find insurance

How to Find Hot Shot Insurance Cover

Contact insurance companies specializing in commercial trucking or freight transportation and ask if they offer any specialized hotshot insurance options. Request quotes tailored to your specific needs and the nature of your hot-shot trucking business.

Comparing multiple quotes and understanding the details of coverage options will help you choose the most suitable insurance broker for your operations.

Final Thoughts

The right commercial truck insurance policy is essential for the smooth operation of any trucking business. Make sure you compare quotes and understand exactly what coverage options you have. Choosing the right policy can make a significant impact on your business.

If you’re in the hotshot trucking business, you must acquire the right vehicle. At Mission Financial Services, we make it easy for owner-operators to access the financing they need to purchase a commercial truck. Get in touch with us to see how easy the application process is.

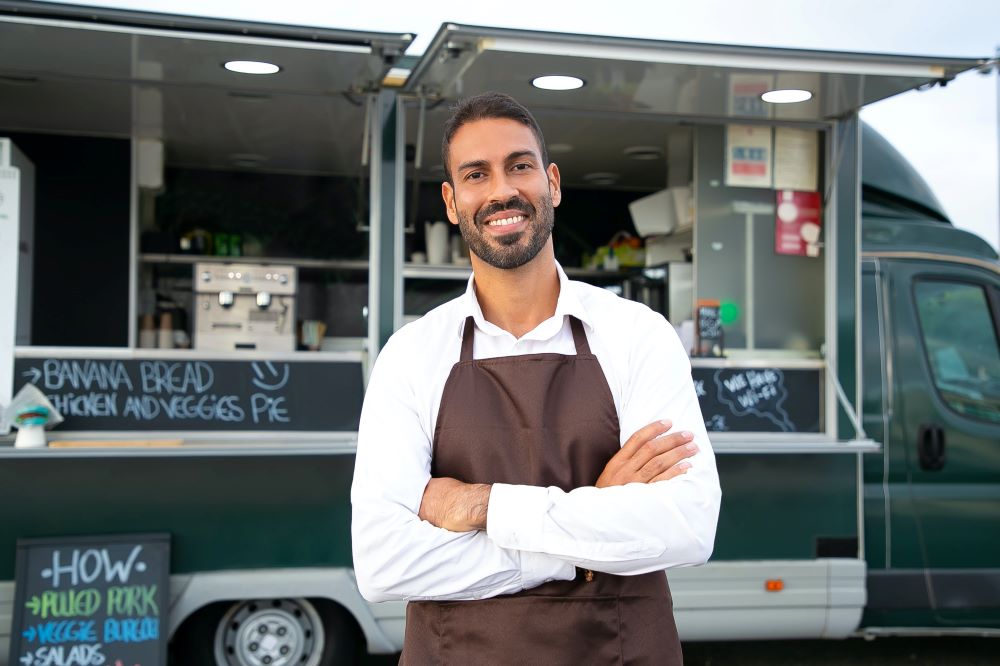
food trucks

General Liability Insurance For Commercial Food Trucks

food trucks
The right food truck insurance policy is essential for anyone operating a mobile food business.

Insurance for food trucks is vital, as it can cover your vehicle, business, and customer-related incidents. Choosing the right commercial insurance broker is essential in starting a food truck business.

Here’s everything you need to know about this insurance.

What Is Food Truck Insurance?

Food truck insurance is a specialized type designed to protect owners and operators from various risks and liabilities associated with running a mobile food business.

This insurance covers potential losses and damages that could occur while operating a food truck.

Who Needs Food Truck Insurance?

Quite simply, food truck insurance is essential for anyone operating a business with a food truck.

Regardless of the scale of operations, whether it’s a small local food truck or a more extensive mobile catering business, having proper insurance is essential to protect against unforeseen accidents, damages, liabilities, or interruptions to your business that could result in financial losses.

Basic Food Truck Insurance Cover

While each commercial insurance broker offers different plans and types of coverage, basic food truck insurance coverage typically includes two cover areas.

food truck liability

General Liability Insurance

General liability insurance for a food truck typically covers:

  • Third-party bodily injury: This covers medical expenses if someone is injured due to your food truck’s operations.
  • Third-party property damage: If your food truck or your operations cause damage to someone else’s property, this coverage helps pay for repairs or replacements.

How much commercial general liability insurance do food trucks need? This depends on your specific business and operational plan.

Commercial Auto Insurance

Commercial auto insurance for your food truck covers:

  • Accidents and collisions: This coverage helps pay for repairs to your food truck if it’s damaged in an accident, regardless of fault.
  • Liability for auto accidents: If your food truck is involved in an accident that causes injuries or property damage to others, this coverage helps cover related expenses.

Other Insurance Coverage You Might Need

We’ve covered the foundations of food truck insurance. However, depending on your food truck operation’s specific needs and risks, additional business insurance coverage options might be worth looking into.

While this raises food truck insurance costs, it could be valuable for the right business.

food spoilage

Here are some extra options to consider:

  • Business Interruption Insurance: Helps cover lost income and expenses if your food truck business is temporarily unable to operate.
  • Commercial Umbrella Insurance: Provides additional liability coverage above the limits of your general liability, commercial auto, or other primary policies in case of a significant claim.
  • Inland Marine Insurance: Protects movable or specialized property (e.g., equipment, tools) when transported over land. It can cover items off your premises, such as when your food truck is in transit.
  • Product Liability Insurance: Covers costs if someone claims your food products harmed them.
  • Liquor Liability Insurance: If your food truck serves alcohol, this insurance covers liabilities from alcohol-related incidents, such as injuries or property damage.
  • Employment Practices Liability Insurance: Protects your food truck business against claims related to employment issues like discrimination, wrongful termination, or harassment.
  • Equipment Breakdown Insurance: Covers the cost of repairing or replacing essential business equipment that breaks down due to mechanical or electrical issues.
  • Food Spoilage and Contamination Insurance: Reimburses the cost of spoiled or contaminated food due to equipment failure, power outages, or other covered causes.
  • Workers’ Compensation Insurance: Provides medical benefits and wage replacement to injured employees. It’s mandatory in most states if you have employees working on your food truck.
  • Hired and Non-Owned Auto Insurance: Covers liability expenses when using vehicles not owned by your business (such as employee-owned vehicles used for business purposes) or renting a vehicle for business use.

food truck
What Influences Food Truck Insurance Premiums?

It’s important that you understand how food truck insurance costs are calculated. Here are some of the main factors that can influence food truck insurance premiums.

Type of Coverage

The extent and types of coverage you choose for your food truck insurance will directly impact the premium.

More comprehensive insurance for food trucks or higher coverage limits typically result in higher premiums.

Location

The area where your food truck operates can significantly affect insurance costs.

Urban areas with higher population density or areas prone to higher crime rates or traffic accidents might have higher premiums on the food truck insurance policy.

Value of Equipment and Assets

The value of your food truck, cooking equipment, appliances, and other assets you want to insure will influence the costs of food truck insurance policies. Higher-value items generally mean higher premiums.

Claims History

Your insurance history and past claims for food truck businesses play a role in determining premiums.

If you’ve had previous claims or a history of frequent claims, it might increase your food truck insurance cost.

Driving Record

If your food truck requires commercial auto insurance, the driving records of the operators can affect premiums. A clean driving record usually results in lower premiums.

Business Experience

The length of time your food truck business has been operating can influence premiums. Established businesses with a track record of safe operations might qualify for lower rates.

food truck owner

Security Measures

Installing security systems, fire suppression systems, or implementing safety protocols can potentially lower insurance premiums by reducing risks of theft, fire, or accidents.

Number of Employees

Your number of employees can impact premiums, especially for workers’ compensation insurance and insurance covering medical costs or lost wages. More employees may result in higher premiums.

Final Thoughts

Take time to choose and compare food truck insurance policies carefully. Like commercial property insurance, the right policy can enormously affect how your business operates.

Looking for financing for a new commercial vehicle? Then get in touch with us at Mission Financial Services – we make the process of obtaining financing easy.


Archives

Sign Me Up!

Stay up to date with the latest news in the commercial trucking industry.

Contact Us
close slider