Office: (404) 975-4800

loan

When Truck Financing Costs More Than Expected: A Practical Guide for Owner-Operators

When Truck Financing Costs More Than Expected: A Practical Guide for Owner-Operators

Mock-up of tractor-trailer, coins placed on light background. Concept. Tariffs, calculation, freight transport costs by truck.

Many owner-operators begin shopping for a truck with a rough estimate of what the monthly payment might look like. Once offers arrive, though, the actual truck financing costs can be higher than expected.

While that can be frustrating, receiving an approval still means a lender is willing to fund the truck purchase – which is good news!

Understanding why financing terms change and how they affect your truck payment helps buyers make better decisions before signing a loan contract.

Below, we discuss the factors that influence commercial truck loans and how to structure financing so the purchase remains affordable for your business.

Why Truck Financing Costs Sometimes Come In Higher Than Expected

Several factors influence the cost of truck financing, and many of them relate to how lenders evaluate risk:

  • Credit history: A strong credit profile usually leads to lower interest rates, while limited credit or past issues can place the borrower in a higher-risk category. Lenders rely on credit reports to evaluate how reliably a borrower has handled debt in the past.
  • Time in business: Experienced operators with established revenue often qualify for better financing terms than first-time buyers. Lenders view a stable business history as a sign that the borrower can handle long-term obligations.
  • Type of truck: A used truck with high mileage may carry more risk than a newer vehicle because repairs and downtime can affect the borrower’s ability to make payments. Older trucks can still be good purchases, but lenders sometimes adjust loan terms to account for potential maintenance costs.
  • Down payment: A larger down payment reduces the amount owed on the loan and lowers the lender’s exposure. Buyers who contribute more capital upfront often receive better terms.
  • Market interest rate: The broader market conditions influence commercial lending. When interest rates rise across the financial markets, financing for vehicles and equipment typically increases as well.
Caucasian Semi Truck Driver Hitting the Road

What Higher Rates Actually Mean for Your Monthly Payment

When financing costs rise, many buyers focus only on the interest rate. While the rate matters, what really affects day-to-day operations is the monthly payment and the loan’s total cost over time.

Consider a simplified example for a commercial truck purchase. Assume a buyer finances $120,000 for a truck over a five-year loan term.

  • At a 7% interest rate, the monthly truck payment might be around $2,376.
  • At a 10% interest rate, the monthly payment increases to roughly $2,549.

That difference may not seem huge at first glance, but it changes the total amount paid over the life of the loan.

A higher rate increases the total cost of financing even if the monthly payment remains manageable. Over several years, those small differences in interest can add up to thousands of dollars.

Buyers should evaluate both the monthly affordability and the loan’s long-term cost. Tools such as affordability and payment calculators can help estimate how different rates and terms affect the total repayment amount.

The Difference Between Interest Rate, APR, and Total Loan Cost

Many truck buyers assume the interest rate tells the whole story, but financing costs involve several numbers that work together.

  • Interest rate: The interest rate is the annual rate used to calculate interest on the loan’s principal. It drives how much interest you pay as you make payments over time.
  • APR: The annual percentage rate (APR) is a standardized rate that reflects the yearly cost of borrowing by combining the interest rate with certain lender-required finance charges (such as origination fees).
  • Total loan cost: The loan term affects what you pay overall. A longer repayment schedule usually lowers the monthly payment, which can help with affordability. However, because you’re borrowing for longer, interest has more time to accrue. So it often increases the total amount paid over the life of the loan.
Truck Drivers Shift Work Vehicle Keys Transfer

How to Plan for Financing Before You Shop

Truck financing becomes easier when buyers prepare before they start shopping for vehicles. A little preparation helps determine what you can comfortably afford and reduces surprises during the approval process.

  1. Start by reviewing your credit report. Checking your credit early gives you time to correct errors or improve your credit profile before applying for financing.
  2. Next, evaluate your business income and expenses. Lenders want to see that your business’s cash flow supports the proposed payment. Gathering bank statements and financial records in advance helps demonstrate stability.
  3. It is also important to understand typical down payment requirements. Many commercial truck loans require a percentage of the purchase price upfront. Planning for that amount prevents delays when the right truck becomes available.
  4. Finally, think carefully about the type of vehicle you truly need. Buying the right truck for your workload often matters more than buying the newest model available.

What to Do if Your Loan Offer Is Higher Than Expected

If your truck loan offer comes back with a higher rate than you anticipated, the first step is to understand why.

Lenders evaluate several factors when pricing a loan, including credit history, time in business, the type of truck being financed, and the size of the down payment. Asking your lender to explain what influenced the terms can help clarify whether the rate reflects credit factors, market conditions, or the structure of the deal.

Next, look at ways to adjust the financing structure. Increasing the down payment, extending or shortening the loan term, or selecting a lower-priced truck can sometimes make the monthly payment more manageable. Even small changes to the loan structure can improve affordability.

It is also helpful to evaluate the loan in the context of your business. If the truck will generate reliable revenue, the key question is whether the payment fits comfortably within your expected cash flow.

Finally, remember that financing terms are not always permanent. Borrowers who make consistent payments and improve their credit profile may be able to refinance later at a lower rate.
Aerial top view of truck and cargo trailer unloading in logostics center.

Protecting Cash Flow When Financing Costs Are Higher

Commercial truck ownership involves more than the purchase price. Operating expenses such as insurance, maintenance, and fuel all affect profitability.

When financing costs rise, protecting cash flow becomes especially important. Structuring payments so they align with expected revenue helps prevent financial stress.

For example, a truck working consistent regional routes may generate predictable income. Matching the loan payment with those revenue patterns keeps the business stable.

Operators should also plan for maintenance. Even well-maintained vehicles eventually require repairs. Setting aside funds for suspension work or engine service helps avoid unexpected disruptions.

Insurance costs also influence affordability. Higher-value vehicles often carry higher insurance premiums, which can affect the overall cost of ownership.

Balancing all of these factors helps ensure the truck supports the business rather than becoming a financial burden.

Conclusion

When truck financing costs come in higher than expected, it does not automatically mean the purchase is a bad decision. What matters most is whether the monthly payment aligns with your business revenue and long-term goals.

Understanding how interest rates, loan terms, truck condition, and down payments affect the total cost of financing helps buyers make informed decisions.

If your truck financing costs came in higher than you expected, you don’t have to fight your way through the next step.

Mission Financial Services helps owner-operators, first-time buyers, and small fleets secure funding for commercial trucks with terms built around real-world cash flow, not perfect-credit assumptions.

So, if you are trying to lock in a workable monthly payment and get the right truck on the road without stalling your business, start your credit application with Mission Financial Services today.

Frequently Asked Questions

Why Is My Truck Loan Rate Higher Than I Expected?

Truck loan rates depend on several factors, including credit history, time in business, the type of truck being financed, and current market interest rates. Borrowers with limited credit or smaller down payments may see higher rates because lenders must account for additional risk.

Can I Lower My Commercial Truck Loan Rate?

Improving your credit score, increasing your down payment, or selecting a lower-priced truck can sometimes lower the interest rate lenders offer.

Does a Larger Down Payment Help?

Yes. A larger down payment reduces the amount borrowed and lowers the lender’s risk. This can sometimes result in better loan terms and a smaller monthly payment.

Should I Wait for Rates to Drop?

Interest rates move with broader economic conditions. While waiting may lower financing costs, it could also delay income opportunities if you need a truck for work.
How Much Down Payment Do You Need to Lease a Semi Truck?

How Much Down Payment Do You Need to Lease a Semi Truck?

Leasing a semi truck can be a convenient way to get on the road, but the deal can feel unclear until you know what you will actually need upfront. The first question most drivers ask is the right one: how much of a down payment will you need to lease a semi-truck?

The honest answer is that it depends on numerous factors, including your credit score, credit history, the truck you choose, and how the lease is structured.

Two drivers can look at the same truck and end up with very different down payment requirements and monthly payment numbers.

Below, we go over typical down payment ranges and the specific factors lenders consider when setting terms.

How Much Down Payment To Lease A Semi Truck: Quick Answer

For most drivers, the down payment to lease a semi truck typically falls between 0% and 15% in advertised down payment, depending on how the lease is structured and what costs are due at signing.

Here’s how it usually breaks down in real-world deals:

  • Low end (0%–5% down): Often limited to the first monthly payment plus fees, not truly zero cash due. These structures usually come with higher monthly payments and are most common for drivers with strong credit and stable income.
  • Mid-range (5%–10% down): A common range for many owner operators. This level helps secure approval while keeping the monthly payment manageable without draining cash flow.
  • Higher end (10%–15% or more): More likely when credit is challenged, the truck is older, or the lease carries more risk. A higher down payment reduces lender exposure and can improve approval odds.

Because down payment requirements vary so widely, working with a lender that understands the trucking industry can make a major difference.

For example, at Mission Financial Services, we focus on flexible commercial truck financing structures and fast approvals, helping drivers explore realistic and achievable options.

What Determines Your Down Payment For A Semi Truck Lease

There is no single down payment number that applies to every driver or every deal. When lenders decide how much money you need upfront, they look at a combination of credit, business stability, the truck itself, and how the lease is structured.

Each factor affects risk, and higher risk usually means more cash required at signing.

Here are the main factors lenders consider when setting a semi truck lease down payment:

  • Credit score and credit history: Strong credit often qualifies for lower down payments and more flexible terms. Bad credit or a thin credit file typically leads to higher down payment requirements.
  • Time in business and business history: New businesses and first-time buyers are considered higher risk, even with solid income. Established fleets with consistent revenue usually have more options.
  • Truck age, condition, and type: New semi trucks with controlled mileage are easier to place in a lease than older, high-mileage used semis. Truck type and expected value at the end of the lease also matter.
  • Monthly payment target and lease term: A longer lease with lower monthly payments may require a larger down payment. Shorter lease terms often shift more of the cost into the monthly payment instead.
  • Cash flow and bank statements: Lenders review how money moves through your business. Strong, steady cash flow can sometimes offset weaker credit or limited business history.

Leasing Vs Financing Options: Why Down Payments Work Differently

Leasing a semi-truck and financing a truck are not the same, and down payments work differently in each structure.

With a lease, the lender or leasing company typically retains ownership of the vehicle. Because the truck is not becoming your asset right away, the lease shifts risk differently. Mileage limits, wear guidelines, and end-of-lease conditions all factor into the payment requirements.

With a semi truck loan or financing, you are purchasing the vehicle. The down payment creates equity in the truck from day one. While financing often requires a larger down payment and longer loan term, it can be a better fit for drivers focused on ownership and long-term value.

Commercial vehicle financing may make more sense if you plan to keep the truck for many years or build equity as a part of your business finances. Leasing can be a convenient way to manage short-term costs and preserve cash, but it often leads to higher total costs over time.

Additional Upfront Costs When Leasing A Semi-Truck

The down payment is only part of the upfront cost to lease a semi truck. Even if the monthly payment looks affordable, these items can change what you can realistically budget before you take delivery.

Common upfront costs when leasing a semi truck include:

  • First payment and timing: Often due at signing, and some dealers collect the first and last payment up front.
  • Security deposit: Often required for new businesses or borrowers with limited credit. It’s typically refundable at the end of the lease, but it does tie up cash for the duration of the term.
  • Insurance down payment: Frequently one of the highest upfront costs, especially for an owner-operator with new authority.
  • Permits and compliance costs: IRP and IFTA setup, plates, and other required items can hit early in the process.
  • Sales tax, registration, and documentation fees: Sales tax varies by state and lease structure, but it adds to the total cost at delivery.
  • Maintenance reserves and warranty coverage: Used truck deals often require a stronger maintenance plan, and setting aside cash up front can reduce the risk of missing a payment later.

How To Lower Your Down Payment on a Commercial Truck

Lower down payments usually come from lowering lender risk. You do not have to be perfect, but you do need to make your credit application easy to approve and easy to price.

Here are practical ways to improve approval odds and reduce the down payment requirement:

  • Strengthen your credit profile before the credit check: Paying revolving balances and fixing errors can raise your credit score faster than most drivers expect. Even a small improvement can reduce your payment requirements or move you to better financing options.
  • Match the truck to lender guidelines: A new semi or a late-model used semi that fits common lender rules (reasonable miles, standard truck type, clean condition) is usually easier to secure with lower down payments than an older, high-mileage used truck.
  • Bring documentation that proves stability: Bank statements show cash flow and spending patterns. Tax returns show business history. Settlement statements and contracts show income consistency. Strong documentation can help offset bad credit or limited time in business.
  • Control your monthly obligation picture: Lenders look at whether the payment fits your budget. If you already have high debt payments, you may be pushed toward a higher down payment or higher monthly payments. Keeping debt-to-income in check improves the financing work behind the scenes.
  • Have a clear plan for the lease term and end of the lease: Lenders pay attention to long-term plans. If the plan is unclear, the deal is riskier. If your plan is stable, the structure can be more flexible.

Frequently Asked Questions

Can I Lease A Semi Truck With No Money Down?

True $0 down is uncommon once the paperwork is finalized. In most cases, “no money down” still means an upfront cost like the first payment, fees, or a security deposit, and the deal may be offset with higher monthly payments.

What Credit Score Do I Need To Lease A Semi Truck?

There is no single credit score cutoff because lenders also look at credit history, income documentation, and business stability. With bad credit, you may still qualify, but you may need a higher down payment or a structure similar to semi truck financing.

Do I Need A Down Payment If I Have A Co-Signer?

A co-signer can improve approval odds, especially if they have strong credit and a stable income. Even so, many lenders still require a down payment to reduce risk and confirm the borrower can contribute cash to the deal. A co-signer may also help you qualify for a better interest rate or more flexible truck financing terms.

Aerial view semi truck trailer cargo on mountain curve road, Semi truck trailer cargo business logistic transportation on green forest road curve, Semi truck delivery asphalt road green forest tree.

Conclusion

Locking down the numbers early keeps you in control of the deal instead of scrambling at the finish line.

Once you know what you can put down and what you need to keep in reserve, it’s much easier to choose terms that fit your monthly budget, protect cash flow, and support the way you want to run your business long term.

If you are comparing a lease to semi-truck financing, or want to see what approval could look like, Mission Financial Services can help you map out the most practical financing options. The right plan can protect your business vehicle and keep your finances steady as your business grows.

Get in touch with us or start your credit application online for fast approvals and comprehensive support.

Truckload Spot Rate Spikes: What an 8% Jump Signals for 2026

Truckload Spot Rate Spikes: What an 8% Jump Signals for 2026

Truckload spot rate spikes have captured attention across the freight market after an 8% jump recorded over a recent two-week period.

For owner-operators, first-time buyers, and small fleets, this is a data point that hints at how fragile current market conditions remain and how quickly opportunity and risk can appear.

Many drivers are still operating through a prolonged freight recession, with demand remaining weak in several lanes and elevated costs continuing to pressure margins.

Understanding why sudden rate spikes happen and what they may signal for 2026 helps drivers decide when to secure financing before the next swing.

Why This Spot Rate Jump Matters

The 8% jump refers to truckload spot rates excluding fuel, a metric commonly tracked through the National Truckload Index (NTIL). While spot rates are not a perfect measure of overall market health, they are widely viewed as one of the fastest indicators of how carriers perceive the value of their services in real time.

Over the two-week period from November 19 to December 4, 2025, spot rates rose more sharply than they did around the same holiday window in the previous two years. Although similar seasonal moves have occurred in the past, the defining difference this year has been how sudden and abrupt those increases have become.

This pattern reflects a market that remains stuck between excess capacity and recovery. Capacity has been slowly exiting since early 2023, but weakening demand has offset much of that tightening. As a result, carriers appear hesitant to raise rates until it becomes absolutely clear that market conditions allow them to do so.

That hesitation may be masking a tighter underlying market than headline indicators suggest. When disruption does occur (whether from seasonal pressures, regulatory friction, or temporary capacity pullbacks), pricing reacts quickly.

These short, sharp rate movements highlight how fragile current market conditions remain and why volatility, rather than a smooth recovery, is increasingly shaping expectations for the period ahead.

View from the driver's seat of a truck of the highway and a land

Spot Rates Explained

Spot rates are the price you get for a load right now, usually booked one load at a time. They are different from contract rates, which are negotiated in advance and stay more stable over weeks or months.

Shippers use the spot market when they need quick coverage. That usually happens when they have a last-minute load, a route problem, or their usual contract carrier cannot take it.

If contract carriers are increasingly unwilling to haul certain freight or lanes, more loads spill into the truckload spot, and prices can change fast.

Spot rates move quickly because they react to what drivers are actually doing in real time.

If a lane gets short on trucks, prices jump. If winter weather slows down pickups and deliveries, fewer trucks are available, and rates climb. If the weather clears or more trucks reposition into that lane, rates can drop just as fast. Contract rates usually lag behind because they take longer to renegotiate and update.

This is why spot pricing is often an early signal for the freight market.

Spot rates react immediately to market conditions while contract rates adjust more slowly over time. Spot markets often reflect changes before contract pricing does, especially during seasonal disruptions or periods of regulatory pressure.

What’s Driving These Sudden Spikes Right Now

Truckload spot rate spikes rarely come from one single cause. Sudden rate spikes are happening because the system is less forgiving, so small disruptions create an outsized reaction.

These are the current drivers:

  • Capacity is thinner than it looks: Carrier details analysis suggests carrier attrition continues after the prolonged freight recession, with many motor carrier property authorities exiting. That can push carriers offline and reduce the cushion in trucking capacity, even when the truckload market still shows ample capacity on paper.
  • Winter weather disruptions create lane shortages: Winter weather across the Midwest and Northeast can disrupt networks and reduce available equipment. When that happens, shippers push more freight into the spot market to cover missed loads, which can raise rates quickly.
  • The market is hyper-sensitive right now: Equipment costs remain high, interest rates are elevated, and demand remains weak in parts of the housing market and the broader economy. Under normal seasonal pressure and typical seasonality, the market’s transition can swing fast, creating considerably more volatility.
  • Costs and regulatory pressure still matter: Higher costs and regulatory pressure continue to affect many transportation providers, which can contribute to ongoing carrier exits over time.

What This Could Mean For 2026 Freight Conditions

The most important point is that this does not confirm a durable market recovery. While some headlines suggest improvement, most freight data still shows uneven demand.

Freight demand remains below pre-recession levels, and increases in freight volumes have been limited to specific regions rather than across the entire truckload market.

Looking toward 2026, the more likely scenario is continued volatility rather than a smooth rebound. Spot rates may rise for short periods, fall back, then rise again as seasonal disruptions affect already fragile networks.

Contract rates could follow in select lanes, but the broader market has not fully worked through the excess capacity built up earlier in the cycle.

For carriers, this environment creates short, temporary leverage windows. When truckload spot rates move closer to contract rates, carriers gain negotiating power. Those moments tend to favor operators with strong cash flow, reliable equipment, and disciplined planning. Operators who are unprepared may struggle once rates normalize again.

Winding road in the forest in the fall with truck on the road

What Owner-Operators And Small Fleets Should Do Next

Truckload spot rate spikes should change how you operate this week, not just how you feel about the market. Treat them as signals that market conditions are tightening temporarily in certain lanes, not guarantees of higher earnings everywhere in the freight market.

The first step is setting a clear rate floor. Know your estimated cost per mile, using fuel, insurance, maintenance, and financing, then add your profit margin on top. If spot rates fall below that number, it is often smarter to reposition, shorten the run, or wait for a better reload than to run freight that damages your weekly average.

Next, tighten your lane plan so you can reload without burning unpaid miles. Lane discipline means sticking with lanes that repeatedly produce freight volumes and predictable reloads.

In practice, that often looks like running repeatable loops between major freight markets, where load options stay steady, and deadhead is easier to control. Chasing one high-paying load into a thin market can look good on the rate confirmation, but it often turns into extra deadhead and a lower weekly average once the next load is harder to secure.

Then, choose loads that protect your cash flow. In a volatile spot market, smart load selection means prioritizing shippers and brokers with reliable payment terms. Avoid freight that creates long waits, inconsistent schedules, or a difficult reload position.

How Financing Strategy Changes When Rates Start Moving

When spot rates swing week to week, your revenue becomes less predictable, even if you are hauling consistently. In a tighter underlying market, that unpredictability can be frustrating because you may see brief surges without enough consistency to count on them for monthly planning.

That is also why lenders mitigate risk by focusing on stability instead of your best week. Most commercial truck lenders evaluate a few core factors:

  • Credit history: How you have handled past credit, including late payments or charge-offs
  • Down payment: How much cash you can put into the deal upfront
  • Operating consistency: How steady your work history and income look over time

Drivers with bad credit or limited credit history are often turned away by traditional lenders, even when they are running viable operations. That can be a problem in a spot-driven freight market, because cash flow gaps show up quickly when repairs hit or loads soften.

Mission Financial Services is built for that reality. We specialize in owner-operator loans, first-time buyer loans, bad credit loans, and commercial truck repair loans designed to help drivers stay on the road and reduce downtime – even when waiting for a more durable market recovery.

The smartest move is to prep financing before you are forced to act. Having approval in place helps you move quickly when the right truck becomes available or when a repair cannot wait.

Semi truck on highway at sunset

Conclusion

Truckload spot rate spikes offer insight into the market’s transition, but they do not promise a smooth upward trend. The truckload market remains fragile, shaped by weakening demand, carrier exits, and sensitivity to disruption.

For owner-operators and small fleets, success is not about chasing headlines. It is about staying prepared.

Financing that supports repairs and growth at the right time can be the difference between surviving volatility and being forced out when conditions materially worsen.

Ready to get on the road with flexible truck financing? Start your credit application with Mission Financial Services today.

What to Consider Before Buying a Commercial Truck

What to Consider Before Buying a Commercial Truck

Updated October 2026

Before buying a commercial truck, match the truck’s weight class to the job you need done. Then price the full cost of ownership and line up financing before you shop. The weight class sets your licensing needs, insurance costs, and tax filings.

A truck is a major investment for a small business. The wrong pick can leave you paying for a truck that can’t do the work.

Key Takeaways

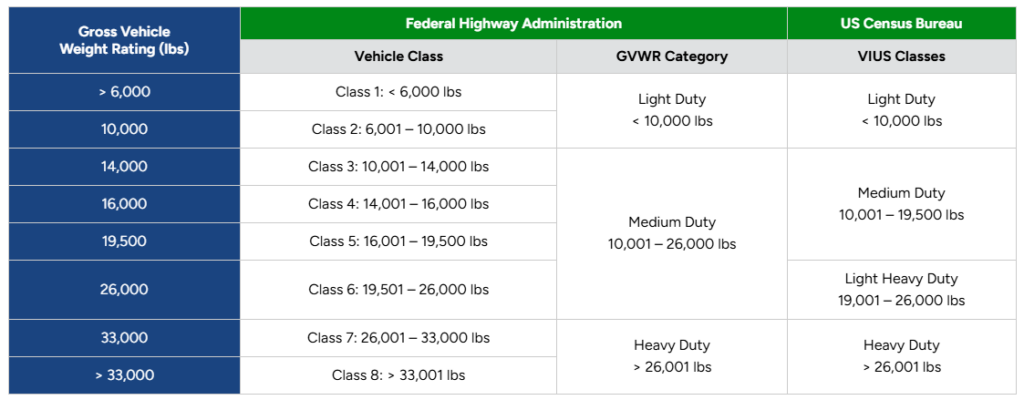
  • A truck’s gross vehicle weight rating (GVWR) sets its class, from Class 1 to Class 8.
  • Trucks over 26,000 pounds are heavy-duty and usually need a CDL to drive.
  • Budget for the total cost of ownership: fuel, insurance, maintenance, and taxes, on top of the sticker price.
  • Trucks with a taxable gross weight of 55,000 pounds or more owe the federal heavy vehicle use tax.
  • Get a pre-purchase inspection and an engine data report before you buy a used truck.
  • Most buyers finance, so get pre-approved before you negotiate.

Commercial Truck Classes by Weight

A commercial truck is a vehicle used mainly for business, like hauling freight or delivering products. Semi-trucks, box trucks, dump trucks, and cargo vans all count.

The industry groups these vehicles into eight truck classifications by weight.

GVWR categories table from Alternative Fuels Data Center

Source: https://afdc.energy.gov/data/10380

Each class covers a range of GVWR, the maximum loaded weight the manufacturer rates the truck for.

The Alternative Fuels Data Center sorts them into three groups:

Class GVWR Category Common examples
1 to 2 Up to 10,000 lbs Light duty Pickups, cargo vans
3 to 6 10,001 to 26,000 lbs Medium duty Box trucks, delivery trucks, chassis cabs
7 to 8 Over 26,000 lbs Heavy duty Dump trucks, semi-trucks

Driving a single truck rated at 26,001 pounds or more generally requires a CDL. Lighter trucks can often operate without CDL requirements, unless they haul placarded hazardous materials or 16 or more passengers.

Many medium-duty trucks start as chassis cabs, which accept bodies built by independent suppliers.

Higher classes cost more to buy, insure, and maintain, and they face stricter rules. So the vehicle type you pick shapes your budget long after you buy it.

How Commercial Trucks Are Used

The work a truck will do should decide which truck you buy. A long-haul carrier and a local plumber have different business models. Their daily operations put very different demands on a truck.

Trucks moved about 72.7% of U.S. freight by weight in 2024, according to the American Trucking Associations. Many businesses rely on commercial trucks for long-distance freight, especially in manufacturing and wholesale distribution.

Construction and contracting companies use heavy-duty trucks to move materials and equipment. For them, durability and payload capacity matter most.

Local delivery and service businesses need trucks that handle frequent stops and tight streets. That’s why cargo vans and medium-duty trucks are common on urban and regional routes. Regional delivery fleets also run a lot of day cabs.

Your cargo type matters too. Furniture, electronics, and dry goods need an enclosed box body for weather protection. Gravel and scrap can ride in an open dump body.

Other businesses use trucks to carry crews, run mobile service units, or haul job-specific equipment.

Buy a truck before you define its job, and you’ll likely pay more. You may also end up with a truck that can’t do the work.

semi trucks in line

How to Buy a Commercial Truck, Step by Step

Buying a commercial truck goes faster when you sort out financing before you shop. Here’s the order we recommend to our borrowers:

  1. Define the job. Write down the loads, routes, cargo type, and payload the truck must handle.
  2. Pick the class. Match the payload to a GVWR class and check whether you’ll need a CDL.
  3. Set a full budget. Add insurance, fuel, maintenance, registration fees, and taxes to the price.
  4. Set up your business. Pick a business structure, like an LLC, before you apply. Lenders may ask for your operating agreement or articles of incorporation.
  5. Get pre-approved. A pre-approval tells you how much truck you can afford before you negotiate. Compare interest rates and loan terms from at least two lenders.
  6. Inspect the truck. Ask for maintenance history and the last annual inspection report. If you’re shopping for used trucks, get a third-party pre-purchase inspection and take a test drive.
  7. Get insurance and close. Lenders need proof of insurance before they fund the loan.

Key Factors To Consider Before Buying A Commercial Truck

Check how the truck will perform in your business before you commit to a purchase. Weigh these factors before you finalize anything:

  • Intended use and payload requirements: Start with what the truck needs to carry. The payload rating sets what it can legally and safely haul, and overloading creates safety and regulatory risk.
  • New versus used options: A new commercial truck comes with manufacturer warranty coverage and current safety features. Used trucks lower the purchase price but can increase maintenance costs, so review the service history. The lower price can leave you more cash for insurance and repairs.
  • Maintenance and operating costs: Fuel efficiency, parts, service access, and downtime all add to the cost of ownership. Fuel consumption also depends on driving habits like idling, speed, and hard braking. A preventive maintenance schedule helps you avoid surprise repairs.
  • Driver requirements: Some trucks require a commercial driver’s license based on weight and configuration.
  • Insurance and compliance requirements: Costs vary by truck class, location, and use. Owner-operators usually need primary liability, physical damage, bobtail, and cargo coverage.
  • Emissions rules: Make sure the truck meets the emissions standards where you’ll run it.

rigs in a row

Engine, Transmission, and Cab Choices

The right truck has specs that fit your routes, your loads, and the person driving it. Check the engine, the transmission, and the cab before you settle on one.

Engine

Most heavy trucks run on diesel engines. Match the horsepower and torque to your loads and terrain.

An underpowered engine works harder on grades and burns more fuel. We ask for the engine and transmission on every vehicle spec sheet, because both affect your loan terms.

Transmission

Automated manual transmissions (AMTs) use a clutch and gearbox like a manual, but a computer handles the shifting. They make long days in stop-and-go traffic a lot easier, especially for newer drivers.

Manual transmissions give experienced drivers full control over gear choice. Some owner-operators also prefer them for heavy hauls and off-road work.

Cab Type and Driver Comfort

Day cabs suit local and regional work. Sleeper cabs add a berth for long-haul runs, where drivers spend nights on the road.

Driver comfort deserves a spot in your buying decision. Seat support, cab noise, and ride quality all add to fatigue over a long shift.

How to Inspect a Used Commercial Truck

Get a third-party pre-purchase inspection on any used truck before you sign. A good mechanic will catch problems the seller won’t mention.

Here’s what the inspection should cover:

  • Maintenance history: Ask for service records, oil change dates, and any major engine or aftertreatment work.
  • ECM download: Ask for an engine control module (ECM) report. It shows engine hours, idle time, and stored fault codes.
  • Oil and coolant: Check for coolant in the oil or oil in the coolant. Either one can point to a failing head gasket, oil cooler, or EGR cooler.
  • Brakes and tires: Measure brake linings and tread depth. Uneven tire wear can point to alignment or suspension problems.
  • Suspension: Look for leaking shocks, cracked springs, and worn air bags. Worn suspension parts hurt ride quality and tire life.
  • Electrical systems: Test the lights, gauges, batteries, and wiring. Electrical faults are hard to trace and can keep a truck off the road.
  • Test drive: Drive it loaded if you can. Listen for knocks, check the shifting, and watch for dashboard warning lights.

Used trucks need more repairs as they age, and age affects your loan too. We finance older commercial trucks, but we recommend choosing one under 10 years old. In our experience, an inspection fee costs far less than one surprise engine repair.

How Much Does A Commercial Truck Cost?

Prices range from about $30,000 for a light-duty van to $150,000 or more for a new semi.

Light-duty commercial trucks, such as cargo vans and smaller box trucks, often start in the $30,000 to $60,000 range.

Medium-duty trucks commonly fall between $60,000 and $100,000, depending on carrying capacity and body type.

A new semi-truck in a standard configuration usually costs $150,000 to $200,000+. Used semi-trucks run about $40,000 to $110,000, depending on mileage and condition.

The final price of a truck also includes dealer fees, optional equipment, and body modifications. Ask about dealer documentation charges up front. We allow up to $500 in dealer doc fees on our contracts.

Heavy trucks carry costs that light trucks don’t. Trucks with a taxable gross weight of 55,000 pounds or more file IRS Form 2290 for the use tax.

Each truck also needs an annual inspection under federal safety rules.

Total Cost of Ownership

The total cost of ownership is the purchase price plus everything it takes to run the truck. That includes the upfront cost, registration fees, insurance premiums, fuel, maintenance costs, and downtime.

New equipment costs more upfront but usually needs fewer repairs in the first few years. A newer truck with better fuel efficiency can also lower operating costs. Compare the total cost over the years you’ll own the truck, not just the sticker price.

Tax treatment depends on the truck’s use and weight. Ask your tax advisor which truck driver tax deductions apply to you.

Financing and Ownership Considerations

Most buyers finance a commercial truck rather than paying cash. Lenders typically look at business income, credit history, down payment, and supporting documents.

Commercial truck loans work differently from personal auto loans. Fewer banks lend on trucks, and interest rates run higher. Commercial truck rates usually run from about 6% to 30%, depending on your credit and the truck.

Banks and credit unions can offer the lowest rates, but they tend to want strong credit and years in business. Dealer financing can move faster, since the paperwork happens at the dealership.

First-time buyers can face different approval rules than established fleets. Check current commercial truck financing rates before you commit to a purchase. When you compare interest rates, compare the loan terms and total repayment too.

Your monthly payment should fit the revenue the truck brings in, without straining day-to-day operations.

Mission Financial Services is a direct lender that has financed commercial trucks since 2000. We respond to applications within four hours and look at your whole credit history along with your score. We work with drivers who have bad credit. We also finance first-time buyers with 20% to 30% down.

Buying vs. Lease-Purchase

Buying with a loan is usually the safer path to ownership. A lease-purchase lets you drive a carrier’s truck now and own it later, but few drivers get there.

The FMCSA Truck Leasing Task Force found that fewer than 1 in 100 lease-purchase drivers end up owning the truck. Its January 2025 report recommended that Congress ban these programs.

A purchase loan gives you full control of the truck and how you run it. Our loans are purchase contracts only, so we don’t offer leases. We do finance lease-purchase buy-outs. The choice between leasing and buying a semi-truck affects your costs for years.

Finance Your Commercial Truck With Mission Financial Services

The right commercial truck fits the job, your full budget, and a loan your cash flow can carry. Before you sign anything, make sure you’ve:

  • Matched the truck’s class and payload capacity to your loads, routes, and cargo type.
  • Picked an engine, transmission, and cab that suit how and where you drive.
  • Priced the total cost of ownership, including insurance, fuel, maintenance, registration, and taxes.
  • Had any used truck inspected, with an ECM report and a test drive.
  • Set up your business and compared rates, loan terms, and total repayment from more than one lender.

That last step is where we come in. Mission Financial Services is a direct lender, and we’ve been financing commercial trucks since 2000.

We finance dealer and private-party purchases in all 48 continental states. On-time car or mortgage payments count in your favor with us, even if your score is low.

Found a truck you like? Contact us with the spec sheet and sales order, and we’ll get back to you within four hours.

Frequently Asked Questions

Is Buying a Commercial Truck a Good Investment?

A commercial truck is a good investment when its work covers the payment and running costs with room to spare. Before you buy, compare the expected revenue per mile with your cost per mile. For a benchmark, the American Transportation Research Institute found trucks cost $2.336 per mile to operate in 2025.

Can I Buy a Commercial Truck for Personal Use?

Yes, but it usually costs more to own. Commercial trucks often need commercial registration and insurance, and heavy trucks may need a CDL to drive. Business tax deductions generally don’t apply to personal use, so check with a tax advisor first.

How Much Is a $70,000 Truck Payment?

At 10% over 60 months, a $70,000 truck loan runs about $1,487 a month. At 20%, it’s about $1,855. Taxes, fees, and insurance come on top. A larger down payment lowers the monthly payment.

What Qualifies As A Commercial Vehicle?

Commercial vehicles are trucks or vans used mainly for business, not personal transportation. That includes vehicles that deliver goods, haul equipment, carry workers, or support service jobs. Weight rating, use, and configuration decide which commercial rules and insurance apply.

Are There Tax Benefits When Buying A Commercial Truck?

Yes, a commercial truck purchase may qualify for tax benefits. A truck used for business may qualify for depreciation deductions. Check with a tax advisor before you count on one.

Is A Cargo Van Considered A Commercial Truck?

A cargo van counts as a commercial truck when you use it for deliveries, service work, or carrying equipment. Trade businesses like cargo vans for their enclosed space, easy loading, and lower running costs.

What Are Chassis Cabs And When Are They Used?

A chassis cab is a truck platform with the cab, engine, and frame, but no cargo body. Businesses use chassis cabs when they need a custom setup, like a utility body, dump bed, or service boxes.

Archives

Sign Me Up!

Stay up to date with the latest news in the commercial trucking industry.

Contact Us
close slider